


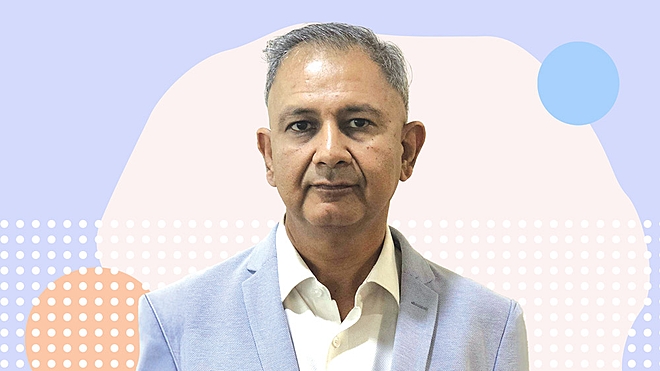

With over 25 years of experience in equities and fund management, Sonam Udasi, Senior Fund Manager at Tata Mutual Fund, has honed a disciplined investment philosophy primarily centred on business quality and scalability.
Udasi adeptly navigates market volatility, focusing on undervalued stocks with strong fundamentals for value funds like Tata Equity PE, while pursuing high-growth opportunities in the Tata India Consumer Fund. He oversees five schemes with assets exceeding Rs 14,700 crore, including the Tata Equity PE Fund, rated three stars by Value Research.
Despite recent challenges in some funds, Udasi's optimism for high-quality companies across market caps, particularly in financials and power, underscores his commitment to long-term wealth creation through meticulous research and adaptability. Edited transcripts
Given the recent volatility in equity markets, do you believe the worst is behind us, or should we prepare for more uncertainty?
From India's perspective, I believe most of the negatives are behind us. Volatility may persist, as we live in an increasingly volatile world, but I find comfort in the valuation bubble bursting over the past four months. While we're not inexpensive, we're within the realm of reasonable valuations. If growth returns, valuations can be justified.
When do you anticipate a meaningful recovery in the small- and mid-cap segments, which have declined significantly in the last four months?
Objectively, the small- and mid-cap indices have only dropped by 16-18 per cent from their peaks. Last year, there was significant hype around SMEs and small caps, which led to speculative buying. Those days seem to be over. However, businesses with viable models—whether large, mid-, or small-cap - have already begun recovering. Some small caps we wanted to buy or increase holdings in are nearing their 52-week highs.
It's not about market cap but the quality of the business and its ability to endure over time. The speculative sentiment prevalent six or seven months ago won't return, as realism is taking hold. More scrutiny is being applied across all market caps, which is positive. Only companies with merit will rise and sustain their gains.
So, you're not expecting further declines in the mid- and small-cap segments moving forward?
High-quality companies across all market cap segments will consolidate and perform in line with their P&L (Profit and Loss) and cash flow projections. Companies lacking cash flow, revenue or P&L potential will continue to struggle, potentially facing further declines. It's a weighing market where quality stands out. Even today, small caps with robust business models and proven growth will command higher valuations. This trend is evident not only in Indian equities but also in global markets.
Can you walk us through your investment philosophy and how it has evolved over your 25 years in equities and fund management?
My philosophy has increasingly focused on the scale and quality of businesses. Over the years, I've incorporated additional considerations, such as management quality, return on equity (ROE) and return on capital (ROC) profiles, industry growth potential, geopolitical impacts and whether a business will remain relevant and competitive over the next five to seven years.
While I evaluate ESG factors, their importance has dimmed in recent years, though this may change. My approach focuses on five key elements: The industry's revenue potential over the next five years, the investability and scalability of companies within that industry, their liquidity, return profiles and capex intensity. I also consider how frequently a company might dilute their equity. When new industries emerge, I assess whether they warrant representation in the portfolio.
Can you elaborate on how you select stocks within your investment universe for the portfolio?
I manage several schemes, including the Tata Equity PE Fund, a value fund, and the Tata India Consumer Fund, which has an expensive trailing P/E in the Tata Mutual Fund scheme universe. These funds require distinct approaches.
For the value fund, I begin by screening for stocks trading below the market or index. This might yield, say, 2,000 stocks. From there, I identify industries with revenue CAGR exceeding the Nifty or Nifty 200 over the next two years. Within those industries, I seek undervalued companies, evaluate their ROE and ROC profiles and prioritise liquidity, favouring index stocks for larger allocations. Growth is paramount—investors choose equities to build wealth, so I target inexpensive companies with growth potential. That's my ideal scenario.
The Tata Equity PE Fund performed well from 2022 to 2024 but has recently struggled, ranking in the fourth quartile among value-based funds. What contributed to this underperformance, and how do you plan to address it?
The underperformance resulted from three factors: Heavy exposure to financials, which underperformed during the downturn; investments in the power ecosystem, which, despite being undervalued, fell as much as mid caps; and market sentiment impacting financial intermediaries.
I remain optimistic about the power sector due to India's demand-supply mismatch, with stocks offering attractive valuations and dividend yields. We took profits at the peak and are selectively adding back. In financials, we hold large banks, financial services firms, AMCs (mutual fund houses) and brokers, which have corrected but are well-positioned for long-term growth. We're increasing allocations in these segments to drive faster compounding over time.
Are these the primary reasons for the underperformance, and has the portfolio changed significantly post-correction?
Post-correction, we reviewed the portfolios. We exited underperforming holdings and reduced our power overweight, though not entirely, and have started adding back after sufficient corrections.
We also maintained our OMC exposure and financial market stocks, confident in their two-to-three-year potential.
That said, we exited most of our defence holdings before the downturn. In short, we are well-positioned in power, financial markets and large financials, holding 6-7 per cent cash to capitalise on opportunities. Recently, we also increased exposure to consumer services.
You mentioned a two-to-three-year outlook for companies. Do you ever adopt longer-term views, such as five to seven years?
We do take longer-term views, but the long term is built on medium- and short-term performance. For example, we've held two positions for seven years, periodically taking profits but retaining them due to consistent growth and management reliability. If a company continues to grow, we hold or add to it, reassessing the investment thesis annually.
When evaluating low P/E stocks, how do you differentiate between a value opportunity and a value trap, and what steps do you take to avoid companies with deteriorating fundamentals?
A low P/E stock is undervalued because it has underperformed the market. We determine whether the decline is structural due to changed industry dynamics, poor management, or temporary, such as an industry slowdown or short-term cash flow issues.
Structural declines indicate a value trap, while temporary ones suggest a value opportunity. Hindsight often clarifies whether a stock was a value or growth investment. True value lies in purchasing an undervalued, growing business, not a perpetually cheap stock that fails to grow net asset value (NAV). Our objective is to ensure NAV growth over time.
The Tata Equity PE Fund can allocate 30 per cent outside the low P/E mandate for growth or thematic investments. How do you decide when to use this flexibility, and what types of non-value stocks have you recently included?
Recently, over the past three to four months, we've added consumer services stocks, which don't fit the value framework but are experiencing triple-digit revenue growth, making them too significant to ignore. The 30 per cent flexibility also allows us to retain stocks that have transitioned from undervalued to valuable but still offer growth potential.
One such stock, held for seven years, represents a 3 per cent portfolio weight and continues to compound effectively. We also use this flexibility to balance the portfolio if it's overly concentrated in a few themes, such as exploring additions in IT, where we're currently underweight but see potential.
Some of your funds, including Tata India Consumer and the Retirement Savings Fund, are in the fourth quartile this year. Are you making adjustments to improve their performance?
To clarify, the Tata India Consumer Fund is in the first quartile, the Retirement Savings Fund is in the first quartile for the past year, the third quartile for two years, and the fourth quartile over three years.
We've made significant improvements by adopting a growth-oriented approach, particularly in consumer services, discretionary, durables and PLI (Production Linked Incentive) names, while avoiding traditional consumer staples. This has driven outperformance, with the Consumer Fund achieving a 19 per cent CAGR over nine and a half years.
Meanwhile, the Retirement Fund struggled during Covid due to limited mid- and small-cap exposure, as we avoided high allocations without in-person management meetings and channel checks. Post-Covid, we added newer companies, boosting performance to the first quartile in the last year. We aim to sustain and improve this trajectory.
The consumption theme, central to the India Consumer Fund, has lagged in recent years. Do you think the recent budget measures will spark a consumption boom, and which segments are you most optimistic about?
The budget measures provide some relief, but taxpayers have multiple priorities, and consumption is just one.
India's consumption theme is compelling due to its inherent tailwind and the presence of high-quality companies in FMCG, retail, consumer durables, auto and media. We diversify with investments in financial services and ticketing businesses, leveraging large, liquid market caps. This approach has enabled the fund to outperform the Nifty and Nifty 500 every year for the past nine and a half years, provided we select investments carefully.
Can you elaborate on how you balance managing the Tata Equity PE Fund's focus on undervalued low P/E stocks with the Tata India Consumer Fund's emphasis on high-valuation growth stocks, and what strategies help you navigate these contrasting styles?
The clear mandates of each fund minimise confusion. The Tata Equity PE Fund has a broader investment universe, while the Consumer Fund is at least 80 per cent focused on consumer-related sectors.
By selecting high-quality stocks in both mandates and prioritising P&L and cash flow growth, we achieve better outcomes over time. Sometimes results come quickly; other times, they take longer, and strategies may temporarily underperform. However, thorough research and adherence to the mandate ensure that investments appreciate over time. I've managed both funds for nearly a decade, and their solid performance demonstrates the effectiveness of these strategies.
Also read: Balanced advantage 'notch higher' than other hybrid funds: Franklin Templeton's Rajasa K
Ask Value Research 
 New episodes every Friday





 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


