


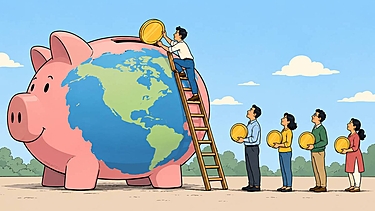
 Anand Kumar/AI-Generated Image

Summary: In the late 1990s, bandwidth was called the ‘new oil’ and Global Crossing borrowed heavily to lay fibre across oceans and continents. Demand did turn out to be limitless. So why did it end in one of the largest bankruptcies in history, and what does that say to a small investor eyeing AI today?
As everyone knows by now, Microsoft has made a voluntary exit offer to 60,000 employees, which is roughly one-fourth of its workforce. That doesn’t mean it’s sacking a quarter of its employees. When it made a similar offer to 9,000 employees earlier this year, about 30% accepted. The interesting part is that these offers are coming in the same year it’s spending about USD 175 billion (about Rs 15 lakh crore) to build AI capacity.
What I find fascinating in the social media commentary on this business is that, depending on which doom-monger you believe, you could end up with one of two opposite impressions of what is going on. One type sees this as evidence that AI is doing so much effective work in big companies (at least in the software industry) that they need far fewer people and, in the near future, will hardly need any. The other camp believes that the huge investments in AI are ruining these companies' finances and that these investments are so far from paying off that they are heading for disaster.
Both views cannot be correct, and the eagerness with which people embrace one or the other tells me no one knows anything. In fact, my mind goes back almost thirty years, to the last time when the whole world thought that the future was being built.
In the late 1990s, when it became clear that the internet would become a major global phenomenon, a small number of companies decided that, in the years to come, an enormous global network of fibre-optic cable would be needed. They borrowed huge sums of money to lay this fibre across oceans and continents. The poster boy of that age was a wonderfully named company, Global Crossing, which was founded in 1997. Global Crossing spent more than USD 10 billion laying fibre crisscrossing the globe and peaked at around USD 50 billion at the height of the dotcom boom in early 2000. In that era, bandwidth was called the ‘new oil’, and everyone was certain demand would be limitless and that whoever owned the data pipes would dominate the future.
As it turned out, demand was limitless, but the timing was all wrong. Data traffic arrived years after the loans came due, so in early 2002, just two years after its peak valuation, Global Crossing filed for one of the largest bankruptcies in history. Much of the fibre-optic cable that it laid down sat dark and unused for years. But others bought that fibre cheaply in the bankruptcy, and it's still in use today, so it’s entirely possible my words are being carried to you on it. The backbone of the modern internet was built; the people who did so went bankrupt, but the asset eventually did its job.
This was not even the first time something like this happened. The British railway mania of the 1840s was a similar story: investors got wiped out, but they funded the first generation of railway lines that carried that economy for decades afterwards.
While my stories sound like ‘all’s well that ends well’, they don't help those trying to invest today. The mountains of money pouring into AI data centres and other assets will eventually be useful, and even indispensable, but that doesn't mean the gains will accrue to those borrowing and spending today.
So what should the small investor do about this revolution in the making? My simple answer is nothing. Neither you nor I, and possibly no one in the world, can tell whether AI is a boon, a disaster, or a bubble. It’s probably all of these, but it's impossible to tell when, or in what order. The temptation to invest on the news is always there, but at this point, from an investment standpoint, our job is to ignore the machine that will keep producing these stories.
As is normal in my advice, dullness is what will protect us. We should own businesses (via equity or equity funds) that we understand well enough to hold through years of noise or, when we need to, sell despite it. Instead of trying to forecast the future, let our savings rate and patience do the work. Broad, low-cost investments are the story I’m most confident in because they've always worked. Use AI to become a better investor, not as something to invest in. Right now, that’s what it’s good for.
Also read: Agreed on the AI bubble. Now what?
Ask Value Research 

 New episodes every Friday



 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


