



Summary: With small- and mid-cap valuations running hot, many investors are getting jittery. But Invesco MF's fund manager believes time changes everything, including how risks play out. In this wide-ranging interview, he explains why short-term earnings worries matter less if you're in it for the long haul, how quality and cash flow still rule his stock-picking process and why it's time for investors to temper return expectations. If you've been wondering how to navigate today's markets with clarity, this one's worth your time.
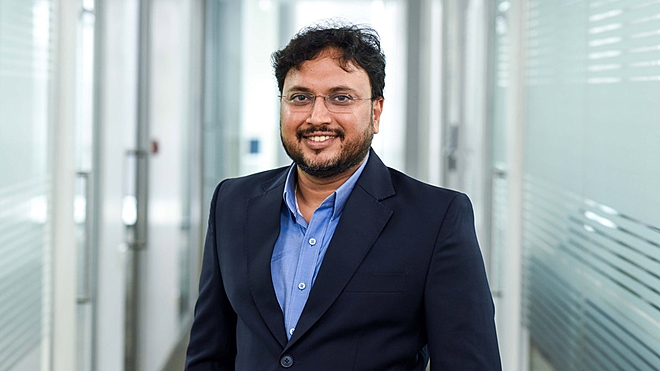
In a market where mid- and small-cap valuations still look stretched, many investors are asking: Will earnings growth keep pace, or are we staring at disappointment? For Aditya Khemani, Fund Manager at Invesco Mutual Fund, the answer depends on how you look at time. Earnings risk, he says, never goes away. But over a three-, five- or 10-year horizon, it matters far less.
With nearly two decades in equities, Khemani calls India’s current macro backdrop one of the strongest he has seen, even as cyclical slowdowns remain inevitable. He oversees five funds with assets worth about Rs 25,000 crore, including the four-star-rated Invesco Large & Mid Cap and Invesco India Mid Cap, and the five-star Invesco India Smallcap.
In this interview, he shares why valuations must be judged through long-term growth and cash flows, how stock selection has driven performance and what’s keeping the Invesco India Large & Mid Cap Fund resilient.
Mid and small-cap valuations still look elevated despite the recent run-up. Do you think earnings growth can keep pace, or are we staring at the risk of disappointment?
When we talk about equities, earnings risk will always be there. There’s no way to run away from it. In good markets or bad, in strong economies or weak ones, earnings risk is something investors must take in their stride.
The key point is the investment horizon. Whether you’re looking at six months, a year, or five years makes a big difference. For instance, if you entered the market five or 10 years ago, it wouldn’t have mattered which quarter earnings risk showed up; it wouldn’t have significantly affected your long-term returns. But if you entered just two or three quarters ago, then an earnings disappointment would have mattered more.
So yes, earnings risk is always present, even now. But the moment you start thinking in terms of the next three, five, or 10 years, things become much clearer from that perspective.
With slowing global growth, easing inflation and the prospects of more rate cuts, what’s your outlook for the Indian markets going forward?
The first thing to remember is that markets are a function of the economy. If the economy does well, the markets will also do well. I’ve been in the markets for about 20 years now, and I would say that the macro environment we are witnessing today is probably the best we’ve seen in that time.
That said, even when the macro picture looks strong, cyclical corrections are inevitable at different points. From 2020 to 2024, we experienced a “Goldilocks period,” where the economy was recovering and optimism was high. However, over the last year and a half, conditions have not been as strong. Rate hikes and monetary tightening had their impact, leading to a slowdown over the past four to five quarters.
However, a couple of quarters ago, the RBI started taking steps to revive the economy, and the government has also been doing its part to ensure recovery. Now, these measures take time, typically two, three, or even four quarters before results are visible. Our view is that, over the next four quarters, we should see things gradually return to normalcy at some point.
However, let me stress that it will be a gradual recovery, not a sharp, hockey-stick rebound. Improvements will likely come at the margin, quarter after quarter, over the next three to four quarters. That’s the base-case view we hold.
If we look at the mid-cap and small-cap segments, do you think earnings growth in this space can justify current valuations, or are we in a zone of excess optimism?
Valuation is always a very subjective matter. Most people look at it simplistically, say the FY26 or FY27 P/E ratio and conclude that a stock is expensive. But that approach can be misleading. India is viewed as a growth market by both foreign and domestic investors, and in growth stocks, 60–70 per cent (or even more) of the value comes from the terminal value, earnings that accrue beyond the next 10 years. So, just looking at the next one or two years, P/E multiples are too narrow an exercise.
On an aggregate basis, I would say the market might be 20–25 per cent expensive. But if you’re backing a company that can grow earnings at 20 per cent or more over a long period, that premium doesn’t really distort returns much. For example, if earnings grow at 20 per cent CAGR over the next decade and you buy the stock 20–25 per cent expensive, your compounding could still be 17–18 per cent CAGR, quite close to the earnings growth.
Of course, if a stock is trading 40–50 per cent above fair value, that’s a clear no-go for us. As long as growth continues and valuations are within a reasonable premium, we’re comfortable holding. However, it’s not just growth; we also consider multiple factors. Our framework is built on high quality and high growth, but equally important is strong cash flow conversion. And, of course, valuations must make sense. You can’t buy any company at any price. We all saw what happened in the bubble of 2000. Many IT companies delivered strong earnings growth, but their stock prices didn’t create wealth over the next 10-15 years because entry valuations were excessive.
So, a 15–20 per cent premium is fine. But paying 50–100 per cent above intrinsic value is dangerous. The reality is that, right now, many investors (liquidity) are chasing quality companies, which makes it harder to find bargains. As an investor, you must decide whether to stick with high-quality, high-growth names at a reasonable premium or move down the quality and growth curve to find cheaper opportunities. It’s ultimately a trade-off each investor has to make, depending on their philosophy.
Mid caps in particular have seen a sharp re-rating and are trading at historically high P/Es. Does their growth potential justify this, or does it raise the risk of a sharp correction if earnings stumble?
Mid caps are a very broad basket. People often talk about them as if they were one homogeneous category, but in reality, the segment includes a wide variety of business models and sectors.
Between 2020 and 2024, almost everything did well, across industries and sectors. But the next two to three years will be very different from that phase. It will be much more stock-specific. During that earlier period, many companies became expensive and even weaker business models started enjoying very high multiples. Going forward, investors will have to be far more selective.
If a business model is strong and you are confident that earnings can grow at around 20 per cent for a long period, then I don’t mind paying a 20 per cent premium. On an aggregate basis, valuations are expensive, and yes, if earnings disappoint, stock prices can correct. But if you’re investing with a three-, five-, or 10-year horizon, these short-term aberrations don’t matter as long as your original investment thesis holds true.
The Invesco India Large & Mid Cap Fund has done reasonably well over the past few months. What has worked for the scheme? Was it stock selection, sector performance, or the overall market environment?
If you look at the period from 2020 to 2024, almost everything did well. It was difficult in that phase to differentiate between good and not-so-good business models. So, as a house, we needed a method in the madness. We decided to focus on themes that were structural in nature, not fads, but sectors and businesses we believed could grow meaningfully over the next three to five years.
From a top-down view, we identified these themes, and then, bottom-up, we picked the right companies and promoters—the “jockeys”—who could execute best within those themes. That’s how the portfolio was constructed. It was sharply positioned, not spread across 80–100 names, but around 45 stocks in aggregate.
Now, if you look at the macro, about a year ago, around the June quarter, post-elections, people began to notice signs of a slowdown. The question then was, how do we continue to generate alpha in such an environment? The answer was to focus on themes that could perform regardless of the macro cycle.
For example, quick commerce was disrupting traditional distribution channels, creating its own growth momentum without needing macro support. Hospitals were another theme, where value migration from unorganised to corporate players was underway. Healthcare is also a non-discretionary service, so it was relatively insulated. Similarly, financialisation of savings is a long-term structural trend, with investors steadily moving from physical to financial assets. These themes allowed us to stay resilient even as the macro slowed.
Now, coming back to your question, did stock selection or sector positioning drive performance? For a fund manager, alpha comes from two sources: allocation effect (sector calls) and selection effect (stock picking). Over the last 12 months, 80–85 per cent of our alpha has come from the selection effect. And that’s true not just for the Large & Mid Cap Fund, but also across our mid-cap and small-cap strategies.
We take pride in being bottom-up stock pickers. We avoid making big sector calls because while they may work sometimes, they can just as easily go wrong. We don’t want to be at the mercy of the market cycle, up one day and down the next. Instead, disciplined stock selection has been the key driver of our performance.
Given how sharp the rally has been, do you expect a period of relatively muted returns ahead? Should investors temper their expectations?
Investors need to temper expectations. The problem is that investor memory is very short-term. The last four or five years have been very rewarding, and people are anchored to those high returns. But it’s unrealistic to expect that to continue.
If India’s GDP grows at 10 per cent in nominal terms, then large-cap companies, on average, cannot deliver more than 10–11 per cent returns. Mid and small caps may do better, but even then, on an aggregate basis, they are unlikely to deliver more than 13–15 per cent returns over the long term.
Therefore, when investors allocate money, they should assume returns in the low teens as a realistic long-term outcome. Within that, there will be phases of no returns for one or two years, followed by periods of strong catch-up. For example, the last year has been broadly flat, disappointing many investors. This could continue for another three to six months; we can’t predict exactly, but eventually, the catch-up will occur.
That’s why trying to time the market for the next three to six months doesn’t work. People who stay invested with a three- to five-year horizon will make meaningful money. Those who focus only on short-term returns will likely be disappointed. This is a long-term game, and the sooner investors internalise that, the better.
Want more such thoughtful perspectives?
At Value Research, we bring you in-depth conversations with fund managers, timeless investing principles and data-backed insights to help you make smarter decisions.
Keep reading. Keep learning.
Ask Value Research 

 New episodes every Friday






 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


