


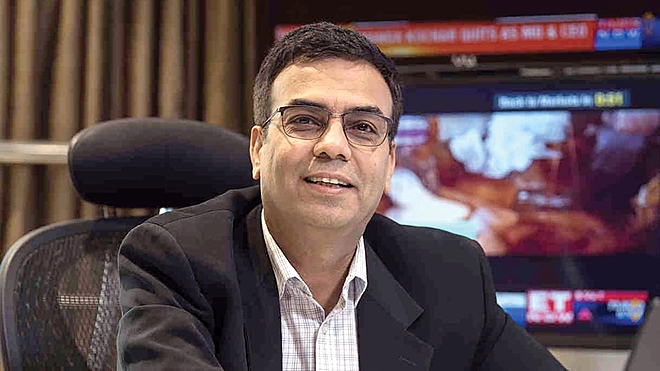
 VRO Team
Summary: Sandeep Tandon's quant Mutual Fund tops one-year charts and sits at the bottom of one-month tables simultaneously, a pattern he defends as design, not flaw. This interview digs into his VLRT timing framework, why he says he's wrong 28 per cent of the time and who should avoid his funds altogether.
Summary: Sandeep Tandon's quant Mutual Fund tops one-year charts and sits at the bottom of one-month tables simultaneously, a pattern he defends as design, not flaw. This interview digs into his VLRT timing framework, why he says he's wrong 28 per cent of the time and who should avoid his funds altogether. Sandeep Tandon runs India’s most debated fund house. On one-year charts, his schemes top almost every category table we publish. But over one-month periods, they sit at the bottom of almost every one. Both statements are true as we go to press. The pattern is not new. In the March 2026 quarter, his equity schemes fell between 10 and 16 per cent. In the June quarter, they rose between 18 and 37 per cent. Tandon had described the same sequence to investors two years earlier, when his funds went from worst in every equity category to first within three quarters. The money followed the returns, as quant now manages about Rs 1.01 lakh crore across 29 schemes, up from a base so small that Tandon calls the rise a case study without a parallel. A third of it sits in one small-cap scheme. No Indian fund house has grown this fast on performance alone. Tandon’s method is also unlike anything else in the industry. He started in 1992 as a trainee at GIC Mutual Fund, helped set up IDBI Asset Management and ran one of the country’s largest proprietary trading desks before taking over this business in 2018. He built an analytics platform first and a fund house second. Tandon argues that timing is not a guess but a calculation, which most of his peers say is impossible. He has now taken the same framework into SIFs, where he can short. We put the numbers to him, including the ones that do not flatter him. Edited excerpts. On timing Your framework says timing is an output, not an input. Explain that to someone who’s been told all their life that timing the market is impossible. For us, timing is a risk-mitigation tool. We call it timing analytics. It is a function of risk appetite, liquidity and valuation analytics, the three components of VLRT. If all three skew to one side, timing skews with them. When many data points endorse the same thing, we take an aggressive bet, depending on whether we are at extreme euphoria or extreme capitulation. And tell me, who does not want to time the market? Every human being wants to time the market. We always say right place, right time. It sits in everybody’s subconscious, including other money managers. People just do not want to accept it. Give us one decision that changed because of the framework. Take March 2020. After the crash, valuations had obviously become attractive. But there is never any certainty that prices cannot fall further. So what matters at that stage is liquidity and risk appetite. Liquidity had collapsed to a 40-year low globally. Risk appetite was at Lehman levels. When risk appetite colla
 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


