


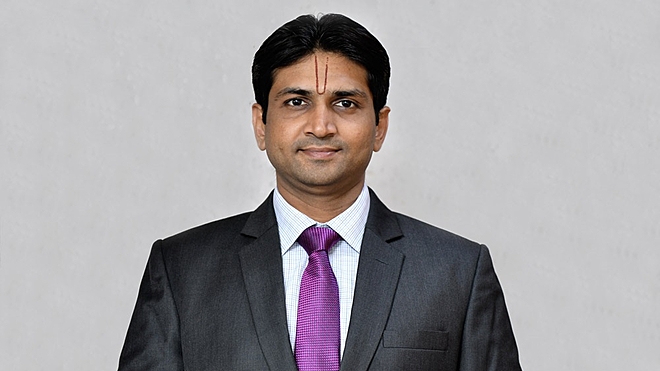
Associated with ICICI Prudential AMC for over 16 years, senior fund manager Mittul Kalawadia manages or co-manages five equity-oriented funds.
In this freewheeling conversation, he shares his views on the market, discusses which sectors look favourable currently and how independent investors should navigate the current market. Here is an excerpt from the interview.
Past one year has been a tale of two halves. Muted for the first six months followed by a rally where markets have surpassed previous all-time highs. In light of the recent resurgence as well as concerns of global economic slowdown, recession and geopolitical risks, how do you view the markets in the short- to medium-term?
Globally, two major events are worrisome. Firstly, the central bankers' decision on QE (Quantitative Easing) versus QT (Quantitative Tightening). If they implement QT, then all asset classes, including financial assets are unlikely to do well. Our understanding is that the US economy is doing well but might slow down. That does not mean it will crash.
The second thing is what happens to oil. Based on demand and supply, it's in a reasonable zone and will remain in a very narrow range. There is neither an oversupply nor a tight market. Some countries like Iran and Venezuela have recently increased their production, and even the US to some extent, suggesting a response from the supply side. As for the geopolitics of it, I'm not an expert. Our expectation is oil prices will remain in a range that we have seen over the last one year. If that is the case, India can absorb the impact of it.
The current account deficit is the important data to track and as long as it is in the current range then it is not going to be an issue. If we end up in a higher priced crude environment plus a tighter central bank in the West, then our current account deficit could come under pressure, and currency may become a bit volatile, but the probability of such a development seems low. So, broadly, we do not expect the economy to slow down meaningfully nor give a big positive surprise either.
Regarding stocks and their valuations, the large cap valuation appears to be reasonable while some of the mid and small-cap pockets are richly valued, exposing investors to execution risk.
Valuations appear to be an integral part of your approach to stock picking. Which sectors are offering value in the current environment?
We see value in a few oil and gas and bank names. In terms of banks, some of the names offer relatively better value with valuations close to four to five-year average level. The only challenge is that earnings may be peaking out and the room for positive surprises look limited. That is why we are positive mostly only on large private banks, which are also among our top holdings. Our picks in these sectors are largely bottom-up.
Apart from that, we continue to be overweight on power and telecom. In power sector, generally, the cycles tend to be long - a 15 to 20-year cycle from one bottom to another. The last cycle started in 2001 and concluded in 2020. We believe power shortage may continue for at least another three to five years. The expected shortage is not as high as it used to be in 2005-08 but is good enough for the company's ROE to expand and deliver good growth guidance over the next three to five years. Valuation wise too they are nowhere close to the peak of the previous cycles. Some of the names are still at around 60 per cent discount to the previous peak.
Telecom is a consolidated industry, and is in fantastic shape today with three players, albeit one of them is a weak player. This essentially means the entry of a fourth player is unlikely at a time when the ROE is still not up to the normal industry mark of 15-17 per cent. If you do not have reasonable ROE, it is very difficult to justify the investment case in the industry, which essentially means that ROE over a period of time will reach normal market level expectations, and that should lead to reasonable growth for some of these names.
Hotels and automobiles are other sectors which we like, but they are more of a bottom-up pick. These are not your pure value plays.
Your monthly market outlook for September 2023 mentions that the Indian economy is currently in the expansion phase, with markets in a boom phase. How should an investor navigate this phase?
From an investor's perspective, our view is that flexi-cap or hybrid funds, which are dynamic in nature, are better suited as the fund manager takes a call regarding the change in allocations between asset classes and market caps. These kinds of funds are better for an investor with a long-term investment horizon.
It is difficult to gauge how long the current economic cycle will last. The only time when you can think about a mean reversion is when you are at the extremes. And right now, we are not at the extremes on either side. We are somewhere in the middle, and it's difficult to predict how long the cycle will last.
ICICI Pru Equity & Debt Fund has been a consistent performer despite having a high TER over the years. Interestingly, its performance has been so exceptional over the past two years that it is in a league of its own. What has contributed to its outperformance?
Firstly, the fund is managed dynamically on both...To read the full conversation, where we understand the reasons behind ICICI Pru Equity & Debt Fund's consistency and how the fund manager selects stocks that enters the portfolio, subscribe to Value Research Premium.
Ask Value Research 
 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


