


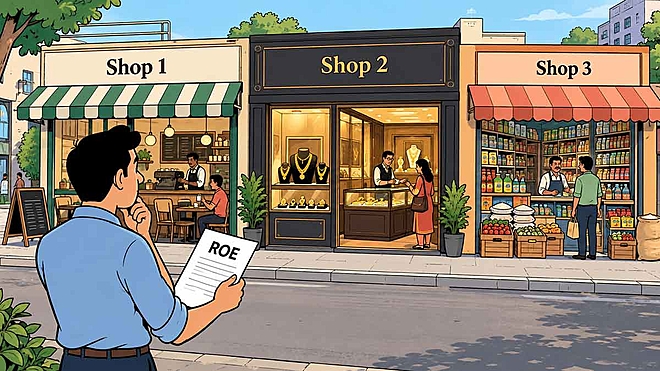
 Anand Kumar/AI-Generated Image

Summary: Return on equity is usually the first ratio an investor picks up, and often the last one they question. Higher is better, and that is where the thinking stops. But the same number can come from three completely different places, and only one of them is worth paying up for.
Think of two restaurants that both make Rs 20 lakh in profit. One charges high prices and earns a fat margin on every order. The other earns very little per order but serves far more customers. Same profit, different recipe.
Companies work the same way. Return on equity (ROE) is one of the first ratios keen stock market investors encounter, and for good reason. It tells us how efficiently a company uses shareholders' money to generate profits, and higher is better. What it does not tell us is which recipe produced it. A software firm, a jeweller and a road builder can all report 25 per cent, and the reasons will have nothing in common. Some sectors earn it on margins, some on volume, some on borrowed money.
A simple method that looks at the forces behind ROE is called ‘DuPont analysis’. Let’s look into it.
What drives the highest ROEs?
ROE is calculated as net profit divided by average shareholders' equity. In simple terms, it tells us how much profit a company generates for every Rs 100 of shareholders' money.
The formula is:
ROE = Net profit / Average shareholders' equity
The higher the ROE, the better. To understand what drives a high ROE, the DuPont method breaks the ratio into three components:
ROE = Net profit margin × Asset turnover × Equity multiplier
Each component tells us something different about the business.
#1 Net profit margin: How much does the company keep?
Net profit margin = Net profit / Revenue
This tells us how much profit a company keeps from every rupee of sales.
For example, a 20 per cent net profit margin means the company earns Rs 20 in net profit for every Rs 100 of revenue.
A high margin can point to strong pricing power, favourable business economics or good cost control. In such businesses, margins can do much of the heavy lifting for ROE.
#2 Asset turnover: How hard are the assets working?
Asset turnover = Revenue / Average total assets
This measures how efficiently a company uses its assets to generate revenue.
An asset turnover of 2 times means the company generates Rs 2 of revenue for every Rs 1 invested in its assets.
Businesses that can generate large sales from a relatively small asset base tend to have higher asset turnover. This is particularly relevant for businesses such as retailers, where inventory can be sold and replenished quickly.
#3 Equity multiplier: Is leverage boosting the return?
Equity multiplier = Average total assets / Average shareholders' equity
This shows how much assets a company has for every rupee of shareholders’ equity. For example, if a company has Rs 100 crore of equity and Rs 300 crore of assets, its equity multiplier is 3x. In other words, every Rs 1 of shareholders’ equity supports Rs 3 of assets. The remaining Rs 2 of assets are funded through liabilities, such as debt and other obligations. A higher multiplier generally means greater use of liabilities, which can magnify ROE.
Different businesses, different profit drivers
To see how this works in practice, we screened companies with a market capitalisation above Rs 1,000 crore, a five-year median and current ROE of at least 20 per cent, and a Quality Score of 5 or more (Quality score assesses a company's quality quantitatively on a scale of 1 to 10, capturing two key aspects: business efficiency and balance-sheet quality). We excluded banks, NBFCs, insurers and holding companies because their business models and balance sheets make ROE less comparable.
We then picked the top five companies for each of the three DuPont components - those with the highest net profit margin, asset turnover and equity multiplier (Do note that each figure is an independent five-year median. Therefore, multiplying the three components may not exactly reproduce the five-year median ROE shown for some companies).
The visuals below show the results.
When margins do the heavy lifting
Top five companies with the highest net profit margins
| Company | ROE (%) | Net Profit Margin (%) | Asset Turnover (x) | Equity Multiplier (x) | Industry |
|---|---|---|---|---|---|
| Indian Energy Exchange | 41.4 | 78.1 | 0.3 | 1.9 | Exchange Services |
| SBI Funds Management | 35.4 | 69.9 | 0.5 | 1.1 | Asset Management Companies |
| HDFC Asset Management Company | 30.1 | 69.3 | 0.4 | 1.1 | Asset Management Companies |
| Nippon Life India Asset Management | 30.5 | 56.9 | 0.4 | 1.1 | Asset Management Companies |
| ICICI Prudential Asset Management Company | 81 | 55.2 | 0.9 | 1.6 | Mutual Funds |
The first thing that stands out is the sheer level of profitability: all five companies have net profit margins above 50 per cent.
Another common thread is the dominance of financial businesses. However, a closer look at the industry classification shows that these are largely asset management, mutual fund and exchange businesses.
These businesses have a fundamentally different model from manufacturers or retailers. They do not need to buy raw materials, maintain factories or hold large inventories to generate revenue. As a result, a much larger portion of their revenue can flow through to the bottom line, explaining their exceptionally high net profit margins.
When turnover drives returns
Top five companies with the highest asset turnover
| Company | ROE (%) | Net Profit Margin (%) | Asset Turnover (x) | Equity Multiplier (x) | Industry |
|---|---|---|---|---|---|
| Gokul Agro Resources | 27 | 1.2 | 5.4 | 3.7 | Edible Oil |
| D.P. Abhushan | 32.9 | 2.3 | 4.6 | 2.6 | Gems & Jewellery |
| Chennai Petroleum Corporation | 35.9 | 3.5 | 4.1 | 2.4 | Oil & Gas Refining and Marketing |
| Lalithaa Jewellery Mart | 24.1 | 2.1 | 3.6 | 3.4 | Gems & Jewellery |
| PN Gadgil Jewellers | 31.8 | 2.5 | 3.2 | 4 | Gems & Jewellery |
This list almost looks like the mirror image of the previous one.
Here, net profit margins are wafer-thin. Four of the five companies have margins below 3 per cent. Yet they manage to generate ROEs of more than 24 per cent. The reason is asset turnover.
Gokul Agro Resources, for instance, has a five-year median asset turnover of 5.4 times. That means the company generates more than Rs 5 of revenue for every Rs 1 invested in its assets.
The three jewellery companies in the list also illustrate why asset turnover can be particularly important in the jewellery business.
Jewellery is a high-value, high-volume business where inventory is bought and sold frequently. Margins on individual sales can be relatively low, but the business can generate substantial revenue relative to its asset base.
When liabilities amplify returns
Top five companies ranked by equity multiplier
| Company | ROE (%) | Net Profit Margin (%) | Asset Turnover (x) | Equity Multiplier (x) | Industry |
|---|---|---|---|---|---|
| Ashoka Buildcon | 49.1 | 12.9 | 0.5 | 9.3 | Construction & Engineering - Diversified |
| Black Box | 33.1 | 2.2 | 2.2 | 7.4 | IT Services & Consulting |
| Schneider Electric Infrastructure | 81.8 | 7.3 | 1.4 | 7 | Electricity Distribution |
| Ashok Leyland | 28.2 | 5.8 | 0.7 | 6.9 | Commercial Vehicles |
| Garden Reach Shipbuilders & Engineers | 23.1 | 10.4 | 0.3 | 6.2 | Shipbuilding & Maintenance |
What they have in common is heavy balance sheets. Roads, factories and shipyards require substantial capital, much of which comes from liabilities rather than shareholders.
Garden Reach shows why a high multiplier does not necessarily mean debt. Its 6.2x multiplier comes entirely from payables and other liabilities, with negligible borrowing. As a defence shipbuilder receives payments from customers before completing vessels, these advances sit as liabilities and raise the multiplier. In this case, the liability is funding working capital rather than creating financial risk.
Ashoka Buildcon is the other kind, where lenders fund capital-intensive road projects. Both can have similar-looking multipliers, but the ratio alone cannot tell the difference. Investors need to look beyond the liabilities.
For genuine borrowers, higher leverage can magnify returns in good times but also amplify the damage when business slows, while interest costs remain.
The takeaway
ROE is a useful number, but it is only the beginning. DuPont analysis helps answer the more important question: Why is the ROE high?
If margins drive it, look for pricing power or competitive advantages. If asset turnover is the key driver, examine how efficiently the company uses its capital. And if leverage is doing the heavy lifting, financial risk deserves closer scrutiny.
The broader point is that no single recipe produces a high ROE. The same 30 per cent ROE can reflect a strong business model or simply high leverage. Comparisons should therefore be made within the same sector, while considering the quality and sustainability of each component.
So, the next time a company flashes an impressive ROE, don't stop at the number. Dissect it to understand what is really driving it.
Also read: When shareholders earn more than the business does
This article was originally published on September 17, 2026.
Ask Value Research 
 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


