


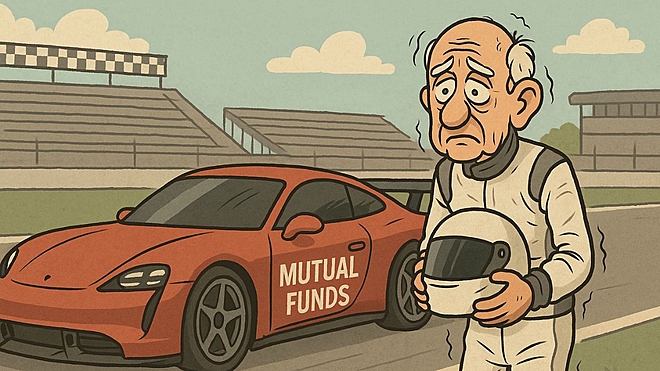
 Aditya Roy/AI-Generated Image


SEBI has just released its first comprehensive investor survey in over a decade, and buried in the data is a number that explains more about Indian household finance than any headline about rising demat accounts or mutual fund inflows: 79.7 per cent of Indian households prioritise capital preservation over returns. Of course, we all knew this, but somehow, the actual number makes it all the more disappointing.
This isn't about financial literacy or market awareness. The survey found that 63 per cent of households are aware of at least one securities market product. Over 21 crore households are aware of these products. Yet, only 9.5 per cent – about 3.2 crore households – actually invest in them. The gap isn't knowledge. It's fear.
Suggested read: Numeracy makes for better investors
The survey identifies the usual suspects: complexity, information overload, and trust issues. But the dominant barrier, cited by 34 per cent of non-investors, is straightforward: fear of losing money due to market risks. This isn't irrational. It's cultural and economic. When your financial buffer is thin, preservation isn't conservative – it’s a matter of survival.
What's revealing is how this fear persists even among those who do invest. Only 36 per cent of current investors demonstrate high to moderate knowledge about securities markets. Even in the highest-penetration segments, roughly half the investors show low knowledge levels. They’re in the market, but they’re not confident or comfortable. This creates a strange dynamic. The survey shows that “quick gains with small investments” and “good for short-term” rank high as triggers for new investors, alongside more sensible motivations, such as long-term wealth building.
The influence ecosystem I’ve written about repeatedly continues its malign work. Personal contacts and financial influencers on social media are the primary sources of information. 93 per cent of investors find these influencers moderately to highly credible, and 62 per cent make investment decisions based on their recommendations.
Suggested read: Investments and influence
Here’s where the survey data becomes uncomfortable: even after investing, risk and uncertainty remain the dominant concern. Lower-than-expected returns, uncertainty about whether to stay invested or exit, and lack of timely market insights are the top post-investment challenges. Nearly 70 per cent of investors cite knowledge gaps – namely, not having accurate information or not understanding statements – as ongoing problems, even after they’ve entered the market.
The policy response has focused on investor education programmes, but the survey suggests these aren’t reaching people effectively. Less than 1 per cent of respondents have attended investor education programmes through webinars or workshops. The preferred channels are social media, mobile apps, and television – not structured education. This creates a peculiar situation. The market grows because some people overcome their fear, often through peer influence or influencer recommendations, but without necessarily acquiring the knowledge that would make them comfortable investors.
The survey identifies potential growth segments, with 22 per cent of aware non-investors expressing an intent to invest in the coming year. But the triggers driving their interest are troubling. “Potential for higher returns” and “quick gains with small investments” are at the top of the list. These are people entering not because they understand the products better, but because they’ve been convinced the rewards outweigh the risks – often the exact opposite of the truth for anyone making decisions based on limited knowledge.
And this is precisely where Value Research Fund Advisor is useful. Our job is to convert abstract “risk” into a manageable process: build an emergency fund, choose the right mix of funds, automate SIPs, review annually, rebalance when thresholds are hit, and keep taxes and costs low. That systematic approach is the antidote to the survey’s two biggest pitfalls – fear and the lure of quick gains. If you already follow this playbook, stay the course. If you know someone still stuck in the 80 per cent, share your checklist with them; sometimes a friend’s simple, repeatable process is more powerful than any webinar.
The deeper problem remains: 80 per cent of households are risk-averse because they can’t afford not to be. Here’s something I have never realised earlier with such clarity: until household incomes rise to a level where capital preservation isn’t the overwhelming priority, securities-market penetration will remain constrained.
Which brings us back to that 79.7 per cent. For most Indian households, capital preservation isn’t a choice – it’s the only sensible strategy given their circumstances. The real question isn’t how to lecture them about markets; it’s whether market opportunities are appropriate for them at all. I know that’s not an optimistic way to end this column, but given the survey results, it’s a realistic assessment.
Also read: Are you a DIY investor?
Ask Value Research 

 New episodes every Friday







 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


