




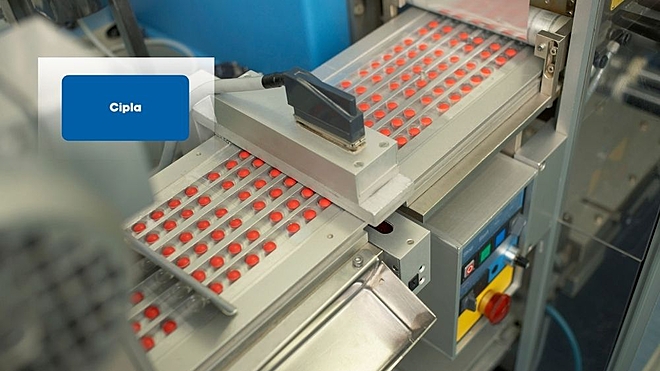
 Adobe Stock
Cipla Ltd is scheduled to report its fourth-quarter results for FY2024-25 (Q4 FY25) on May 13, 2025. Analysts and investors expect a steady performance driven by resilient domestic growth and strong respiratory product momentum, even as the U.S. generics business faces near-term headwinds.
Key Expectations: Revenue and Profit Growth Likely in High Single Digits
According to a Bloomberg consensus, Cipla's standalone revenue is projected to rise approximately 8.7% YoY to ₹6,705 crore, while net profit is expected to grow ~9.7% YoY to ₹1,023 crore. EBITDA is estimated to expand by more than 18%, supported by improving operating efficiencies and a favorable product mix, particularly in the respiratory segment. Margins are likely to stay robust, with analysts expecting EBITDA margins near 23%, compared to 21% in the year-ago quarter.
This performance builds on Cipla's consistent growth through FY2025, where each quarter delivered steady topline gains and strong bottom-line expansion.
Segment-Wise Highlights
India Branded Generics: Core Strength Continues
India remains Cipla's strongest market. The domestic branded generics business, which forms the largest chunk of revenues, is expected to report a 9-10% YoY growth in Q4. This growth is led by chronic therapies like respiratory, urology, and cardiac, which continue to outperform industry averages. A strategic distribution partnership with Sanofi for CNS products also aided topline momentum.
In Q3 FY25, Cipla's India revenue grew 10% YoY to ₹3,146 crore, highlighting its consistent prescription demand and brand recall. For Q4, analysts will closely track whether Cipla sustains this trajectory, reinforcing its leadership in the Indian pharma market.
US Generics: Supply Headwinds Persist
The U.S. business, Cipla's second-largest market, remains under pressure due to ongoing supply constraints of Lanreotide, a key generic oncology product. In Q3, North America sales were flat at $226 million, and this softness is expected to continue into Q4. Analysts forecast a slight ~1% sequential dip in sales to around $223 million due to a mild respiratory season and product shortages.
However, Cipla's existing portfolio, including its market-leading generic Albuterol inhaler, continues to provide a cushion. Stable performance from generic Revlimid (Lenalidomide) also adds support. Investors will be watching for updates on resolving Lanreotide supply issues and the timelines for upcoming launches such as generic Advair and Abraxane, both of which could significantly boost FY2026 revenues.
Respiratory Franchise: Strong Margins, Future Growth Engine
Cipla's respiratory therapy franchise remains a cornerstone of its success. In India, respiratory drugs contributed significantly to the double-digit domestic growth in Q3, and this trend is expected to continue in Q4.
Globally, the company is targeting major inhaler launches in the U.S., including generic versions of Advair Diskus and Symbicort. While the current U.S. respiratory season was soft, limiting immediate gains, Cipla's existing inhalers (e.g., Albuterol) have helped maintain margin strength. Notably, Q3 FY25 saw Cipla deliver record EBITDA margins of 28.1%, partly due to the high-margin respiratory product mix.
API Business: Modest but Strategic Contributor
Cipla's Active Pharmaceutical Ingredients (API) segment continues to deliver moderate growth. Estimated at contributing around ₹560 crore annually, the API division is small but strategically important for vertical integration and third-party sales. Q4 is expected to be stable, with no major surprises. Investors may look for commentary on new contracts or capacity expansions.
Stock Rating and Investment Outlook
According to Value Research Online, Cipla carries a 4-star stock rating (out of 5), underpinned by a well-balanced scorecard:
- Quality: 7/10 - Strong fundamentals and low debt
- Growth: 7/10 - Consistent revenue and profit growth
- Valuation: 5/10 - Fairly valued; neither cheap nor expensive
- Momentum: 7/10 - Positive stock price movement in recent months
These scores suggest Cipla is a fundamentally strong stock with steady growth potential and market confidence. While valuation isn't deeply attractive, consistent execution and upcoming U.S. launches could be catalysts for re-rating in FY2026.
Final Takeaway
Cipla's Q4 FY25 results are expected to close the fiscal year on a steady note, driven by its India branded business and strong respiratory portfolio. Challenges in the U.S. generics space remain a concern but are largely factored into current expectations.
Investors should pay attention to commentary on:
- U.S. product launches and supply resolution timelines
- Full-year margin guidance
- Domestic growth sustainability
- Dividend announcements or capital allocation updates
With stable growth, strong cash flows, and an attractive presence in chronic therapies, Cipla remains a compelling bet for long-term investors looking for a defensive healthcare play with global expansion potential.
For detailed financial information, visit our stock page- Cipla Ltd.
Disclaimer: This article has been written with the assistance of Artificial Intelligence. While our digital writer has been trained to follow our editorial style, we recommend applying a critical eye while reading. Enjoy the story — and keep smiling with understanding!
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


