


 Anand Kumar/AI-Generated Image

Summary: A promoter can pledge shares and a company can hit a weak patch, and both often recover. But what happens when the two turn up in the same stock? We ran a screen to find out, and not every name it caught belongs there. Here is what to check before you decide.
Think of a shopkeeper who has quietly mortgaged his shop to a financier but still raises the shutter every morning. From the street, nothing looks wrong. The trouble starts only on the day the financier asks for his money back and the shop is worth less than the loan.
That is close to what happens when a promoter pledges shares. Promoter pledging is the people who control a company borrowing money and putting up their own shares as collateral. The loan is theirs, not the company's, which is why it never shows up in the company's accounts.
Why the combination is the story
Each flag on its own is survivable. Plenty of promoters pledge to fund an expansion and unwind it later. Plenty of companies pass through a weak patch and recover.
Put the two together and they stop being independent. Collateral is only worth its market value. If the price falls far enough, the lender asks the promoter for more cash or more shares. A promoter who cannot pay watches the lender sell those shares in the open market. That selling pushes the price down, which can force more selling.
Now add a company that is already short of cash. It cannot support the promoter, the promoter cannot support the shares, and the falling price makes raising fresh money harder still. A weak balance sheet turns a margin call into a spiral. That is the risk this screen is looking for.
The data check
We screened the Value Research stock universe for an Altman Z-score below 2.99, a promoter pledge of 30 per cent or more, and a market capitalisation above Rs 500 crore. The Z-score folds several financial ratios into one bankruptcy-risk number: above 2.99 is safe, 1.81 to 2.99 is grey, below 1.81 is distress.
Nine names came through, which is the second thing worth noticing. Most pledging sits in companies with ordinary balance sheets. Most weak balance sheets belong to promoters with little left worth pledging. The overlap is narrow by design.
| Company | Sector | M-cap (Rs cr) | Altman Z-Score | Promoter pledge (%) |
|---|---|---|---|---|
| Afcons Infrastructure | Industrials | 8,921 | 1.6 | 50.2 |
| B L Kashyap and Sons | Industrials | 1,174 | 2.3 | 58.3 |
| BGR Energy Systems | Industrials | 1,869 | -1 | 30 |
| CIAN Agro Industries & Infrastructure | Consumer Staples | 2,796 | 2.3 | 30 |
| India Power Corporation | Energy & Utilities | 620 | 2.4 | 40 |
| Kirloskar Electric Company | Industrials | 859 | 1.9 | 37.5 |
| Shalimar Paints | Materials | 635 | 2 | 52.9 |
| Sical Logistics | Industrials | 686 | -1 | 41.2 |
| True Green Bio Energy | Consumer Discretionary | 617 | 1.9 | 35.2 |
| Screen run on October 8, 2026. Pledge data from the June 2026 shareholding quarter.The scores shown here rest on quantitative historical financial data and should not be construed as recommendations. | ||||
One name to read with more caution
Afcons Infrastructure is the largest company here, and the screen misreads it. Engineering and construction contractors earn thin margins on long project cycles and carry large liabilities, such as customer advances, retention money and payables, that fund the work. The Z-score reads both as signs of fragility, even when they are just how contracting works. The pledge is still worth understanding. The low score, on its own, is partly a feature of the business model. The broader point holds for the other two Construction and Engineering names, B L Kashyap and Sons and BGR Energy Systems.
What to check, in order
Promoter pledging is not a filter on our screener yet, so this is done by hand on the stock page. The screenshots use Afcons Infrastructure to show where each number lives.
1. The Value Research Stock Rating, which already folds quality, growth and valuation into one view
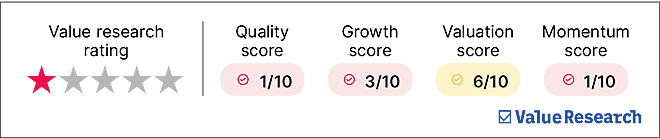
Afcons Infrastructure’s Value Research Ratings
2. The Altman Z-score: which zone, and why
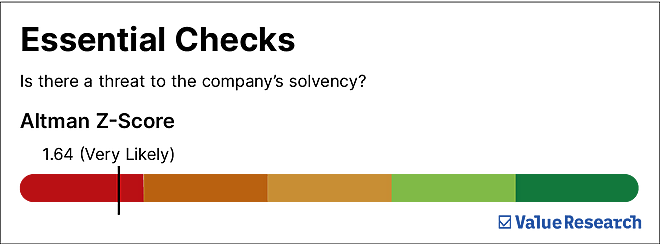
Afcons Infrastructure’s Altman Z-Score
3. The pledge trend across four quarters, and the stated reason. Rising, to service debt, is the real warning
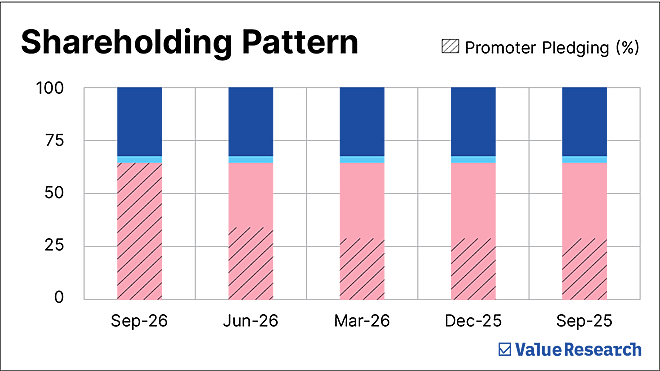
Afcons Infrastructure’s Shareholding Pattern
4. Whether the business pays its own way: debt-to-equity, and interest coverage

Afcons Infrastructure’s Solvency Ratios
The lesson
When a pledged promoter sits on top of a company where the numbers already flag for distress, each problem makes the other harder to fix. Check the direction, not the level.
Pick one company you own and open its shareholding pattern. If the pledged figure is zero, you have learnt something in 30 seconds. If it is not, you have four quarters to read.
Also read: Red flags and green shoots in Q1 FY26
Ask Value Research 
 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


