


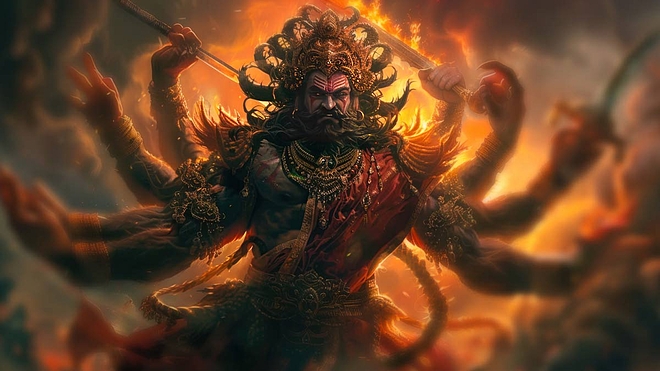
 Aprajita Anushree/AI-Generated Image
Summary: Just like each head of Ravana stood for a vice, your financial life may be under attack from bad habits. This Dussehra, go beyond symbolic fireworks and defeat these 10 destructive money habits that silently eat into your wealth.
Every year, Dussehra reminds us of the timeless story of good conquering evil. Rama’s victory over Ravana was more than a battle of might—it symbolised the fall of arrogance and the rise of righteousness. Every head of Ravana represented a different vice, and all had to be defeated before peace was restored.
Now think about your own financial life. The “Ravanas” we face now are in our own behaviour with money. Left unchecked, they gnaw at your wealth slowly but surely.
This Dussehra, instead of just watching effigies burn, why not identify and conquer the 10 heads of financial mistakes in your life? Here are 10 evil money habits that could be holding you back and how you can cut them down.
1. Impulse buying
“I’ll just browse,” you tell yourself as you open that shopping app. An hour later, a delivery truck is on its way with things you didn’t need yesterday and won’t remember tomorrow.
Impulse buying is the most seductive head. It feels harmless, even rewarding in the moment. But unchecked, it wrecks budgets. Small, frequent splurges compound into large leaks over time.
What to do: Follow a 24-hour pause rule. If you still want the item a day later, consider buying it. Most often, the urge will vanish as quickly as it came.
2. Lifestyle inflation
A salary hike arrives, and suddenly the old car feels too small, the house too cramped and the phone too outdated. Lifestyle inflation—the silent creep of spending as income rises—keeps you stuck in a cycle of “earning more but saving less.”
What to do: Draw a line between wants and needs. Every time your income rises, increase your savings rate before you upgrade your lifestyle. Let luxuries grow slower than your investments.
3. Credit cards
Credit cards are not evil. Misusing them is. Swiping without tracking, rolling over balances and ignoring due dates create a spiral where interest costs (often 30-40 per cent annually) outstrip any investment returns.
What to do: Treat credit cards as a convenience tool, not free money. Pay in full, on time, every month. If you can’t, lock the card away until you regain control.
4. No emergency fund
Life rarely announces crises in advance. Job loss, medical emergencies, or sudden expenses can arrive uninvited. Without an emergency fund, you’ll either liquidate investments at the wrong time or slide into debt.
What to do: Keep at least six months of expenses parked in a liquid fund or savings account. It’s your financial fire extinguisher, boring until the day it saves you.
5. Skipping insurance
“I’m young and healthy, why waste money on insurance?” I’ve heard this line from countless friends. And yet, one unexpected hospital bill is enough to wipe out years of savings.
What to do: Health and term insurance aren’t optional; they’re foundational. Insure your risks. A term plan and a health policy are shields every household needs.
6. Someday SIPs
You know SIPs (systematic investment plans) are powerful. You’ve read how they compound quietly over the years. Yet, you keep telling yourself, “I’ll start once I get that bonus” or “once the market cools down.” That someday never comes.
What to do: Compounding rewards time, not timing. Start small, even Rs 1,000 or Rs 2,000 a month is enough. Build the habit first, scale up later.
7. Market timing
“Let’s wait for the market to dip before investing.” Sounds wise, but in practice, most people sit on the sidelines as markets climb. Others jump in when prices are overheated and exit in panic when they fall.
What to do: Accept that you can’t predict markets consistently. Build wealth through discipline, SIPs over lucky guesses.
8. Herd following
A friend brags about a multibagger, a colleague shares a hot tip, and suddenly you feel left out. You invest not because you researched, but because “everyone else is doing it.”
What to do: Herd investing often ends in regret. By the time news reaches you, the best gains are gone. Do your own diligence. If you don’t understand the business, don’t buy the stock.
9. Over-diversification
Many investors believe “more funds, less risk.” The result? Portfolios with 12 or 15 mutual funds that look like a confused buffet. Too much diversification ends up mirroring the index, diluting performance, increasing costs, and without reducing risk.
What to do: Trim your portfolio. Three to four equity funds and two debt funds are enough for most investors. Quality beats quantity.
10. No goals
Perhaps the most destructive of them all: investing without purpose. When you don’t tie money to goals—like a home down payment, children’s education, or retirement—it drifts aimlessly. You chase returns, panic in crashes and redeem too early.
What to do: Anchor every investment to a goal and time horizon. Once you see investments as a means to an end, discipline becomes easier.
The final battle
When effigies of Ravana burn this Dussehra, remember: the real battle is closer to home. Every financial decision is a choice between discipline and temptation, between long-term peace and short-term thrill.
The 10 money habits listed above are not invincible. Each can be conquered with small, deliberate steps. No divine weapons—just awareness, patience and consistency.
So this year, as fireworks light the night sky, take a quiet pledge of your own. Defeat the bad money habits that hold you back. Build the good ones that push you forward. Because true financial freedom isn’t about how much you earn, it’s about how wisely you choose.
And if you’re looking for trustworthy insights to guide those choices, turn to Value Research Online. From mutual fund recommendations and portfolio tools to deep-dive articles like this one, it’s your one-stop resource to make smarter financial decisions without the noise.
This article was originally published on October 01, 2025.
Ask Value Research 

 New episodes every Friday







 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


