




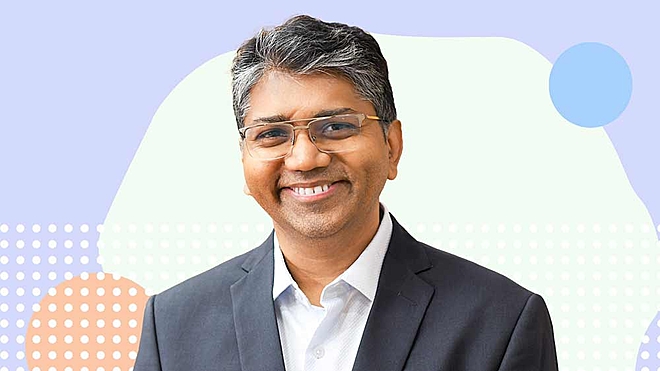

Before he became a fund manager, Chirag Dagli was just another college student hooked on the buzz of the stock market. It was the Harshad Mehta era, when headlines moved markets and fortunes were made overnight. For a middle-class kid with ambition, the lure was irresistible.
Decades later, Dagli, now a Fund Manager at DSP Mutual Fund, hasn't lost that fascination. What's changed is his approach: rigorous, layered, and rooted in timeless principles. Currently, he manages two funds - the DSP Healthcare Fund and DSP Multicap Fund - with a collective AUM (assets under management) of around Rs 5,000 crore. Of these, the healthcare fund holds a four-star rating from Value Research.
In this exclusive interview, Dagli unpacks his stock selection playbook, explains why he avoids style boxes like 'value' or 'growth' and shares the reasons behind the multi-cap fund's preference for mid-cap stocks. Below is the edited excerpt of our conversation.
Can you share what initially drew you to the world of equity investing?
I'm a chartered accountant by qualification. However, my entrepreneurial journey had already started with the stock market during college. This was back during the Harshad Mehta days when a lot of money was being made. As a middle-class guy, I was naturally attracted to it. So, I've always been interested in the markets. Fortunately, I became a chartered accountant early on and was fortunate enough to start working in the stock market. Since then, there has been no looking back.
What core principles guide your investment decisions? How do you select stocks?
At the heart of my stock selection process is the underlying principle that you want to buy stocks trading at a price lower than their intrinsic value. You can slice, dice and look at a stock's intrinsic value in many ways, depending on current earnings, replacement cost, etc. However, the core principle is that you want to buy stocks that are lower than their intrinsic value.
Once you've done this analysis, you look at a particular sector and identify a stock that looks like the best company within that sector based on valuation, management quality, growth potential, execution and forensics. Once you compare all these and conclude that this is the stock to own, you will do the next layer of analysis on the portfolio construction side. So, the first layer is equity research in its purest sense; the second layer is portfolio construction. In portfolio construction, you essentially put stocks into four buckets: growth stocks, value stocks, compounders and turnaround sectors.
Once you put a stock in a specific bucket, you compare it with various other stocks in that bucket but across multiple industries. That allows you to do two things. One is not to have a large style skew. For instance, I'm not a value or a growth investor. I think these are all labels we call ourselves. At heart, everybody wants to buy stocks that are mispriced in some sense.
Now, if you look at these four buckets, growth stocks are essentially high-growth stocks with good and quality management, ticking all the boxes on the forensic side. These are the ones that you're comparing from the perspective of potential opportunity. So, you compare two growth stocks, look at the possible opportunity to grow, how fast they can grow and what the price indicates regarding growth potential. That's on the growth bucket.
Similarly, on the value side, these companies are not growing as fast as the GDP or growing slower than the GDP, likely with very soft multiples. Again, you look at where the market narrative is wrong here. How does the market think about these stocks differently? If there's a stock with a P/E of five, six or 10, what is the market telling you about the long-term terminal value of these businesses, and is it wrong or right about that? That's the second bucket, which is the 'value' bucket.
The third bucket is the 'compounders', companies growing in line with India's GDP. These are well-run, large and stable companies. The usual big names come to mind. Their stories essentially are the India story: If India does well over the next 10 years, they'll also do equally well, if not better.
Then there's a fourth bucket, essentially a turnaround kind of bucket. Since we don't want a huge style skew across these four buckets, we have a very reasonable, optimal mix around this. But that does not mean the portfolio will be 25 per cent in each bucket. Depending on market conditions, it is intuitively right to assume that compounders will have a much larger weight, turnarounds will have a much smaller weight and growth and value will likely be roughly equal in weight by and large. That's how portfolio construction will likely happen because turnarounds are also high-risk, and that risk needs to be adequately priced as far as the stock price is concerned.
One thing I'm very clear about is that reasonable capital efficiency is a must across the entire portfolio. The turnaround bucket is the only bucket where a lower-than-mid-teens return on capital is tolerated. This is because these companies are going through a unique situation. They're going through a down cycle or a big investment phase, so their reported capital efficiency is poor. In all the other three buckets, reasonable capital efficiency, as I said, is something we look for; mid to slightly higher teens are non-negotiable capital efficiency.
With the recent pullback in Indian equities, do you think the worst is already behind us, or are we in for more volatility?
No. I think, generally, it's difficult to make very forward-looking comments. But one obvious thing is that volatility is bound to rise. We are in an uncertain world. Much of this stems from global volatility, not as much from India. In that sense, we are in a sweet spot. But naturally, the world is far more globalised, and in that sense, we don't operate out of an island. So, global uncertainty and volatility in the markets are here to stay. It can't be said that volatility is behind us. The form and shape, the contours, will change. But things remain very dynamic, and taking one day at a time is how I would say.
Since the DSP Multicap Fund is relatively new, can you share its strategy and how it aligns with your broader investment principles?
Two or three things are a little different. One is, by its very definition, multi cap, which has a much higher weight towards small and mid caps than the flexi-cap fund.
Something unique with DSP's Multi Cap Fund is that we have a lot of stocks below the Nifty 500. The country has 500 top names that trade in the market; we have about 13 to 14 per cent of the portfolio below that.
The second thing we are trying to do is focus more on the small- and mid-cap categories within the multi-cap fund. India is growing very well and changing from the bottom up. That is where we see a lot of opportunity.
The third unique thing about DSP is our ability to invest in international names, essentially US-listed names. Today, we don't have any in the multi-cap fund, but we can do it at some point where we don't find opportunities in India.
We are currently investing in international stocks in our healthcare fund. About 14 per cent of the DSP Healthcare Fund invests in US-listed names. So, we can achieve something similar in the multi-cap fund as well, but at an opportune time, depending on the stocks and whether there are opportunities not present in India but in the US.
If I look at the portfolio of the DSP Multicap Fund, 47 per cent of the portfolio is in mid-cap stocks. What gives you confidence in mid caps despite their elevated valuations?
Small and mid caps put together will be slightly more than 65 per cent of the multi-cap portfolio's composition. I'm clubbing the two because these category classifications change every six months. So, given the size of the fund and the depth of coverage that we have, DSP has a history of running the micro-cap fund. We have a large small-cap fund as well. Given that vintage and legacy, we understand some of these businesses very well and can benefit from the insights into some of them.
By and large, we've always said that for the better part of the last two years, we've been saying small and mid caps are expensive on an absolute basis, but that's when you look at the index, versus the large caps.
I think small- and mid-cap investing is a lot about bottom-up stock selection. I don't need to own 500 names. I need to own 30-40 good-quality names in the small- and mid-cap space. I see enough opportunity and stocks in the multi-cap fund, especially at the size of our AUM. We did the NFO last year, so we're about 12 months or more. I still see opportunities we can buy in the small- and mid-cap space, although the overall index may seem expensive versus the large caps.
Also read: CIO Sanjay Chawla spots signs of recovery in mid-cap stocks
Ask Value Research 

 New episodes every Friday



 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


