




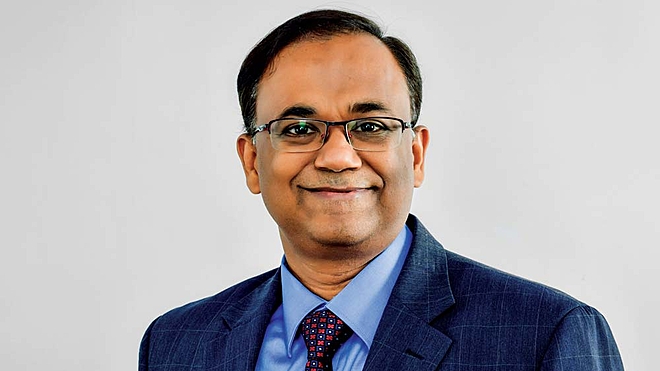
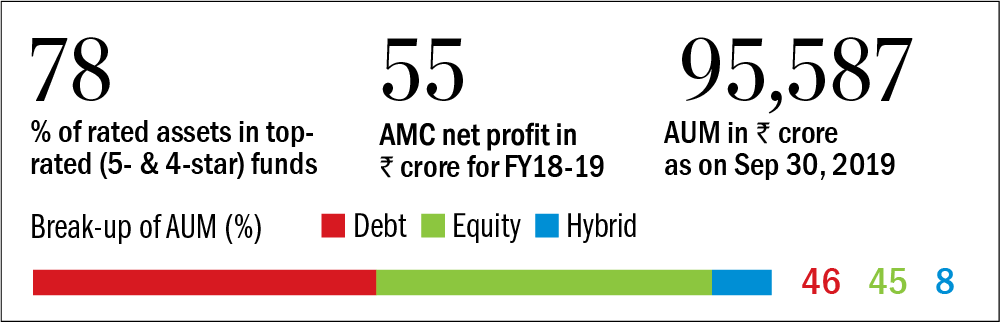
These are the best of times and these are the worst of times for the industry. We are at an all time high in terms of penetration and AUMs, but we are facing spotlight like never before thanks to the effect of credit events on debt funds and weak performance in equities relative to the benchmarks.
Through this period at Axis AMC, it has been our endeavour to ensure that we don't lose sight of the basics - that we offer the right products to our investors and manage them responsibly using a sustainable approach.
I think we have executed this quite well and as a result we continue to grow and get increasing support from our partners and investors. We are hungry and keen to achieve a leadership position in the industry over the short to medium term.
Impact of new expense slabs
I think the industry has been able to absorb the TER impact. There is not much point in dwelling over changes in regulations as these are the new realities that we have to work with. The way we look at it is that lower expenses make the product even more attractive for our investors and therefore over the long term any short-term impact of the move should get negated by higher flows.
Risk control in debt funds
Our AMC has submitted its proposal to SEBI for side-pocketing and a go ahead for the same is awaited for initiating the process of segregation of portfolio in the future for certain schemes of Axis Mutual Fund. It is an important safeguard for investors in open-end debt schemes in case there is a material credit event.
With respect to our investment process, the focus has always been on having multi-layered risk management as an integral part of the process. At the base level, we do detailed credit diligence for each exposure that we take. We complement that by fund-level risk limits that work on limiting exposure to each credit in line with prudent risk limits relevant to that strategy. Finally, we ensure that we are conservative in terms of the products that we offer and avoid creating aggressive products that investors may not understand or which may not be sustainable.
Key challenge
Our funds have done extremely well across the cycle but our message of sustainable performance and prudent risk management is often lost in the euphoria when markets are going through upswings. We have to ensure that we take our message out as broadly as possible - to both distributors and investors. We have to ensure that we can make investors relate to what we are trying to do and to appreciate the potential value addition to their portfolio from our long-term investment philosophy.
This article was originally published on December 12, 2019.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


