




As an AMC, our heritage is drawn from our parent, Sundaram Finance, which has imparted to us the core values on 'the way we conduct our business'. Adding to this are our home-grown strengths such as an extreme research-oriented investment-process focus, which has led to a superior performance track record in equities with small and mid caps, in portfolio management and a high-quality credit portfolio in fixed income.
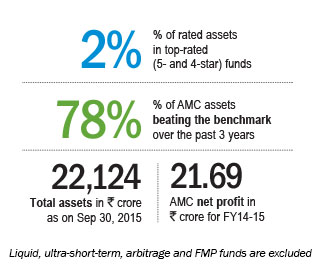 High on the list in the areas where we experience challenges would be our brand recall in the non-South markets as compared to the competitors who have the parentage of either a pan-India large bank or industrial house. Our approach to tackle this has been to build our brand presence through the distributor fraternity. Another area would be the need to be present across a range of product categories. We have consciously been building our fixed-income bouquet and will be adding arbitrage, passive management and alternatives in the coming year.
Challenges ahead
Our mid- and small-cap funds have been punching above their weight in terms of net inflows into the category. Our money-market and shorter duration funds have also been getting a fair share of inflows. The challenge is to translate this market share into other categories - large-cap, medium- and long-term fixed income, etc. - given that many of these funds have also been beating their benchmarks.
From an investment perspective, creating a larger alpha versus the benchmark in some of these funds is a key priority. Another key challenge would be the pace at which economy-related reforms progress vis-a-vis market expectations.
Competition
The real underlying issue is mutual fund penetration, which is still at single-digit levels. Reaching more customers is not something that needs more AMCs; leave alone acquisition of new customers, the existing AMCs are hardly equipped to meet the needs of even the existing base. What the industry needs is a massive expansion in distribution base. This would itself make for a perfectly competitive industry and drive diversity in product offerings.
Retail reach
We set ourselves a target last year itself - a 100-city plus 'brick-and-mortar' customer contact presence. We have made significant progress, with a current strength of 94. The rest of the goal will be achieved in the course of the current year. Apart from completing the rest, our key focus now is to increase the empanelment of new distributors, enhance the activity levels of current distributors, and increase the number of customer folios and SIP investors in these locations. Our efforts are beginning to bear fruit, evidenced from the statistic that 37 per cent of our IFA base, more than a fifth of our retail folios, almost 40 per cent of our SIPs by number and 30 per cent by value arise from locations beyond the top 15 cities.
This article was originally published on December 08, 2015.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


