




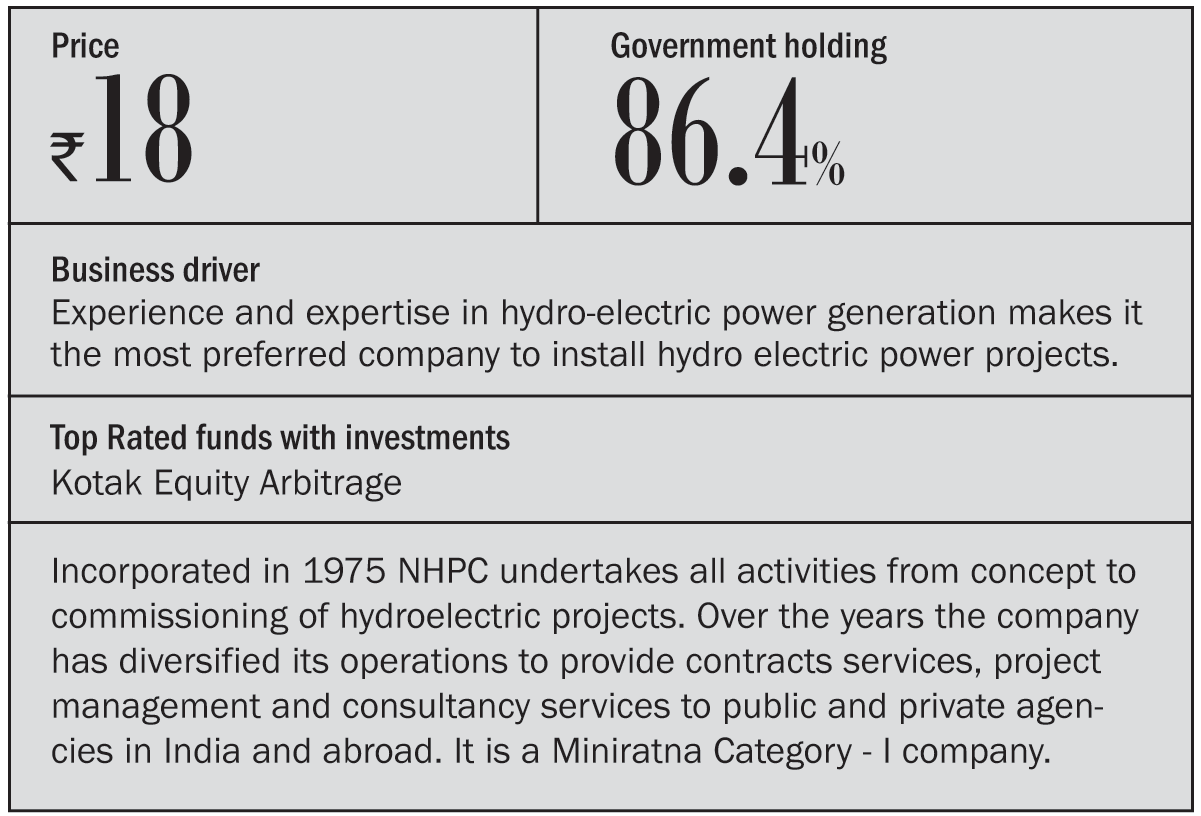
National Hydro Power Corporation (NHPC) is primarily engaged in hydro electric power generation with a current installed capacity of 5,747 MW, generated through 17 operating power stations. The company also provides contract services, project management and consultancy services to public and private agencies in India and abroad.
The company has 7 projects that are under construction with an aggregate power capacity of 4,500 MW. Over the years NHPC has also ventured into consultancy, geothermal, tidal and wind energy and recently it has indicated to move into thermal power generation as well.
Strengths
The opportunity to tap hydroelectric power is immense, with the potential capacity estimated at 98,242 MW. NHPC has projects in pipeline and some are being discovered.
NHPC has vast experience and expertise in the hydroelectric power generation. It is for this reason that even those projects that were taken away from NHPC and given to private players are now being executed by the company through JVs with these private entities. Jindal Power, Reliance Energy and KSK Energy Ventures, were awarded projects which was earlier given to NHPC by the Arunachal Pradesh government.

All the three players are using NHPC to complete the projects which NHPC lost. Further, the Comptroller and Auditor General of India (CAG) made a statement that projects above 100MW need to be fair, transparent and competitive, which should insulate NHPC from facing such issues in the future, where state governments award projects to private players.
Although hydro power has a high gestation period, they operate at very low recurring cost once the projects commence. It is for this reason that the operating and net profit margins are high for NHPC in it: 88 per cent and 45 per cent net margin, respectively, over the past five years.
Concerns
The major concern is the delay in the project execution and completion and hence escalating the initial costs without generating any revenues. Capital work in progress was close to 52 per cent of the tangible fixed assets and around 20 per cent of the book value in FY13 which is very high. The reasons are delay in clearance, opposition from environmental groups and government scrapping projects due to feasibility and environmental issues. NHPC is facing delays in projects with a capacity of 3,808.5 MW.
The high capacity 2,000 MW project in Subansiri Lower Assam and Arunanchal was expected to be operational by FY18 has suffered due to local agitations since December 2011. NHPC has already invested around ₹6,000 crore in the project.
Further, a PTI report stated that five projects with a aggregate capacity of 3,810 MW were behind schedule. Three projects which were scheduled in 11th Plan will now be completed in the 12th Plan. The Forest Advisory Committee (FAC) has also denied the clearance to its flagship 3,000MW Dibang project in Arunachal Pradesh.
The entire hydropower sector is suffering due to these issues and according to a CAG report, hydropower capacity addition, which was targeted at 11,813 MW in the 11th Plan, will not be met even with the revised target of 6,794 MW.

Valuation
The stock is currently trading at almost half its price since its listing in 2009 and price to earnings of 9.6. The price to book of 0.76 is 36 per cent lower to its average of 1.19 and is lowest in the sector due to the hovering concerns. Given its operational efficiencies once the projects comes to track-difficult in near future-the company can witness strong growth. Invest if you have high risk appetite.
This article was originally published on March 12, 2014.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


