




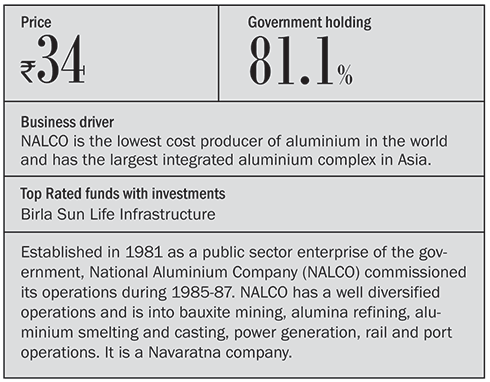
NALCO is not just about aluminium and has business interests in chemicals and electricity. The chemicals segment comprises calcined alumina and alumina hydrate, the aluminum division involves manufacturing of aluminum ingots, wire rods, billet, strips and rolled products; while the bauxite produced for captive consumption during production of alumina is considered under the chemicals segment.
Strengths
Nalco is fully integrated and its operations range from extraction of key raw material bauxite to captive power and the company has been able to keep its cost low. It is for this reason alone that Nalco has an edge over other players.

At times when most of the metal producers are dependent on coal import, Nalco has the ability to meet its requirement for its captive power plants in Angul, Odisha, from owned mines and Coal India, thus saving the yet rising power and fuel cost. To further improve the cost structure the company is expected to commence coal mining from Utkal E coal block by the end of the current financial year. Nalco also boasts of its captive bauxite mines at Panchpatmalli, Odisha, because the bauxite from these mines consumes low energy in the crushing and digestion process during conversion to alumina.
International markets have started to show signs of recovery since FY12. For instance, the company's exports have witnessed strong revenue growth of 33 per cent and 24 per cent in FY13 and FY12 respectively, in contrast to the domestic revenue where it fell by 13 per cent in FY13.
Although Nalco does not have a very convincing growth driver in the near future, it is expected that the company will witness a push in its topline once the overall economy picks up, the timing of which at the moment is not certain, but is more likley to witness a turn in direction.
With increasing global demand, the company has planned expansion of its capacity for aluminum smelting from 3,45,000 MT to 4,60,000 MT, for alumina refining from 1.57 million MT to 2.1 million MT, for captive power from 960 MW to 1,200 MW and bauxite mines from 4.8 million MT to 6.3 million MT. The fact that the company has its own reserves and cash to expand its scale without depending on the loan amid high interest rates, is a big plus.
Concerns
Nalco has had a constant fall in its net margins since 2007, dropping to 8per cent from 36 per cent in FY13. The main culprit for this fall is the power and fuel costs which form a major part of the Nalco's expenditure. Power and fuel account for more than 30 per cent of the company's revenue in FY-13 from 13 per cent in FY-07. However, this is a matter of concern for all players in this segment.
As Nalco products are commodity-based, it does not have control over pricing and depends on the demand to arrive at pricing. This limits the scope to improve the margins, as any improvement can be achieved only on the cost side. Although cost have risen sharply over the past few years, Nalco has maintained its competitiveness on comparative basis.
An area of worry remains to be the escalating cost of power and fuel, which is vital for the company's operations. However, the company has started putting in place plans to tackle this with more captive power resources but delay in execution can further eat away the margins.

Valuation
Nalco is a debt free with ₹5,337 crore cash, which is 56 per cent of its market cap. Bringing together these variables the enterprise value coverts to ₹4,200 crore as against its market capitalisation of ₹9,613 crore and EV/EBIDTA of just 3.9 makes it heavily undervalued. At current price of ₹38 the stock is trading at price to earnings multiple of 13.6 and price to book of 0.78 which 60 per cent discount to its 10 years of average. Invest with an indefinite time horizon.
This article was originally published on March 07, 2014.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


