




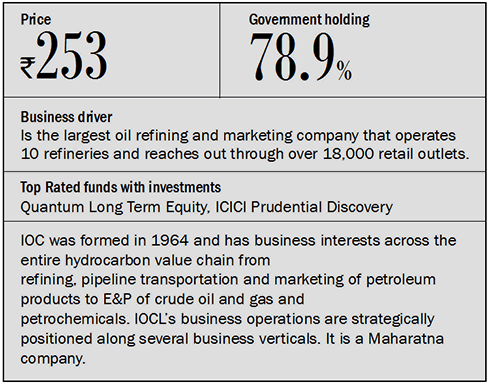
Indian Oil Corporation (IOC) is the largest company in India by revenue and the largest refining and marketing company in India. It operates 8 refineries with a capacity of 65.7 MMTPA and a pipeline of more than 10,000 kilometres. IOC sells a diverse product basket all belonging to the crude basket that includes petrol, diesel, LPG, auto LPG, aviation turbine fuel, kerosene, bitumen, naphtha, lubricants, and paraffin among others. In July of 2013, IOC raised $500 million by selling 10-year dollar-denominated bonds.
Strengths
With 49 per cent market share, IOC is the market leader in the petroleum products market. It has 31 per cent share in refining capacity and 67 per cent of downstream sector pipelines capacity in India. IOC and its subsidiaries run 10 out of the country's 22 refineries that have a combined refining capacity of 65.7 million metric tonnes per year.

IOC operates the country's largest and the widest network of fuel stations which totals more than 20,000 outlets. It supplies cooking gas under the brand name Indane to over 66.8 million households through a network of 5,934 distributors. The shear size and scale gives IOC a very distinct visible advantage.
IOC's refining margins for the quarter ended September 2013 stood at $6.6 per barrel compared to $5.2 per barrel in the previous year and much higher than the $1.7 per barrel it reported in the first quarter of the current financial. Much of this gain is estimated to come from inventory gain of $4-5 per barrel of the reported GRM according to a report by Motilal Oswal. The company reported a premium of $1.2 per barrel to the benchmark Singapore GRM.
The next phase of growth for IOC is to come from the expansion of its Panipat refinery from 12 to 15mmtpa. The ₹14,400 crore naphtha cracker commissioned at Panipat and the ₹29,000 crore integrated refinery that will have a capacity of 15 MMTPA.
Further, the strategy to deploy multiple brands to market its products has advantages. For instance, it sells under the IndaneGas for its domestic and industrial gas. It uses AutoGas for its automotive natural gas, Xtra Premium for its automotive premium petrol, Xtra Mile for its automotive premium diesel and Servo for its lubricants and greases.
IOC incurred a net under recovery of ₹410 crore in the September 2013 quarter after upstream companies compensated it ₹8,630 crore while the government paid ₹9,240 crore. The government's decision to raise diesel prices by 45 paisa every month and market pricing for bulk buyers is expected to help downstream companies in a big way. Under-recoveries are expected to go down by as much as 40 per cent in FY15 as compared to F13 levels.
Concerns
The delay in the government adopting the Kirit Parikh report will hurt IOC. Like other OMCs, the fortunes of the sector players are not as much a function of fundamentals but rather of political compulsions. With the elections less than six months away now, any radical decision that will benefit the oil companies at the expense of the public can be absolutely ruled out. That means any policy action for the sector is now at least six months away.

Valuation
IOC trades at three times its earnings, which is a significant discount to its 10-year median valuation of 8.4. There is no long term fundamental case to buy IOC till the unceasing government interference stops. The immediate likelihood of that scenario looks dim. The stock has already lost 25 per cent in calendar year 2013. There are no indications that the going will get easier for OMCs till the much needed new policy for the sector is spelt. Stay away from IOC till then.
This article was originally published on March 05, 2014.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


