


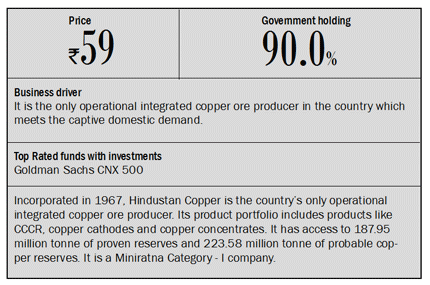
Hindustan Copper is the country's only operational integrated copper ore producer. Its product portfolio includes products like CCCR, copper cathodes and copper concentrates. The by-products of the company comprise copper sulphate, sulphuric acid, reverts and anode slime. The company has four manufacturing facilities across Jharkhand, Rajasthan, MP and Maharashtra.
Copper is used most in electricals and about a third of the entire copper consumption in India goes into electricals. Other major consumers include transport, building and construction, engineering and consumer durables.
Strengths
Copper ore production in India during 2012-13 stood at 3.6 million metric tonne, which is sufficient to meet only about four per cent of the country's total demand. Hindustan Copper has a ready market for copper, which it meets on its own, while the balance is imported.

The company sells copper in three forms: continuous cast rods used in copper wires, cathode used in the manufacture of alloys, foils, etc, and copper concentrate used for smelting and in the production of refined copper. The continuous cast rods took the lion's share of Hindustan Copper's sales at 20,729 tonne (FY13), followed by the sale of cathode sales volume of 3,783 tonne and lastly by concentrate copper with volumes of 1,330 tonne.
Hindustan Copper has seen margins move away from red between FY97-03. Between FY04-10 margins averaged at 14 per cent while in the last three years, they averaged at 36 per cent. The most recent quarter ended September 2013 saw margins at 37.8 per cent. Likewise, the cash reserves have also improved and the company is now debt free. It has managed its affairs with negligible to zero debt for the past eight years now and the net cash added to `527 crore as of FY13.
The company is working towards increasing its mining capacity to 12.41 MTPA by 2017-18 from the current 3.66 MTPA (FY13). The increase is mostly expected to come by increasing the capacity of its existing mines and re-opening of closed mines. Also planned are brown field and green field exploration at its Banwas and Chapri-Sideshwar (Jharkhand) MINES which should collectively add 2.1 MTPA.
Concerns
Being a pure commodity play, the fortunes of the company are dependent on copper prices on the London Metal Exchange. Then there are requisite permissions like environmental clearances, mining leases and other Governmental approvals which given the current political environment could take more time than accounted for.
Copper prices on the London metal Exchange have largely been flat through 2013 and was down 8 per cent in calendar 2013. However, the demand-supply position currently in favour of miners like Hindustan Copper is likely to remain so.
The company has filed applications for mining lease (ML), Prospecting license (PL) and Reconnaissance permit (RP) in its search for new mines. Of special interest are Sikar in Rajasthan, the districts of Mohindergarh, Jhajjar and Bhiwani in Haryana, Balaghat in Madhya Pradesh and East Singhbhum in Jharkhand. Establishing new mines could cost the company over `3,400 crore, which could impact the finances.

Valuation
The company's business and margin profiles are good, but its inextricable relationship with the Government has both advantages and disadvantages. Hindustan Copper has very limited competition-no player can just mine copper in India without Government approval. The only serious competitor to Hindustan Copper is Sesa Sterlite. Even though it has already lost half its market value over 2013, on a half-yearly earnings per share annualised basis, Hindustan Copper still trades at an expensive 38 times earnings. Stay away till valuations cool down.
This article was originally published on March 03, 2014.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


