


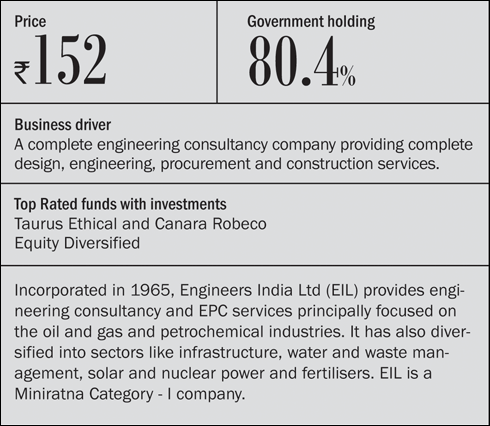
Engineers India (EIL) is one of the few players that has a government mandate to build infrastructure for the domestic oil and gas sector with highest quality and safety standards. EIL has two main verticals-the Consultancy and Engineering vertical accounting 61.8 per cent of its revenues (as of first half FY14) and the Lump sum turnkey projects (LSTK) vertical that accounts for 38.2 per cent. With the slowdown in the economy; the lump sum turnkey projects vertical has witnessed a dip, resulting the share of consultancy in the company's Ebit to go up from 80 per cent (H1FY13) to 90 per cent (H1FY14).
Strengths
EIL is the government's engineer as it receives majority of its revenues from the government. It specialises in building infrastructure for the oil and gas sector which accounts for about 95 per cent of the order book. Within this, the refining and petroleum sector constitutes over 70 per cent of the order book.
A big advantage that EIL enjoys is that over 90 per cent of the contracts it gets are either negotiated or nominated by the Ministry of Petroleum and Natural Gas. This ensures that EIL does not have to enter into competitive bidding for a significant portion of its revenues, which in turn is the reasons for the high margins that EIL has enjoyed historically.
The company has a strong order book with 55 per cent constituted by the consultancy vertical. Moreover, the company is the lowest bidder in orders worth `3,000 crore which are likely to be awarded over the next two quarters. Strong cash balance is another plus with cash balance at the end of the first half adding to `2,500 crore up from `2,390 crore at the end of FY13.

Concerns
EIL's main source of revenue is building infrastructure for the hydrocarbon sector in India. This is also its Achilles' heel. The slowdown in the capex cycle in the government owned refining and petrochemical sector has hit the company hard. Revenues from the lump sum turnkey projects vertical saw a decline of 53 per cent in the first half of the current year. That on an order book that declined 52 per cent during the same period.
Like other infrastructure players, the slowdown has now come to bite EIL. Its order book declined 26 per cent over the previous year. While lump sum order book was down 31 per cent in the September 2013 quarter, the consultancy vertical saw order book decline 31 per cent in the same period. Order inflows are down 22 per cent disproving any notion of a recovery in the sector.
Another blow comes from falling margins, which have traditionally been EIL's strong point. Consultancy and Engineering vertical saw margins decline from 42.6 per cent to 37.6 per cent during the first half of the current year while margins in the lump sum turnkey projects vertical saw a decline from 9.5 per cent to 6.8 per cent. The main cause of this decline was falling revenue.
A cause of worry is also the ROCE, which averaged 42.9 per cent in the past three years. Although this is the highest among its peers, it could go down this financial year as the slowdown starts hitting the bottomline.

Valuation
EIL trades at nine times its earnings. The immediate outlook for the company looks bleak if the recent results are anything to go by. The company might face more headwinds ahead if the investment cycle doesn't turn around quick. Yes EIL is still the preferred engineer for the government and it has sufficient cash balance to tide over the tough times. The high cash to market cap ratio makes it an attractive value buy. EIL is as high quality engineering company as you can get but any investment in this company will pay off only in the long run.
This article was originally published on February 24, 2014.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


