




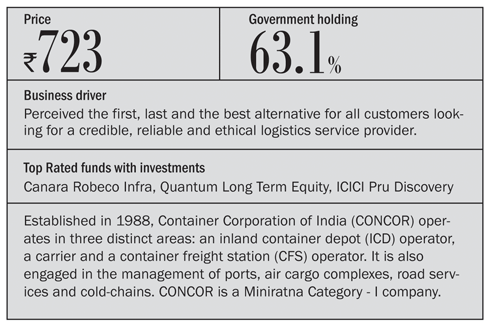
CONCOR serves as a multimodal logistic solutions, which operates under the Railways. It started its business by taking over seven Inland Container Depot (ICD) networks from Indian Railways and now handles container freight services through agreements.
The company serves the EXIM (Export Import) and domestic trades' logistics needs through its wide network of 8 regional offices. CONCOR also provides hub and spoke services that involve the linking of road or short lead rail shuttle services within defined catchment areas, to long lead-point --to-point train services.
Strength
The company handles 75 per cent of the total container cargo movement in India, carrying 31 million tonne in FY13. It helps to be the preferred choice for the large scale EXIM and domestic logistics because of its pan India presence and strategic command over Railways' routes.
With operations based on cash, the realisations are good, which is evident in the net profits, which matches the cash from operating activities in all its financial years. This aspect leaves the company from any worries over working capital requirements.
The company has negligible debt, is cash rich with `3,000 crore and has a healthy net worth. The financial strength helps CONCOR go ahead with its planned capital expenditure towards upcoming expansion and upgrade plans.
The company has focused on growing its business through tie ups with government and industrial bodies. It has entered into a JV with Punjab and Uttarakhand. Further, to broaden its reach and to cover other aspects of logistics the company has formed CONCOR Air to exploit the air cargo segment. Plans are on the anvil to undertake the design, development and operations of the air cargo terminal at Santa Cruz airport in Mumbai. Moreover, to provide single window facility, the company is setting up Multi Modal Logistics Parks (MMLPs).
As part of development, the company has started 7,200 high speed container flats (BLC wagons) which are capable of running at 100 kmph. CONCOR is gradually replacing the outdated wagons with its plans to further add to the fleet every year. Moreover, the company has purchased 7,200 flat wagons from the Indian Railways to strengthen its existing fleet. This strategy will reduce the transit time and will bring in growth in volume of non durable products. In the future, the major growth driver for the company will be the dedicated freight corridor (DFC) being developed between Mumbai and Delhi, which is expected to be operational in FY17.

Concerns
The economic slowdown shows no immediate signs of a turnaround. This has not only affected the EXIM logistic segment, witnessing a decline of 1 per cent in the port traffic in FY13, but also the domestic operations which went through very moderate growth. The other major looming threat is the introduction of the Private Freight Policy (PFT) introduced by the Ministry of Railways in FY11. The policy seeks to increase the participation of the private sector players and CONCOR faced ban on some of the terminals in this regard. Concern is also the rise in the haulage charges imposed by the Railways.

Valuations
CONCOR is one of the few PSUs which is trading at a price higher than its highs of 2007 and has given good long term returns, which almost matches the Sensex. The share price is trading at price to earnings multiple of 14.7, marginally lower than its 10-year median of 15.6. The current P/BV is at 40 per cent discount to the 10-year average of 3.35. Amid slowdown in the FMCG sector and overall EXIM operations, the company will witness a surge with these factors reversing. Consider it with a long term perspective.
This article was originally published on February 21, 2014.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


