


The shareholders of country's fifth-largest technology company HCL Tech are a happy lot. The stock is one of the best performing technology stocks this year with a gain of 83 per cent (ytd)! That much gain was not seen by even industry leader TCS. This story is about why it may not be too late to join the HCL Tech bandwagon and how the company is poised for an even better fiscal this year. With its momentum, HCL Tech may finally join the Big Boys Club of Indian IT.
Growth drivers
Billion dollar deals: Unlike the poster boys of Indian technology--Infosys and Wipro, HCL Tech has snagged deals totalling $4 billion in the last four quarters. An exceptional performance given that the June quarter is seen as a weak one for re-bids. Winning these deals gives the company a chance to cross-sell its other services to the freshly-acquired clients. The cumulative value of these deals adds a tremendous near term visibility for FY14.
Growth across verticals: HCL Tech reported broad-based growth across verticals. Financial Services grew 6.9 per cent (q-o-q), manufacturing by 5.4 per cent, Life sciences by 6.5 per cent and public services by 3.1 per cent.
Infrastructure services driving growth: The infrastructure management services (IMS) recorded a growth of 8.7 per cent over the immediately preceding quarter. IMS now brings in 33.1 per cent of the company's revenues and with an overall growth of 36 per cent for FY13, it is also one of the company's fastest growing verticals. IMS now brings in 33 per cent of its revenues and with an overall growth of 36 per cent for FY13, it is also one of the company's fastest growing verticals.
One of the primary reasons why IMS is growing robustly is the strong demand in the re-bid market estimated at around $160 billion. According to Ambit Research, HCL Tech's IMS could grow at 30.8 per cent annually between FY13-16.
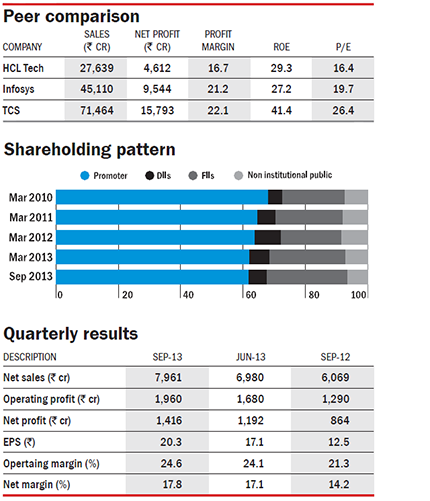
Strength of margin gains: Driven by the strong show of its IMS vertical, HCL Tech's Ebitda margins expanded to 26.3 per cent (q-o-q). Net margins for the company-- came in at 17.8 per cent for the September 2013 quarter, making it the eighth successive quarter of net margin expansion for HCL Tech. HCL Tech is expected to sustain margins at 22-23 per cent level for the rest of FY14.
Strong cash generation: HCL Tech generated free cash flows to the tune of Rs 3,974 crore in FY13. This is more than twice the free cash flow it generated in FY12. With its momentum still on a roll, the company is expected to generate still higher free cash flows in the current year--at around Rs 4,356 crore (According to Ambit Research).
Concerns
Core concerns: HCL Tech's main concern is flagging growth of its application services. This is the company's primary revenue contributor bringing in 45.7 per cent of the topline. Application services recorded a growth of only 0.9 per cent over the preceding quarter and has lagged behind with only 5.3 per cent growth in FY13. Weakness in the Enterprise Application segment, which saw a decline of 3.7 per cent in the last quarter, has particularly impacted this vertical. According to Ambit, core software services could record a growth of around 8.4 per cent annually between FY13-16.
Discretionary spending yet to pick up: According to the management of the company, it may still be early to flag-off a higher discretionary spending era. It is still seeing discretionary spending decisions being taken on a quarterly basis, rather than being longer term contracts.
High attrition: In spite of higher utilisations of 84.9 per cent, current attrition levels annualised at 16 per cent are still high relative to the industry.
High sensitivity to currency: HCL Tech has one of the highest sensitivity to currency movement. According to HSBC Research, a one per cent appreciation of the rupee vis-a-vis the dollar can dent margins by as much as 30-40 basis points.
Financials
HCL Tech has grown its revenues annually by 28 per cent in the last five years. Ebitda margins for FY13 stood at 22.7 per cent--higher than previous year margins of 19 per cent. Earnings per share jumped 66 per cent in FY13--much higher than the company's average annual earnings per share growth of 12 per cent in the preceding five years.
The company reported a revenue growth of 22 per cent in FY13. According to HSBC Research, revenue growth should stack at around 18.5 per cent this year. And as per Ambit Research, on the back of the momentum in the IMS vertical, HCL Tech could post a higher run rate of around 24 per cent--after taking into account the prevalent slowdown in core software services.
EPS estimates for HCL Tech for the current year vary between Rs 64.4 (Kotak estimates) to Rs 73 per share (Ambit Research). Here again the strong traction in IMS along with cut in tax rates from 25 per cent to 22 per cent is expected to help the company push per share growth numbers higher.
Outlook and valuation
The strong run in the IMS vertical has helped HCL Tech leap above its historical competitors. It is now growing faster than them. Four successive quarters of $1 billion plus deal wins signal that the company is poised for even stronger growth. Ebitda margins of the company are now higher than long time competitor Wipro and HCL Tech is now on its way to
narrow the margin gap with erstwhile industry leader Infosys.
Upside potential: Though the share price has run up considerably in the last one year, HCL Tech has not run out of steam yet.
According to HSBC Research, if HCL Tech is able to continue its large-deal-wins and churn out better-than-industry growth with improved margins in new deals, there stands a case of re-rating of the stock going ahead. Currently, HCL Tech has most of the above factors going in its favour. It trades at a TTM P/E of 16.4x. Buy the stock with a five-year investment horizon.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


