


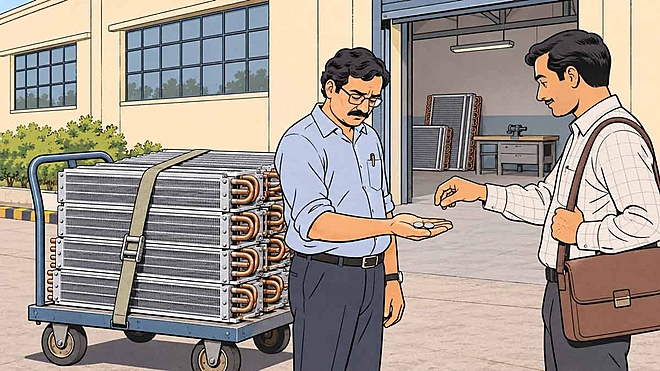
 Mukul Ojha/AI-Generated Image
Summary: Profit doubled. The share price went the other way. At KRN Heat Exchanger, a fast-growing supplier to India's air-conditioner makers, the market has changed what it will pay. The reason sits inside a single coil, and it decides what the stock must now deliver.
Our analyst diary, "Inside every air conditioner," published in Wealth Insight August 2026 edition called KRN Heat Exchanger a business worth knowing, but asked whether over 100 times earnings was a price worth paying. The share price is more than 40 per cent below its high of Rs 1,660. The P/E multiple has halved, from 121 to about 55, even as profit for H1 FY27 and Q2 FY27 rose 127 per cent and 100 per cent year-on-year.
Demand was already waiting
KRN makes the copper and aluminium coil inside an air conditioner, the part that moves heat. It builds each coil to the customer's design, and buyers such as Daikin and Blue Star switch suppliers reluctantly. For years the old plant ran above 90 per cent of capacity, with customers waiting for more.
The October 2024 IPO paid for a second plant at Neemrana, which opened in May 2025. The plant also brought new products and a surprise: data-centre cooling, where sales rose almost fivefold in the first half. Exports nearly tripled. That run explains how the P/E reached 100 and above.
| Rs crore | FY25 | FY26 | H1 FY27 |
|---|---|---|---|
| Sales | 430 | 600 | 571 |
| Net profit | 53 | 76 | 69 |
Margin: sales rose, profit did not
KRN does not earn money from selling coils. It earns a spread over the metal inside them. About 70 paise of every rupee of sales goes on raw material, mostly copper and aluminium.
|
|
Q1 FY27 | Q2 FY27 |
|---|---|---|
| Sales (Rs crore) | 252 | 319 |
| EBITDA (Rs crore) | 49.1 | 48.8 |
| EBITDA margin (%) | 19.4 | 15.3 |
| Raw material (% of sales) | 67.8 | 70.5 |
| Other expenses (% of sales) | 5.6 | 7.3 |
In Q2, sales rose 26.5 per cent over Q1. Operating profit (EBITDA) did not move. Had Q1's margin held on Q2's sales, operating profit would have been about Rs 62 crore instead of Rs 49 crore. Management named four causes.
Metal prices came first. KRN resets prices with customers once a quarter, so a sudden rise hits KRN first. And passing on metal cost lifts sales, not rupee profit. Say a coil sells for Rs 110 and earns Rs 10. Copper adds Rs 20, and KRN passes it on. The price becomes Rs 130, profit stays Rs 10, and the margin falls from 9.1 to 7.7 per cent.
Freight was second. Export orders cost more to ship, and freight took 1.8 points of margin. Daikin, a key customer, was third. Its price rose with metal, but KRN's rupee profit did not, as in the example. Business promotion was the fourth.
Working capital: growth that eats cash
Follow one coil. KRN pays suppliers in about two months. It holds stock for about three and a half months. After delivery, the customer takes about three months to pay. So each rupee of sales ties up KRN's money for about four and a half months. That tied-up money is working capital: stock and unpaid customer bills, less what KRN owes suppliers.
Fast growth stretches the chain. Dearer metal makes the same stock cost more. Management cites stock for new product lines and stock built before new rules limited copper-tube imports.
| Rs crore | Mar-26 | Sep-26 |
|---|---|---|
| Inventory | 273 | 380 |
| Receivables | 175 | 309 |
| Payables | 158 | 210 |
| Net cash (debt) | -141 | 32 |
The result: KRN reported profit, but its cash from operations used Rs 133 crore of cash in the half year, after Rs 114 crore in FY26. Profit is an accounting number. Cash pays suppliers and lenders.
A share sale to institutions (QIP) in June covered the gap. It raised Rs 350 crore, and about half is spent.
Management says it began working on this only about two months ago. It promises control by the end of the year, through better stock tracking, export factoring (selling bills to a bank for cash now) and buyer credit on imports. These change who funds the chain. They do not shorten it.
The more KRN sells, the more cash it needs first. Against sales, the chain is slightly shorter than March's 4.8 months, because stock has eased. But KRN now pays suppliers faster, and customers pay no faster.
What today's price needs KRN to deliver
The outlook has support. Management expects Neemrana to run at 80 per cent of capacity next year, against 50 this year. Exports earn 4 to 5 points more margin before freight, and government incentives are due from next year. It expects the Q3 margin to match Q2's and Q4 to be one to two points better.
The risks are real. Data centres gave over a third of Q2 sales, yet customers firm up orders for only one to two months, and KRN does not report a conventional order book number, because its orders are rolling. The United States is the largest export market, and management says tariffs or war could slow exports.
Now let’s see what the current price is asking for. Say you want 15 per cent return a year for the next five years. Here’s the different scenarios of profit growth needed in order to get that return:
|
|
Yearly profit growth needed (%) |
|---|---|
| Year 5, P/E holds at 55 | 15 |
| Year 5, P/E falls to 40 | 23 |
| Year 5, P/E falls to 30 | 30 |
KRN's profit grew 45 per cent in FY26, and the last 12 months are 50 per cent above FY26. That is faster than any row needs. But the speed came from filling a plant with queued orders, with a falling margin and negative cash flow. Such doubts push the P/E down, and a lower P/E needs faster profit growth.
Watch the Q3 margin, and inventory and operating cash flow in the March 2027 accounts. If both improve, the fall will look like a reset and a P/E near 55 can hold. If not, the lower rows become more likely.
Also read: Cheaper, but can they grow fast enough?
Ask Value Research 

 New episodes every Friday






 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


