




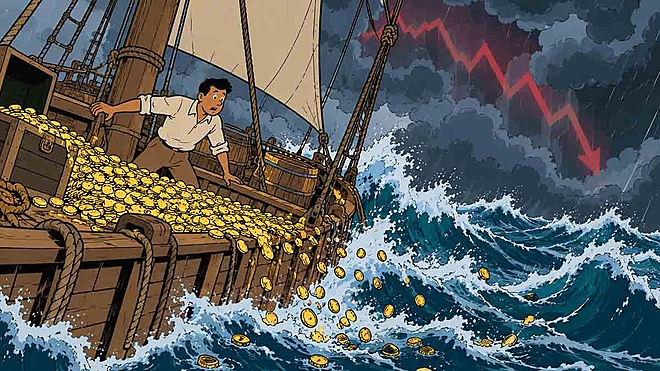
 Anand Kumar/AI-Generated Image

Summary: After two falling months, many investors see red against good funds and want out. But a fund that falls 18% while the index falls 24% has done well; the loss reflects timing. Judge a fund against its peers over a year or more, and worry only if it stays near the bottom for over a year.
Think of an investor who puts a large sum of money into a good equity fund a few months before a market peak. It's a well-managed fund, and in the fall that follows, it loses 18% while the index drops 24%. On any sensible basis, the fund has done well: the market has fallen sharply, but this fund manager has managed to fall a lot less. When the market turns, this head start will matter. The fund needs to rise about 22% to get back to where it started; the index needs about 32%.
But our investor does not see any of the good news. On his screen, there’s a big red number in front of this fund. The fact that the fund beat the index feels like some meaningless statistic.
Two different yardsticks
The difficulty is obvious: two different things are being compared. Judged against its benchmark, especially during a fall, any analyst, including Value Research, would say that this fund did well. The investor’s yardstick, though, is not benchmark-relative returns but his own absolute returns. That depends on the date he invested, whether it was a lump-sum investment or SIP, and simply where he entered the market cycle. In my experience, his own loss drives the decision to sell, but he blames the fund to justify it. This lets the investor ignore the responsibility he should take and shifts it to the fund manager.
Something similar happens when a fund that was a leader a couple of years ago now becomes ordinary. Suppose a fund gave 8% last year, but its five-year annualised returns are 18%. This kind of variation is routine in equity funds, whose track record is built from uneven years: some great, some good, some bad, and a few ugly. An investor who has stayed around for a few years sees one dull year among many good ones. The one who arrives after the boom feels tricked into buying a fund that used to be good but has now suddenly turned bad. It's the same fund, but the two investors' experiences are the exact opposite.
When psychology wrecks the arithmetic
The reason all this matters, and why I’m explaining it in somewhat tedious detail, is that the psychology here can wreck the arithmetic. A red number on your portfolio tracker is just a paper loss until you talk yourself into selling, at which point it becomes real. Except for the occasional brief bonanza, equity investing rewards years of patience and consistency, along with the quality of the fund you choose. This is even more true of SIPs, where stop-start investing can seriously damage your returns.
When to start worrying
But of course, there are funds that do genuinely decline. What I have said above shouldn't be taken to mean every fund should be held indefinitely regardless of performance, and the test for when to start worrying is, I admit, not that easy.
The first thing to watch is how a fund does against peers in the same category, which Value Research Online makes simple. Look over a time window of a year or more, because shorter periods have all kinds of random variation. Funds that perform exceptionally for a time can slip to the middle of the performance tables, which is natural and common. But when a fund goes near the bottom and stays there for more than a year, it is a different situation and needs a closer look. Another useful test is the five- and seven-year returns, which put a fund’s recent problems in a longer context and show you whether it still deserves patience.
The same tests also protect you in the opposite situation: you could be invested in a fund that is going bad, but due to the timing of your investments, the number on the screen could still be green. So a good investor should apply these tests even to funds that are showing a profit. Of course, this is too much hard work to do manually, and could easily become a distraction. But with the tools Value Research Online and other portals offer, you can automate this and let it run in the background. The colour of the number on your screen tells you about your timing, not about your fund.
Also read: Is Your Fund Good? Here's How to Check
Ask Value Research 

 New episodes every Friday





 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


