


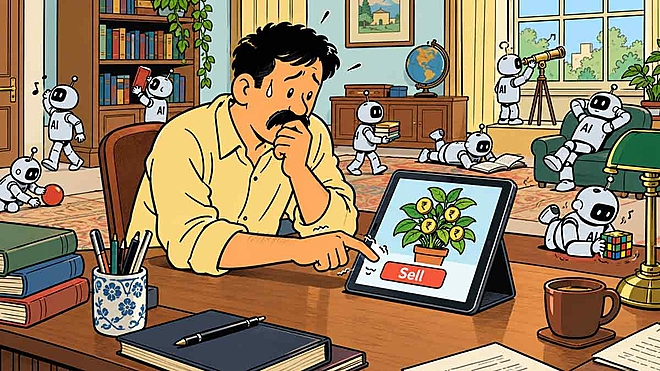
 Anand Kumar/AI-Generated Image

Summary: Investing apps now promise to make you a smarter investor, and some of what they do is genuinely useful. But an investment lives through three stages, and these tools are built almost entirely for two of them. The stage they skip is the one that decides what you actually earn.
There’s a spate of articles and social media posts in recent months about what is called the ‘AI Rollup’ business strategy. This is the thesis: buy an ordinary, stable but unglamourous business, put a layer of AI on its operations thereby reducing costs and increasing the margins, and then, as the profits rise, sell it off. Better still, acquire several similar businesses and roll them up into one with a single AI layer on top. ‘Acquire and implement AI’ has apparently become the plan for private equity and other usual suspects.
Some of the flaws in this concept are obvious. However, someone who has been in this kind of an activity had an excellent analysis. This person said that the opportunities for AI improving business operations is real because it can indeed, if implemented well, cut administrative effort and thereby increase margins. However, these improvements occur only when you just get into a business. The human aspect of sustaining a business over a period of time, the daily firefighting that every entrepreneur does, is something that the machine won’t do.
This actually applies quite well to retail investors’ personal investments too. There is now a spate of (supposedly) AI tools that are being thrown at investors which all promise to help them make better investments. So to understand what these AI tools can or cannot do for you, let’s see the lifecycle of an investment. There is the acquisition, when you choose your funds and invest in them. There is a long holding period, which is, hopefully, the growth phase, where returns grow and compound. And at some point you sell off the fund either because you need the money or the fund has declined. The thing to note is that the tools now being sold to investors are aimed almost entirely at the first and third of these stages.
For example, the software can analyse thousands of funds instantly and figure out that the three or four you are researching have almost identical portfolios. Or, it could go through the mass of marketing jargon from a fund company and rewrite it in human-understandable terms in whatever language you want. There are many such examples and they are genuinely useful.
However, the investor’s real challenge, like the business acquirer’s, lies in the middle stage. Choosing a good fund is the easy part because there are actually a lot of good funds and distinguishing the good from the bad is not black magic, nor is it guesswork. The difficult part comes when the markets fall sharply and you have to keep your SIPs running. It also comes when someone tells you to buy a fund that did slightly better than the one you are holding. Or, when there are wars and instability around the world and you start panicking about what will happen to your investments.
This is when the ‘AI tools will make you a great investor’ theory starts failing. When your finger hovers above the sell button in the app, there will not be an AI hand that will reach out and stop you from doing so. The real challenge of investing is in the human factor, your own emotions and attitude. And this is not just an opinion--study after study, including a recent one by my team at Value Research--shows that investors’ actual returns always lag behind those of the funds he invests in. Investors arrive after the good times and leave during the bad ones. This is the hole in the AI investor hype--the robots help you choose but that is not where the challenge is.
So do go ahead and use the tools, but remember that discipline and patience are the real tools, and only you can supply them.
Also read: The investor in the mirror
Ask Value Research 
 New episodes every Friday




 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


