


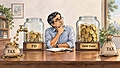
 Anand Kumar/AI-Generated Image

Summary: For a fortnight now, thousands of people have been doing genuinely excellent research. Excel sheets, fine print, settlement dates that push a transaction into the next financial year. All of it on a credit card rule change. Now ask the same people what their fund charges them every year.
For about a fortnight now, India's personal finance internet has been consumed by an argument that has nothing to do with markets, investments, or retirement. A large bank has changed the rules on a premium credit card. In future, the card will be only for customers who either spend a lot or keep a large 'relationship value' with the bank. Everyone else's card will be closed or downgraded. The response has been extraordinary, with threads running to hundreds of messages, screenshots of emails from relationship managers circulated as evidence, and talk of complaints to the RBI.
Some of that anger is justified. If a bank collects an annual fee and then, before the year is over, tells customers they don't deserve to be members, it has taken money for a promise it has since withdrawn.
But that is not what I want to write to you about.
What amazed me was the quality of the work going into it. If you read those threads, you will find a standard worthy of a good investment research team. People have built Excel sheets tracking their spending. They know which categories count, how settlements can push a transaction into the next financial year. They have read all the fine print and understood it. This is sustained, numerate analytical work on a question that matters intensely to them.
Now ask one of those people what the expense ratio on their mutual fund is, or how their portfolio is split between equity and fixed income. I have done such experiments, and I know the answer.
The reason is not foolishness or laziness. A credit card programme is built as a game that pays out immediately. You work out a clever manoeuvre, it pays within the month (actually, it makes you spend more), and you have won something. Investments offer no such excitement. Given the choice between a game that settles this week and one that settles in twenty years, people will choose the fast game, and the financial industry knows it.
It is worth doing the arithmetic on the slow game. On a portfolio of Rs 50 lakh, the gap between a fund charging 0.5 per cent a year and one charging 1.5 per cent is Rs 50,000 in the first year alone, and since that money never gets invested, it widens every year after. One fortnight of that effort, spent instead on your fund costs and your asset allocation, is worth more than every reward point you will ever earn.
The bank's own notice told holders that the card is not a product but a reflection of a relationship. That is exactly right, and it is exactly the problem. A relationship is something the other party can end.
So which of these things do you actually own? Points, tiers, lounge access and relationship status are not your property. A loyalty programme exists to help the other party make more money, and the terms and conditions are written to ensure it.
Your units in a mutual fund and your shares in a company are yours. You will never get an email saying you have been transitioned out for failing to maintain an adequate level of engagement. A scheme can be merged or wound up, but the money stays yours and comes back to you. The value will rise and fall, but that is the market moving, not a bank revoking.
I am not asking you to cut up your cards. I use mine almost every day. But the perks should be a casual byproduct of spending you would do anyway. If you find yourself working hard to hit a target the bank has set for you, that is the moment to move the energy to your portfolio. It cannot be taken away from you. But it can get neglected.
Also read: The Premium My Father Sold
Ask Value Research 
 New episodes every Friday





 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


