




 AI-generated image

What is the best approach for retirees to derive a regular income that safeguards their savings and adjusts for inflation?
There's no one-size-fits-all answer. It depends on your income needs, risk tolerance, and the size of your retirement corpus.
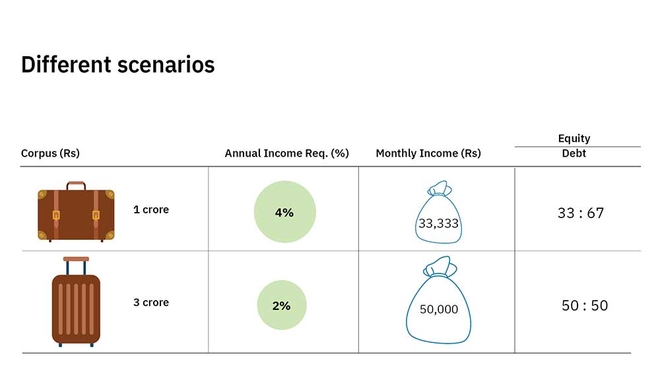
Broadly, your corpus should be invested in a manner that it can beat inflation as well as help you derive meaningful returns continually. You can follow asset allocation with at least 30-35 per cent in equity. And make sure that your annual withdrawal is not more than 6 per cent of your corpus. For the debt allocation, you can go with a mix of liquid funds, short-duration funds and guaranteed-return products like Senior Citizens Savings Scheme (SCSS).
Example: For a Rs 3 crore corpus and a Rs 50,000 monthly income requirement, which comes out to Rs 6 lakh annually, a Rs 1 crore portion of your corpus should suffice for your income. This leaves room to take a more aggressive equity approach since the income requirement is a small percentage of your corpus.
On the other hand, let's say you have a total of Rs 1 crore, of which 4 lakh is to be consumed annually, then you'll need to play it a little on the conservative-side.
Conclusion
This question was asked by a premium subscriber, and featured on our special series Subscribers' Helpline. If you'd like to get answers to similar questions, watch this month's episode.
Also read: Securing your retirement income
This article was originally published on September 27, 2024.
Ask Value Research 

 New episodes every Friday





 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


