


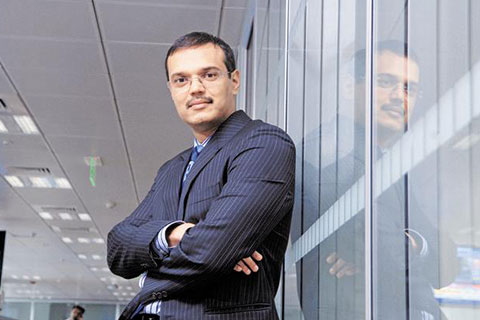
India's economy is already on the mend, evidenced by the fact that the earnings revision index has turned positive after being negative for seven years on the trot, says Ridham Desai-managing director, head of India research, and equity strategist for India at Morgan Stanley's research division-in an interview. Private capital expenditure is set for a recovery in the next 6-12 months, judging from improving order inflows, Desai said in an interview. Edited excerpts:
When you meet the larger investor community in Singapore, what is it that they want to know from you about India?
Three to four questions have come up. First, are domestic flows sustainable? One of the big stories in India is the secular shift that is happening in the household balance sheet. We have no doubt that they are sustainable; of course the levels can be debated because we've had a big surge in the last 3-4 months.
Second, the GST (goods and services tax) reform-will it work? I am actually surprised that people have doubts about this, because GST is the biggest reform that India has done-but we've had a little bit of turmoil that is actually quite par for the course. When I look back and reflect on how we thought about this back in April and May, it's turning out to be less problematic.
Third, what's the next thing from the government? The government has done a slew of things-the GST, DBT (direct benefits transfer), the state-owned bank recapitalisation, they've done well on infrastructure and have eased doing business to some extent. I don't think there's anything immediate in terms of legislation, it's more administrative. There's no major legislative agenda.
And the last question was on our recent report on Digital India. We think that India has made a massive inroad into digitization, and what could be the risks to that? So, that I think is pretty straightforward because it's cyber security and privacy around Aadhaar.
I've told the people here (in Singapore) that we've just seen a big fiscal stimulus from the government, so if you don't think that growth is going to turn around soon, you need to think again because India just did a $30 billion-odd recapitalisation for state-owned banks that will feed into credit growth. This is a major capital infusion.
Then, they've have done a fair bit of GST rate cuts, which is again in the nature of some stimulus. The farm loan waivers and direct benefit transfers add up.
These are significant transfers happening from a government that has until now been very stingy about fiscal spending. So there is a little bit of loosening of the belt because, I think, there is comfort on inflation and the fiscal front, and there is also an election in 2019. I think growth seems to be already on the mend, and we are seeing early signs of that. Earnings revision index in India has turned positive-this has been negative for seven years on the trot. So, you'll be seeing that in earnings as well.
Any specific concerns on India that investors here in Singapore have been asking you about?
I think the one concern is about oil. One of the smart things this government did three years ago was that when oil prices were falling, they increased taxes. In effect, they did not pass on the oil price decrease to the consumer-rather took them away as taxes and spent them on infrastructure, which I think was a very good policy. Now, if oil prices rise because of geopolitical tensions in the Middle East, I would characterize that as a supply side shock. When oil prices rise because demand is rising, it's not so bad for India because it gets matched by foreign flows. But when it's a supply shock, there are no matching foreign flows. That puts some stress on the economy.
Now, what choices will the government make-will they let retail prices rise or will they cut taxes? Either way it's a problem, because if you let retail prices rise, then inflation nudges higher, and if you cut taxes, it reduces your fiscal flexibility. It will take something out of the capex that the government is doing, at a time when capex is very crucial for growth. To me, that seems to be a pretty big risk going into 2018, and hopefully nothing untoward happens in the Middle East...But we will have to watch that carefully.
Are investors here concerned about India valuations?
There is nothing to be worried about. People look at the PE (price-to-earnings) ratio, but earnings in India are depressed. When you want to look at the PE ratio, you have to normalize earnings. If you do that, the market is not as expensive.
Another way of doing that is to look at price-to-book, which is a far more stable indicator. It looks through earnings cycles, and in India, that number is 3.1 times, which is bang in the middle of the historical average-so even relative to emerging markets, India is slightly below the historical average.
When you look at price-to-book, if the multiple is at 2, then you shut your eyes and buy equities in India and don't worry about anything else. If the multiple is approaching 5, then you sell your stocks and don't worry about where growth is heading.
But when the multiple is at 3, it is not actually providing you any information. Valuations are at a level at which, on their own, they do not give you a sense of whether stocks are to be bought or sold. Instead, you have to rely on stuff like earnings growth and interest rates.
I got more questions here (in Singapore) of sector-level valuations because within that 3.1 level, there is a fair bit of disparity-stocks that have done well and have been investors' favourite are no longer cheap.
The ones that have not done well, but also concurrently suffer from poor fundamentals are the ones that look cheap. So what do you do? That has been the trade all year with investors taking the risk and going contrarian. I see that happening more and more often, because domestic mutual funds have now become very big; hitherto they were capable of outperforming the index very easily because they were focused on midcap stocks but now because of their size, that strategy is no longer workable and they have to take greater risks.
People will make that call. Beaten down stocks where fundamentals appear to be weak but could turn around, are the ones in which you could actually put your money to work. The strategy we have is to focus on the change in return on capital (RoC) over the next two years as a filter to buy stocks, rather than the level of RoC.
As GST data starts coming in over the next couple of quarters, a lot more micro, small and medium enterprises (MSMEs) will have access to funding at competitive rates. How big a game changer is it?
Very big, because the entire MSME sector, which accounts for 85% of India's total employment, has been outside the formal banking system due to the lack of good data and also because of the practices in Indian banking. Bulk of India's banking sector has done only collateral-based banking hitherto.
That will shift to cash-flow-based lending since now you have good data on cash flow-that's what GSTN (GST Network) does, it provides that data. If you are a GST network participant, you can actually authorize GSTN to send that data to anybody you wish, such as a bank that proposes to give a loan. This data cannot be fudged; hence, banks will be able to lend against this cash flow and that is a big boon to MSMEs, given that they are the ones that don't have the collateral.
Large companies have always had collateral. We're not talking about the listed companies at all-there are about 5,000 listed companies in India and nine million firms on GSTN. Of this, six million firms may not have had access to the formal banking sector, which is why in our recent report, we call it the formalization and the financialization of India. These are game changing things.
There has been a lot of a debate in the media on job creation. Is that really a big risk factor and an area of concern?
It's a long-term concern, and it comes from the fact that India is going to integrate a large number of people into the workforce over the next 10 years.
You have to skill them appropriately and ensure that they are healthy, and therefore worthy of working. The near-term debate I think is a little bit overdone. If there was no job creation in India, I don't think we would get the growth or the consumption demand that we are getting.
The fact is, India sells a lot of stuff like 20-odd-million two-wheelers in a year-how do you sell so much unless incremental jobs are being created.
Private capex is something that has been talked about in the past couple of years. A lot of projections have also gone haywire. Do you think we now have enough indicators to say that in the next six months to one year, private capital will take off?
The answer is yes. Let me share numbers. Private capex in the previous cycle peaked at 18% of GDP and it's now down to 6%. Frankly, I thought it will bottom out at 8%, but it has gone down to 6%.
To that extent, we also missed it. Three years ago when we met, I was far more optimistic of a recovery, and three years on, that's not actually happened. So, it's taken a bit longer.
A part of it has to do with the banks' balance sheet, which did not get fixed in these three years. It's taken a bit longer, but finally the fix is coming.
A part of it is to do with the external economy, which was quite sluggish in 2015, and I think that also hurt private capex. This has also turned around in the last year and is being fixed. And part of it was also the fiscal compression that the government did to bring down inflation, which I think has lasted longer than we would have hoped for.
All these things have worked against private capex. Now, we are hitting the trough-the fisc has probably done its bit in terms of tightening, export growth has recovered and banks have been recapped. So, it's probably safe to say that in the next 6-12 months we will get a recovery. I'm seeing early signs- order books have started improving, largely led by government infrastructure spends and that's leading the overall capex. It looks unlikely that private capex goes back to 18%-that is a far cry. I think we will probably go back to double digits.
Do you think the banks' recapitalization is sufficient? Or is something more needed to get the banks on track?
The amount is very close to what we had estimated, so I think it takes care of the problem as far as capital is concerned, and that, therefore, allows the state-owned banks to resume lending at a stage when loan growth comes back. Otherwise, they wouldn't have been in a position to do that, but would rather have created a supply side constraint to loan growth. That constrain has been removed, which will now allow them to restructure their balance sheet and become more aggressive with their NPAs (non-performing assets) and take care of them. So, it does remedy the problem to most extent.
Does the jump in rankings in the ease of doing business actually correspond to increase in growth?
The only number to look at is FDI (foreign direct investment) to GDP (gross domestic product)-that's gone up steeply...fact is, the foreign investors have voted with their feet and they have put money to work and they are still putting money to work. So, there has been some change. Is it all done? No, there is more work to be done but, certainly the news is good.
In arrangement with HT Syndication | MINT
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


