


Instead of sticking to the rate cuts, RBI is trying to move liquidity into neutral zone and influence transmission of lower rates in the system, says, Amardeep Singh, Fund Manager, UTI Dynamic Bond Fund.
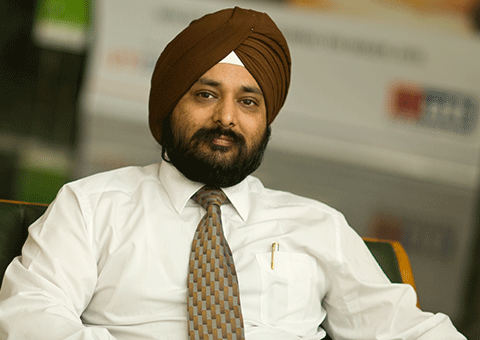
What is your outlook on interest rates in India?
Long-term rates presently reflect the recent rate cut and a stable global outlook. Further moves over the next few quarters will be driven by two events: the expected policy action from the US Fed during the year and the monsoon in India. This will have an important bearing in how the inflation trajectory moves forward. The 10-year government securities (G-Sec) may be range-bound within a narrower band compared to that of the previous quarter. The long-term rates would henceforth react more to technicals like open market operations, state government issuances and the Ujjwal Discom Assurance Yojana (UDAY) bonds in terms of supply.
So till we have some clarity from the Fed on its outlook and rate action(s), the 10-year yield should not breach the 7.53 per cent level. In the lower end the rates are not likely to fall below 7.40 per cent. Aggressive OMO purchases from RBI could help rates maybe breach this range at the lower end. However, we expect, nearer to the the Fed action there could be some volatility. The market does not expect more than one more rate hike, possibly in June and any indication to the contrary, could send the 10-year rates to 7.60-7.70 per cent level. Another year of sub-par monsoons could also drive rates northward as this will pull up people's expectation on inflation, mainly food inflation.
Looking at all the factors at the moment, while RBI may continue with its accommodative policy stance, I do not foresee another rate cut from the RBI this year. The focus has now shifted to influencing transmission through changing the liquidity paradigm instead of emphasizing on more rate cuts. This means that instead of sticking to the rate cuts, RBI is trying to move liquidity into neutral zone and influence transmission of lower rates in the system. If this happens, the volatility in the overnight rates and banks behaviour towards lowering lending rates will definitely improve. This with the marginal cost-based lending rate regime should help bring about transmission of the 150bps of rate cuts more effectively.
What is your framework of taking a duration call?
Our duration calls are built around a top-down approach on the forecasted trends in key macro variables. We have a healthy discussion in the team on possible outcomes and the risks we can see to these outcomes before arriving at our view on rates. Once a fundamental view has been taken on rates, we consider technical factors such as market positioning, demand-supply etc and tactically alter our durations.
What is your framework of taking a credit call? What kind of credit risk you don't take at all?
All investments that we make in the non-sovereign category of bonds are based on our internal research view without too much reliance on public ratings. We have had a strong framework for credit calls built around understanding the business models, cashflows, instrument structures and equally importantly risks which further encapsulates combined knowledge of our research resources within the credit and equity analysts.
In your view, how should a long-term fixed income investor optimise his returns?
We believe that long term investors should re-balance their asset allocation within their fixed income portfolio now more in favour of the short term income category without completely exiting the long-term debt funds. While a large part of the rate cut cycle behind us, RBI continues to be in an accommodative policy stance with a focus on bringing system liquidity into a neutral zone. Short-term funds stand to gain from any easing in liquidity situation as RBI intends to move to neutral liquidity regime in near future. Also, this category may be less volatile when compared to long term debt funds at a time when scope for further rate cuts may be limited.
What will you attribute the above average performance to?
In depth research, a strong team, a mix of above two (Duration & Credit) and maybe a bit of luck too!
Please click here to read the analysis of this fund.
This article was originally published on June 24, 2016.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


