


I am an engineer. I am 39-year old and married. I have a 4-year old daughter. I own 3 properties which give me a rental income of ₹30000 per month. I do not have any outstanding loans. I would like to use these properties to generate cash flow in future which may require an investment of 50 to 75 lakhs in 2 to 3 years. I started investing via SIP in November 2007. Me and my wife have term life insurance policies.
I have surplus disposable income of ₹4 lakh p.m. My goals are daughter's education , her marriage and saving for my retirement. I also wish to go to vacation with my family every 2 years.
Please suggest me a suitable plan to reach my goals on time.
- Ravi Kulkarni
What he has (Cash flow)
- Monthly disposable income of Rs 4,30,000
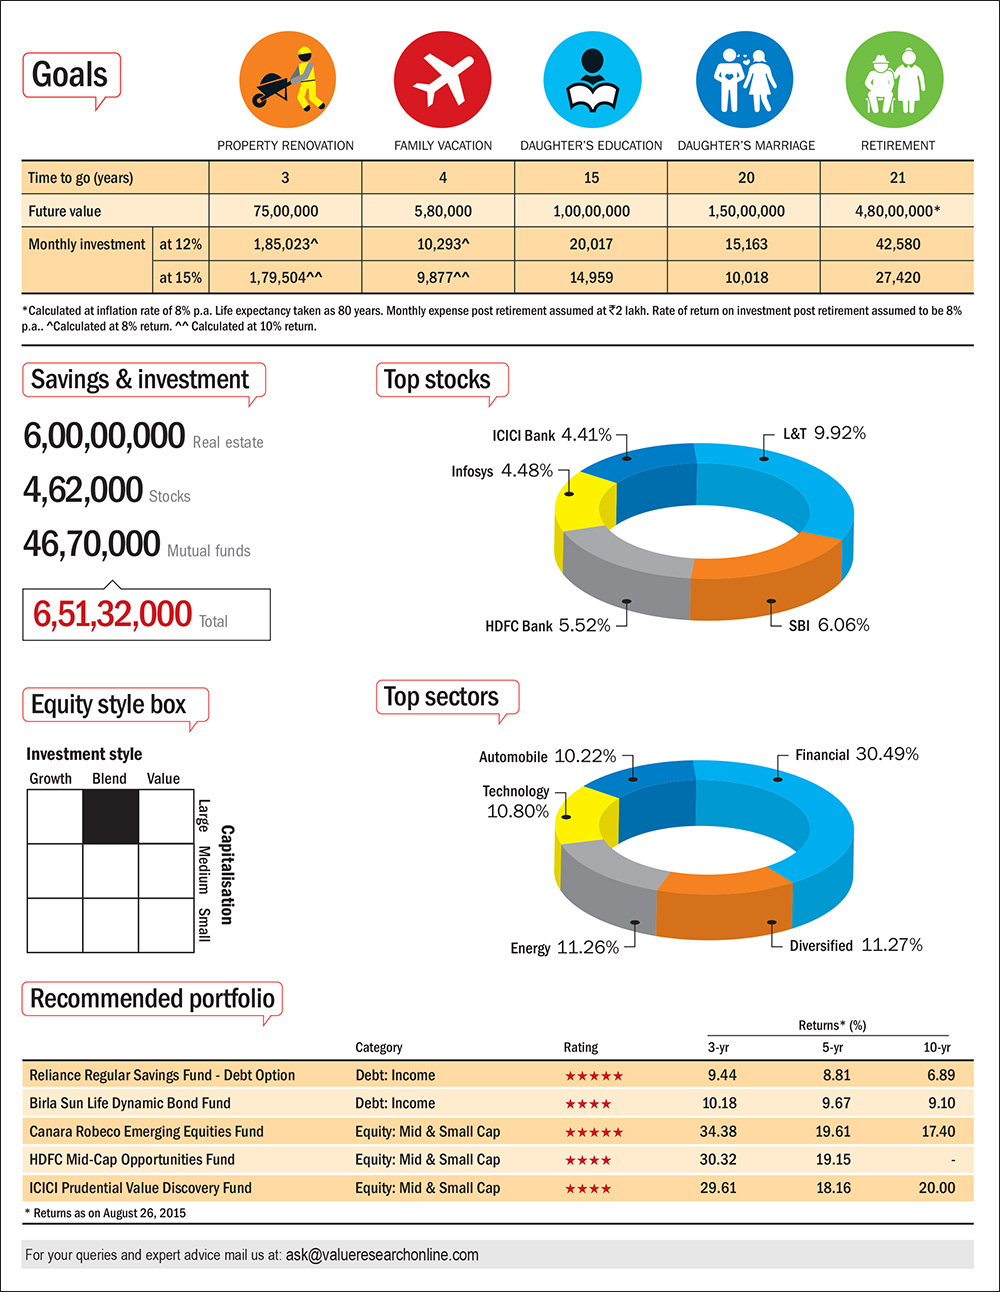
What he wants (Goals)
- Family vacation
- Property renovation
- Daughter's education
- Daughter's marriage
- Retirement
What he should do
Emergency fund: Ravi Kulkarni must maintain an emergency fund equal to at least six-month expenses as he has a kid. He must keep some amount as cash at home, in bank savings account and the remaining in liquid funds depending on his needs.
Health insurance: Ravi must go for an adequate family floater policy as health insurance. ICICI Lombard Complete Health Insurance and Apollo Munich Easy Health Plan are our recommendations.
Life insurance: Ravi Kulkarni and his wife are insured under term plans. The insurance cover must be enough to take care of dependents. Since life insurance is needed only for an earning member, Ravi may discontinue his wife's term plan if she is a homemaker.
Investments: Ravi Kulkarni invests in equity shares as well as mutual funds. Since we don't comment on individual stocks, we won't be able to tell him what stocks he should buy or sell. However, given that he has limited understanding of finance, direct equity exposure should not exceed 10-15 per cent of his total portfolio.
Ravi has a long time to reach his goals. He should invest in mutual funds through SIPs and benefit from the expertise of fund managers. Until now he has invested in large-cap mutual funds. We recommend investing in mid- and small-cap funds. These can give him better returns than large-cap funds over the long term. He may discontinue his current SIPs and let the amount already invested grow.
For the near term goal of property renovation, income funds would be apt. For his vacation after two years from now, he may utilise his equity investments. For the next vacation due after four years, he can invest in income funds. For later vacations, he should invest in mid- and small-cap funds. Once he reaches near his goals, he must start switching to debt to lock in the returns generated.
This article was originally published on August 28, 2015.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


