


There are many things Infosys did wrong in the past few years, it missed many opportunities, lost market share to rivals TCS and HCL Tech. Its famed margins buckled, employees started leaving in droves, utilisations fell and earnings couldn't match that of its peers. Infosys had become a shadow of its former days and seemed to have lost its way.
Narayana Murthy forced out of retirement had to take charge went CEO shopping. He homed in on Vishal Sikka, the erstwhile CTO of SAP, the world's third largest technology company with revenues of Euro 16.8 billion (2013).
Sikka has a tough task at his hand. He has growth to take care of, he has lost market share to take back, he has margins to worry about and attrition to stop. When he does all this, he has to set a direction that will set Infosys to regain its lost market leadership.
Is Sikka the right man for the job?
To understand why go back to SAP circa 2008. The company had bloated, become slow to respond to client requirements and new competition was eating into its market share. SAP was facing what Infosys now suffers from.
In comes Sikka, in charge of innovation and launched HANA, the world's fastest database with presence in the cloud. HANA went on to become a superhit that would generate $1 billion in sales for SAP. Sikka had made SAP more customer-centric and more agile - much like the nimbler start-ups - the very things he now wants Infosys to become.
What is Sikka's strategy?
To correct everything that Infosys has been losing out on, Sikka in his first earnings call at Infosys has laid out his broad strategy.
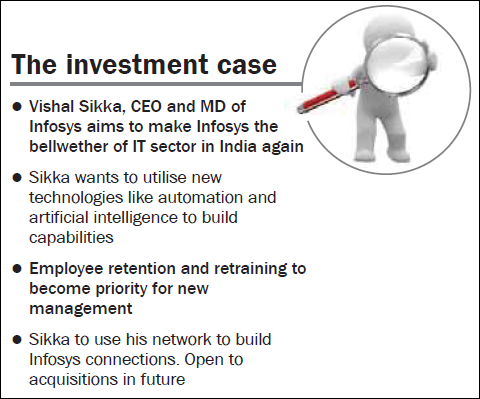
Greater role for new technology: Sikka wants Infosys to utilise the latest in emerging technologies to get ahead of peers. Automation is a big future area as is artificial intelligence which Sikka wants Infosys to utilise to improve service offerings and delivery to clients.
The importance of partners. Sikka has had a long-standing work experience at SAP. As such, he understands the role partnerships play in success of a company. He is looking at strengthening partnerships with other technology firms like Microsoft, SAP and Oracle. Sikka would also partner with technology start-ups in the future. That will keep Infosys ahead of peers in emerging and nascent technologies.
Sharper workforce. Sikka would like his employees to train on newer technologies. He is looking to collaborate with technology institutes to bring that training to his employees especially in design thinking, artificial intelligence and data sciences.
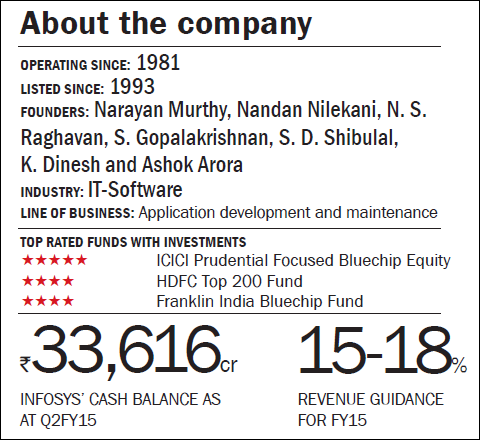
Inorganic growth. The markets have for a long time now hoped that Infosys would utilise its ₹33,000 plus crore cash balance to make acquisitions. Infosys has not made any major acquisition for many years now. That will change. Sikka indicated Infosys will look for acquisitions in newer technologies and those that grant it access to newer markets. Japan would be a key market to improve presence as it is the worlds second largest IT market and no major IT company barring TCS has any significant presence there.
Sikka is confident that these broad initiatives will help the company grow revenues by 15-18 per cent and maintain Ebit margins of 25-28 per cent. More specifics about Sikka's strategy are expected by end of FY15.
In the meantime, Infosys is pulling up its socks and getting a few things right. Here are some of them.
Healthy client addition. Infosys added 49 clients in Q2, which compares well with the 238 clients it added in FY14. Deals won this last quarter totalled $600 million taking total cumulative deals in H1FY15 to $3.6 billion. Revenue per customer improved to $2.41 million compared to a decline in the past six quarters. The top client grew by 3.2 per cent; the top five clients grew by 2.4 per cent while the top ten clients grew 3.2 per cent respectively.
Margin gains. Ebit margins came in at 26.1 per cent for the September 2014 quarter up from 24 per cent it reported in FY14 on account of higher utilisations and offshoring. The company has guided margins could remain at 25-26 percent as it looks to invest in brand building and developing capabilities in newer technologies.
Better Utilisation but the attrition headache. Utilisations have gone up from 77.4 per cent in FY14 to 82.3 per cent. Attrition at 20.1 per cent is still a headache. Sikka in a bid to stem has hiked salaries, given promotions and called ex-Infoscians to rejoin the company. These measure appear to be working - month-on-month attrition is now down.
Focus on selling and marketing (S&M). Sikka wants more investment in marketing. S&M spends jumped from 5.2 per cent in June 2015 quarter to 5.8 per cent in last quarter.
Outlook
Infosys has maintained its revenue guidance of between 7-9 per cent for FY15. Q1FY15 saw Infosys report a growth of 2.3 per cent while Q2 was better at 3.1 per cent. Infosys needs to grow at 1.6 per cent in the remaining two quarters to meet seven per cent guidance and at 3.6 per cent to meet the upper end of the forecast.
Valuations
The story of Infosys' decline can be best looked at with a comparison with its arch rival TCS. Infosys had always maintained a lead over TCS in the valuation game ever since TCS got listed in 2004. By October 2006, the valuation lead that Infosys maintained over TCS was at its peak - Infy traded at 38 times its earnings while TCS at 30 times. Over the next five years, both these giants battled it out and the valuation gap narrowed down between them until in April 2011, TCS beat Infosys at the valuation game has ever since maintained its lead. Today TCS trades at 25.6 times its earnings while Infosys at 18 times.
At a valuation of 18 times, if Sikka is actually able to pull up Infosys above its three-year average earnings growth of 15 per cent, then Infosys appears as a good bet. By all indications, Sikka is the right man at the right place and at the right time to perform this miracle.
This article was originally published on December 11, 2014.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


