


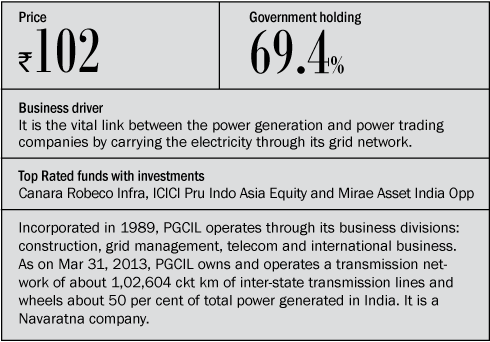
Power Grid Corporation of India (PGCIL) is the central transmission utility (CTU) for the power sector which transmits electric power across India. The company is a major player in developing the National Grid, a niche programme initiated by the government. With grid network of 1,02,604 ckt km and more than 50 per cent of the total transmission share in India it is one of the largest power transmission vehicles in the world.
PGCIL has presence in the power transmission sector in South Asia, Middle East Asia and African countries and provides consultancy services in UAE, Nigeria and Bangladesh. The company also operates as a network provider to the telecom sector for their broadband and other networks.
Strengths
PGCIL is a monopoly over long distance power transmission with its wide grid network. The networks is supported by 173 substations and transformation capacity of about 1,80,000 MVA and inter-regional power transfer capacity of 30 GW as in FY13. PGCIL is continuing its growth story and witnessed a strong growth of 27 per cent in revenue from transmission charges in FY13 over the last year.

The efficiency with which the company works is a positive with the transmission system availability of 99.90 per cent speaks highly. Tripping due to failures reduced to 0.32 in FY13 from 2.07 in FY10. This was possible due to improvement in the deployment of technologically advanced operational techniques.
Over the years PGCIL has maintained an average net margin of 31 per cent and average cash margin of 54 per cent over the past five years. In the midst of rising input cost and infrastructure costs, maintaining consistent margins is a remarkable feat. Further, PGCIL does not face working capital issue as it has negative net current assets, which is mainly funded by the advances from clients and deposits received from the contractors.
The company is widening the National Grid, which is planning to increase the power transfer capacity to 65,550 MW by adding 38,000 MW. Raising funds for this expansion will not be difficult or strain the company's finances. Further, the consultancy division of the company has started to perform and earned ₹315 crore in FY13. The prospects of this division look compelling as it has bagged 26 new domestic assignments from the public and private sector companies and 9 new international projects.
Concerns
The company has a high debt to equity ratio of 2.72 as on FY13 end which has risen over the years. The debt level will further grow with planned capital expenditure and to improve this ratio, the company needs to infuse more equity, which would result in equity dilution for equity investor over the long term, which is concerning.
But the big concern that looms is the pricing model enforced by the Central Electricity Regulatory Commission (CERC). In its recent regulation the commission has carried the same pricing RoE base of 15.5 per cent with additional 0.5 per cent for timely completion of projects. The CERC has done away with the gross tax benefit, which can negatively impact the company.
Moreover, the company is already facing pricing controversies with few states and there are cases pending in the courts. Any adverse ruling may also affect the margins of the company. Also short term concern of the currency rates fluctuation looms around.

Valuation
The stock is trading 17 per cent higher than its listing price of ₹85 in 2007. At current price of ₹100, price to earnings stands at 10.3 which is 45 per cent lower than its all time median of 19. Price to book of 1.63 is 35 per cent discount to its average of 2.5. PGCIL serves as an ideal investment opportunity who are very bullish for power sector and participate in the sector's growth.
This article was originally published on March 20, 2014.
Ask Value Research 
 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


