


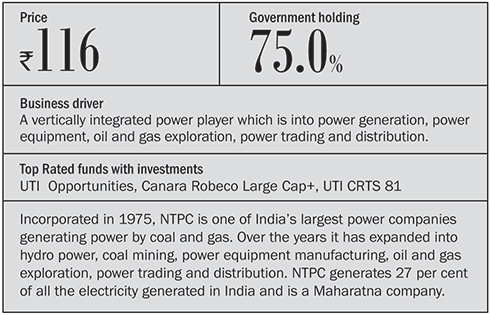
NTPC's principal business includes generation and sale of bulk power. The company has a total installed capacity of 41,184 MW (including 5,364 MW through JVs and subsidiaries) with 15 coal based and seven gas based stations spread across the country.
The company also has a consultancy division wherein with its expertise it provides its advisory services to clients from India and abroad. With 20,064 MW capacity under construction, NTPC is well poised to achieve the 12th plan target of 12,038 MW and even surpass it.
Strengths
NTPC scores highly being among the lowest cost producer of power at an average selling price of ₹2.96 per unit in 2012-13 due to its integrated operations and has a healthy net margins of over 18 per cent, averaging over the past 5 years. This alone makes the company have a lion's share in the power generation sector.

Further, the cash realisation of the company is quite efficient and although all major clients being distressed state electricity boards the company was able to recover 100 per cent bills, partly because of its tripartite agreement with RBI towards realisation.
Although nearly 85 per cent of the company's expenses go towards meeting coal and fuels, it is in line with peers.
To tackle the rising cost of coal and counter the dependence on coal import, the company is expanding its captive coal mining capacity. NTPC was recently allocated of coal blocks and has coal reserves of around 3 billion tonne with capacity of about 53 million tonne per annum (MTPA). However, the first coal mine Pakri-Barwadih is expected to be operational in FY14 and the rest are still some time to go.
The company is aggressively adding to its capacity and plans to raise it to 1,28,000 MW in the next couple of decades.
Apart from its original coal and gas based thermal power generation it has ventured in to hydro power, non conventional power generation and nuclear power.
According to the company, it has identified that hydroelectric potential in India is above 1,45,320 MW whereas the current installed capacity is just 39,491 MW. To leverage the opportunity it is setting up two hydro projects in Himachal Pradesh and Uttarakhand.
Concerns
One of the big worries is plant load factor (PLF), a measure of average capacity utilisation. In FY13, PLF was 83 per cent, which dropped by 8 per cent basis point from 91 per cent in FY09. The plant availability factor (PAF), which estimates the time for which the plant is used also declined to 88 per cent over the years due to interrupted supply of coal and gases. With more use of captive coal mines the company may able to handle the issue.
While the company has ambitious expansion plans, NTPC faces delay in its projects due to delays in environmental approvals and land acquisitions. Further delays in the projects can escalate the initial costs for the company.
Likewise, as the company is regulated by the Central Electricity Regulatory Commission (CERC), the company does not have command over the pricing. Recently CERC came up with a pricing model which can negatively impact the company wherein it has proposed to go with base RoE of 15.5 per cent with additional 0.5 per cent for timely completion of projects for generating and transmission projects, which can put the existing higher RoE under pressure.

Valuation
The stock was trading at 7-year low in the current financial year and now at a price to multiple of 9.3, 45 per cent lower than its 10-year median. The current price to book of 1.32 is 42 per cent discount to 10-year average of 2.27. The company has a business model which is prone to regulations and hence can be risky bet in short to medium term. Buy it for very long term.
This article was originally published on March 14, 2014.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


