


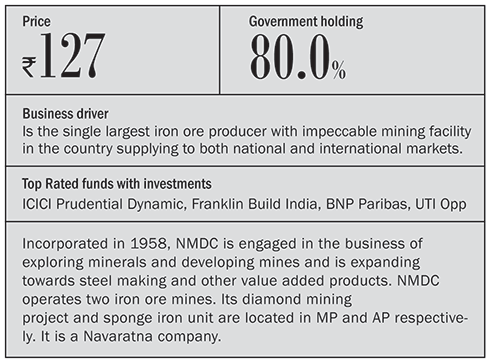
The country's largest iron ore producer has reserves in excess of 1.3 billion tonne and is known worldwide for the high iron content in its ores. NMDC has also been carrying out scientific mining of the mineral deposits by mechanised means which has resulted in additional mineable reserves from its existing mines. Through its international global investment division, NMDC Global, its focus is on expanding its geographical footprint around the world. It has an MoU with OJSC Severstal, Russia, to jointly set up an integrated steel plant in Karnataka.
Strengths
NMDC's biggest strength is its superior and high quality ore. Selling high quality ores also reduces competition from low priced-low quality suppliers. Current contracts are for 35-36 million tonne, higher than the company's FY14 despatch target of 30 million tonne.
To meet the rising demand, NMDC is steadily building up its capacity, which is set to go up to 48 million tonne by FY15.

Being the largest miner, the company also has an enviable say in pricing of the ore. Though there were several price cuts in 2012-13 on account of sluggish steel demand in the country, price hikes were initiated in September. Iron ore prices are expected to sustain at current levels in the near term, especially with the rising prices in international markets. That the company's pricing is reference for other miners, speaks volumes of the strength it possess.
Financially, the company is cash rich with net cash totalling ₹22,500 crore as of September 2013. That constitutes roughly over 40 per cent of the company's current market valuation. The company also has a high dividend yield of 5 per cent, despite concerns over weak commodity cycles.
Concerns
The fortunes of NMDC are inextricably linked to global ore prices like any other metals company. Lower realisations (down 15 per cent y-o-y) on account of lower prices resulting in revenue decline of 5 per cent in the latest quarter even when sales volumes went up by 11 per cent in the same period. Realisation is of concern because in FY12-13 it had a realisation of ₹4,000 per tonne compared to ₹3,776 per tonne now.
Falling realisations can wreak havoc with margins. Ebitda margin contracted 8.81 per cent in the latest quarter, which was the worst margin the company witnessed in the previous eight quarters. Similarly, Ebitda/tonne was down 25 per cent; another 8-quarter low.
NMDC's despatches depend on its evacuation infrastructure, with 85 per cent of despatches made on rails. This mode needs an upgrade. Although NMDC has signed an MOU with Railways for doubling of rail lines, it could take as much as five years to achieve. NMDC also plans to build its own slurry pipeline from Kirandul to Nagarnar and between Nagarnar to Vizag.
Plans to diversify into steel production comes with different challenges. Land for its integrated steel plant in Jagdalpur, Chhattisgarh, has been acquired. However, till the time that the plant breaks even, it could be value destructive proposition for NMDC. The company has already spent ₹3,000 crore. Commercial production is expected to start around FY16. Moreover, the steel plant is located in Naxal affected area which poses other disruption threats.

Valuation
NMDC trades at eight times its earnings. That cash accounts for 40 per cent of the company's market cap makes NMDC all the more attractive. With low capex programmes, NMDC sets itself apart from many of its competitors. Even though it will remain vulnerable to global ore prices and is a pure commodity play, NMDC by virtue of its high quality ore and one of the highest margins in the business is a strong long term investment bet.
Ask Value Research 
 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


