


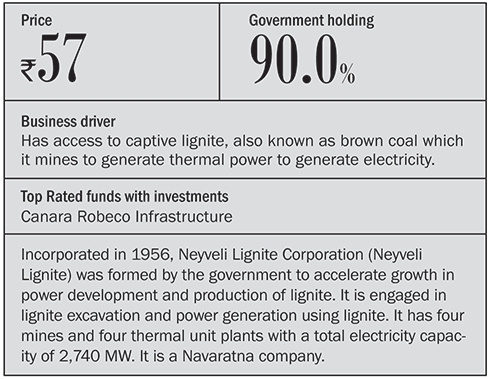
Neyveli Lignite operates in two business segments namely; lignite mining and power generation. The aggregate installed capacity of all lignite mines stands at 30.6 MTPA as on March 31, 2013, and 3 thermal plants of 600 MW, 420 MW and 1,470 MW installed capacity are located at Neyveli with the fourth mine with a capacity of 2.1 MT per annum and thermal plant with capacity of 250 MW are located in Barsingsar, Rajasthan taking its combined capacity to 2,740 MW. The company is also the nodal agency for lignite exploration and also sells raw lignite to other power utility companies from the surplus.
Strengths
NLC is considered to operate the largest open-pit lignite mines in India and has sufficient lignite. It has a healthy margin of an average 48 per cent over the past five years and the average net margin for the same period being 28 per cent. Revenues have grown at a decent annualised growth rate 13.4 per cent over the last five years but the operating income has not been able to match the same pace and instead grown at only 7 per cent. This is due to rising operating costs on account of rise in employee cost and administrative costs.

Coal generates more heat than lignite, which makes it more effective to generate electricity and hence the company is venturing into coal-based thermal power generation. NLC plans to invest ₹29,239 crore in coal based power of which ₹26,728.40 crore will be for the development of power projects and ₹2,510.70 crore for coal mining. The project with a capacity of 1,000 MW is planned at Tuticorin in Tamil Nadu and is expected to commence from end of FY14. This diversification will help the company improve its return on equity.
There are several other projects that are under various stages of construction adding to 6,480MW power with the Sirkali thermal power project of 4,000 MW being the biggest. TPS-I with 600 MW capacity at Neyveli has become out dated and will be replaced by a 1,000MW thermal power plant known as Neyveli New Thermal Power Station (NNTPS) instead. This replacement will come with capital expenditure of ₹5,907 crore with target commissioning in FY-14 or FY15.
Some of the other ongoing projects outside Tamilnadu include the 2,000 MW coal based thermal power plant at Odisha, 1,000 MW power plan in Gujarat in a JV with Gujarat Power Corporation and 250 MW Bithnok thermal power plant in Bikaner, Rajasthan among others.
Concerns
The biggest concern is the outstanding to be received from the state electricity boards which add up to ₹3,802 crore as on March 31, 2013. This amounts to over 65 per cent of the revenue earned in FY13 and can lead to becoming a large bad debt, if it continues the same way. Moreover like other power utility companies NLC is also subject to dynamic pricing policy of the regulatory body CERC.
NLC's coal based under construction Ghatampur thermal project in Uttar Pradesh will be sourcing coal from mines allocated in Dumka district of Jharkhand. However, at the moment operations at the Dumka mines are hit and stalled due to agitation by the local population. The delay in coal sourcing will impact the schedule of the project, which is a short-term concern for now.

Valuation
The stock at a current price is trading at price to earnings ratio of 7.26 and is 40 per cent lower than its 10 year median. Also the prices are 27 per cent discount to its book value and is 55 per cent lower than 10 year average. This is due to non recovery from the SEBs and is not clear when will it be recovering. The growth in prices of the company majorly depends on the fate of its recovery and timely completion of its expansion plans.
This article was originally published on March 11, 2014.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


