


Cash conversion cycle is the number of days an entity takes to convert its operation into cash. It starts with buying raw material on cash or credit and ends when cash is realised by selling or from the debtors. But actual time taken to manufacture or convert raw material into finished product and selling thereof may vary hugely according to the business nature and industry.
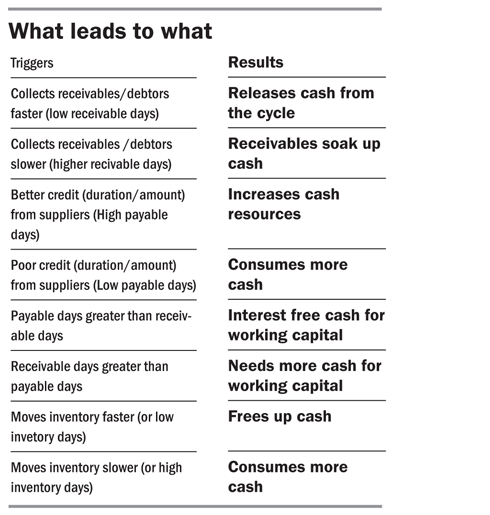
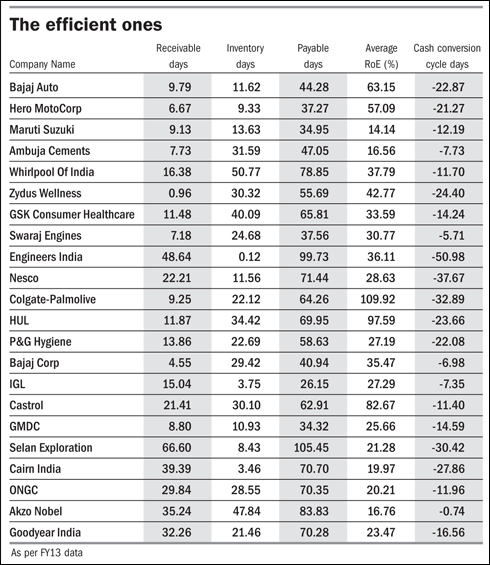
But despite the business nature, cash conversion cycle can be shortened by effectively managing receivables and payables. If cash conversion cycle is negative, it means the company is able to realise cash from its customers and has sufficient time to pay creditors. This pushes down the funds required for day-to-day operations to almost zero and that saved sum instead earns interest.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


