




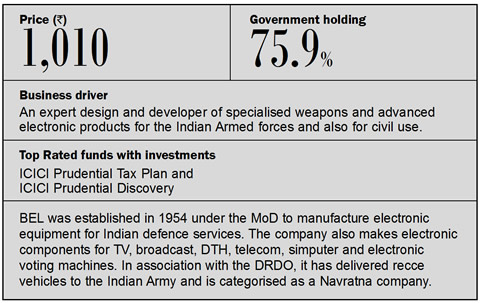
Bharat Electronics (BEL) manufactures electronic products for the Indian defence sector. The company operates under the Ministry of Defence and has become an expert in designing and developing specialised weapons and advanced electronic products not only for Indian armed forces but also products for civil uses.
BEL, with its wide product range, also caters to overseas defence needs and its exports include coastal surveillance system, radar warning receiver, radar finger printing system, fitted up and bare shelters and electronic voting machines, among others.
Strengths
The company has no dearth of orders, with its order book touching Rs 24,794 crore as on October 1, 2013. BEL also does not have any logjam issues, with its infrastructure well stacked with the capacity to generate Rs 10,000 crore revenue per annum. Further, the expenditure on defence sector as budgeted by the government has risen over the years to Rs 86,714 crore and is expected to further grow.
Where the company scores is with its vast knowledge and R&D division which boasts of numerous patents that makes it a strong player in a niche field. BEL has continuously focused on its R&D and incurred around 8.5 per cent of the revenue on the same in FY-13.
Technology tie-ups with institutions like the DRDO, ISRO, CSIR, C-DAC, C-DOT give it an exclusive positioning. The company also utilises young talent from leading institutions like the IITs, NITs and IISc for the development of new products and improving existing portfolio. This way its own R&D division has developed technologies and indigenised their operation and saved itself from depending on costly technical know-how or outsourcing.
The company is a strong exporter, especially in the radar and communication segment which has wide demand in the overseas market. Its total exports in FY13 stood at $32.78 million. And, to cater to the international market the company is enhancing its capacity and conducting new tests and the resource for the same is not a problem with huge cash pile up of Rs 4,500 crore. Rising crime and regulator compulsions have increased the demand for security systems, especially in the civil segment, which could become a major growth driver. It is also a strong player in the smart cards.

Concerns
The company has high working capital, which is because of the high debtor and inventory level.
As on March 31, 2013, the debtors, inventory and advances for purchases add up to Rs 8,912 crore which is short funded by creditors and advances received from clients of Rs 7,479 crore. A model of low credit time to pay the creditors by way of 77 payable days with high receivable of 176 days has increased the time it takes to convert its operation into cash. Although the high receivable days can partially be attributed to higher sales in the last quarter of FY13 which anyhow will be realised in the next financial year, for its good, the company needs to bring down the working capital and improve its receivable days by reducing it.
Another area of concern is unattractive margins. This is a constant concern for the company which has the government as its major client. Moreover, the payment model adopted by the government is very conservative when it comes to paying the companies that it owns. Also, the company needs to brace up to the challenge of private players gaining entry into the sector.

Valuations
At current price the stock is trading a price to earnings multiple of 9.5 and price to book of 1.29 which is 60 per cent discount to its 10-year average of 3.16. A debt free and cash rich company, BEL is a value stock, but value unlocking heavily depends upon government's continued interest in defence.
This article was originally published on February 12, 2014.
Ask Value Research 
 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


