


Shariah-compliant funds avoid the traditional sin industries, such as gambling, alcohol and tobacco. To tap potential investors, the Shariah index was constituted in 2008 and later two new schemes hit the market to cash in the philosophy. But Tata Ethical has been around since 2011; though it settled for its current name only in 2011. These three funds collectively manage a paltry Rs 128 crore as on March 31, 2013 and despite two of the schemes carrying an ethical epithet to not to be seen as targeting a particular community, these funds have not caught the fancy of investors.
What hurts the performance of these funds the most is the absence of exposure to the banking and financial sectors owing to the interest bearing activities by stocks in these sectors which goes against the Shariah principles. However, the strategy is a boon during bear phase, which is reflected in the performance of these funds in 2011.
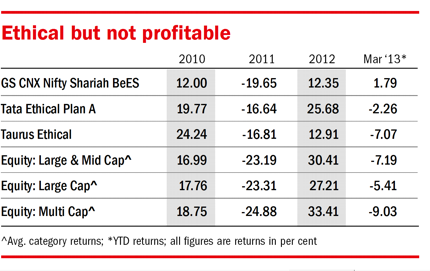
At best, these schemes can be a good bet when the markets are down, but that is more of a selection to make in hindsight. Ethical investing has failed to match the investor expectation, which leaves the debate open for investments in such funds as it may match an investor’s principles but may not be profitable.
Ask Value Research 
 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


