


In the May 2012 issue of Wealth Insight, we had done a story ‘A smokescreen of performance’ and asked our readers to stay away from Amar Remedies and several others despite such companies showing promising growth on the books.
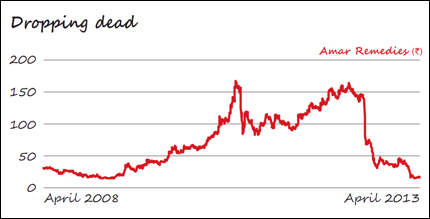
Since then Amar Remedies has dropped to one-tenth of its size from Rs 150 last year to Rs 15 today. No doubt these companies had shown a healthy growth in their revenues but we were suspicious of their sustainability. Why? Because they were recognising their revenues too early and did not manage their receivables properly which lead to a burst. It further emphasises the need to not just look at the income statement of a company but also its cash flow and balance sheet.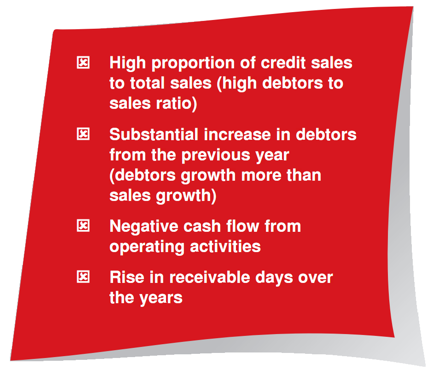
Once again we have compiled a list of such companies which look shaky and may not be able continue their impressive run. The criteria by which we arrived at the list is mentioned in the box above. 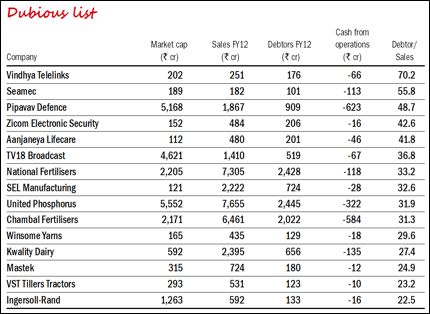
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


