


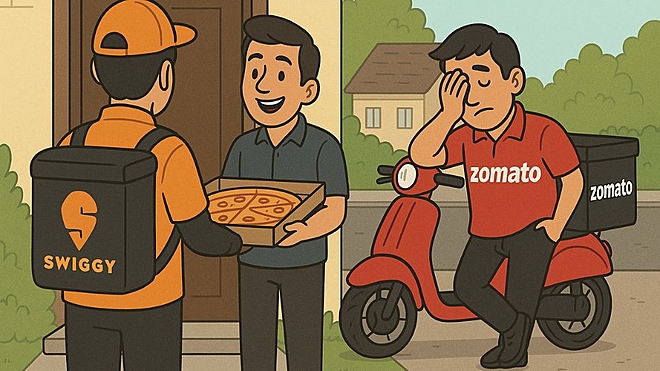
 AI-generated image
Swiggy's stock price soared by 12.49 per cent in intraday trading on the Bombay Stock Exchange (BSE) today, marking its most significant intraday rally in 2025. This surge follows the announcement that its 10-minute food delivery service, Bolt, has expanded to over 500 cities in India. The stock closed at Rs 305 on Friday.
Swiggy Share Performance and Market Dynamics
Stock Surge and Expansion of Bolt
Swiggy shares experienced a notable increase, reaching an intraday high of Rs 337.55. This surge is attributed to the rapid expansion of Swiggy's Bolt service. Bolt, which was launched in October 2024, now operates in more than 500 cities across India. Approximately one in every ten food delivery orders is delivered through the Bolt service. This expansion comes at a time when competitor Zomato is discontinuing its 10-minute delivery service, Instant, citing weak demand and a lack of profitability.
Analyst Ratings and Market Sentiment
Despite recent volatility, analysts remain largely positive on Swiggy's prospects. According to Trendlyne data, the average target price for Swiggy's stock is Rs 455, suggesting a potential upside of 49 per cent from current market prices. The consensus recommendation from 21 analysts is a 'Buy'.
Key Financial Metrics
Here's a snapshot of Swiggy's key financial metrics:
| Metric | Value (Rs Cr) |
|---|---|
| Market Cap | 69,806.26 |
| PE Ratio | -26.95 |
| EPS (TTM) | -11.33 |
| PB Ratio | 9.28 |
| 52 Week High/Low | 617 / 303 |
Recent Financial Performance
In the third quarter of FY25, Swiggy reported a net loss of Rs 799 crore, which widened from Rs 574.4 crore in the same period last year. However, revenue from operations grew by 31 per cent year-on-year to Rs 3,993 crore, indicating strong demand. Swiggy's Gross Order Value (GOV) also rose by 38 per cent year-on-year to Rs 12,165 crore.
Valuation and Analyst Perspectives
Earlier in the year, Kotak Institutional Equities initiated coverage on Swiggy with a 'Buy' rating, setting a fair value of Rs 500 on the stock. Bernstein also initiated coverage with an 'Outperform' rating, with a target price of Rs 635, suggesting a 29 per cent upside from previous levels. However, Invesco has marked down Swiggy's valuation to $12.7 billion.
Challenges and Future Outlook
Stock Performance and Losses
Despite positive analyst ratings, Swiggy's stock has faced challenges. Investors have experienced losses due to the stock's decline, partly attributed to disappointing Q3 earnings and the unlocking of shares post-IPO. The stock debuted at Rs 420 per share in November 2024 but is now trading below its listing price.
Quick Commerce Expansion
Swiggy's quick commerce business is expected to post rapid growth. Kotak projects a 63 per cent GMV CAGR and 74 per cent revenue CAGR over FY25-28. However, this expansion requires significant investment, and the company anticipates EBITDA losses to peak in FY26, with positive EBITDA expected by FY28.
In Conclusion
Swiggy's recent stock surge reflects investor confidence in its expansion of the Bolt service and its potential to capitalize on Zomato's retreat from the 10-minute delivery space. While challenges remain, analyst ratings and growth projections suggest a positive outlook for the company.
Ask Value Research 

 New episodes every Friday







 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


