




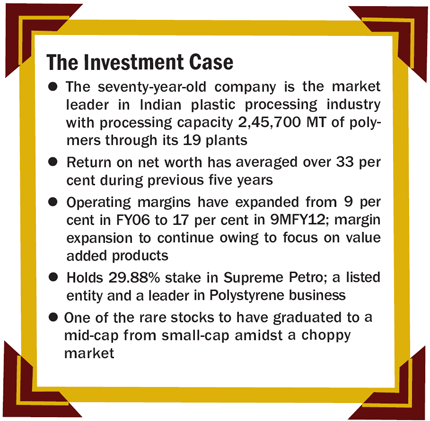
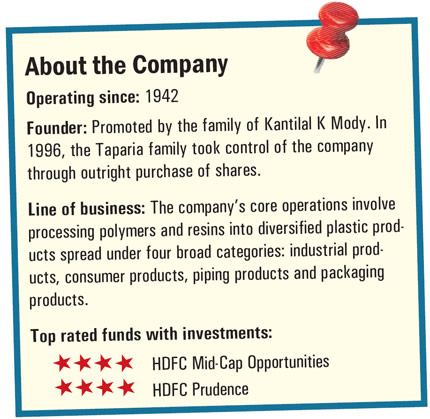
Look around and chances are that every second object you'll see would be made of plastic. From cola bottles to toothpaste tubes, from electronics to cars - we cant really do without plastic. But it wasn't like this in the 80s and the 90s. Toothpaste used to come in aluminum tubes, bottles containing our favourite soft drink or tomato sauce were all made of glass and even the buckets, crockery and furniture were seldom made of plastic. Things have changed drastically since then; all thanks to those enterprising few who extracted the maximum out of this opportunity. Supreme Industries (SIL) is one such company and is today acknowledged as leader in the country's plastic industry. Whether its furniture or pipes, this 70-year-old company has built a credible name for itself.
According to the All India Plastic Manufacturers' Association (AIPMA), the domestic consumption of plastic has been growing at 10-12 per cent CAGR over the past decade and is all set to reach the 12.5 million tonnes mark (estimated) in 2012 from 9 million tonnes in 2010, which will make India the third largest plastic consumer after US and China. In the past 40 years, India's per capita plastic consumption has increased from just 1 kg to 8 kg (2010). By 2015, this figure is expected to reach 16 kg; a 15 per cent CAGR during this five-year period.
Strengths
SIL clocked a record turnover of Rs 2,769 crore in the last financial year, making it one of the biggest players in the Indian plastic industry. Its 19 manufacturing units together process around 2,45,700 MT of polymers every year (among the largest in India), further translating into a comprehensive product portfolio. It also counts who's who of the Indian industry, such as Tata, Maruti Suzuki, Whirpool, Exide, as customers.
Piping system is the biggest contributor to the company's overall revenues whereas furniture segment contributes the least. SIL has been very smart in following a strategy that maximises contribution by value added products. It is reflected in its operating margins which have improved from 9 per cent in FY06 to 17 per cent in 9MFY12 (June ending).
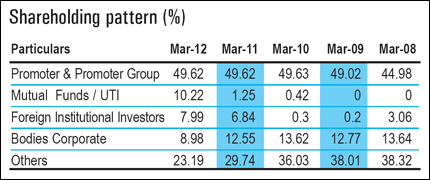
* SIL is one of the rare small-cap stocks that have managed to become a mid-cap amidst a choppy market. High institutional interest is partly responsible for sustained rise in its share price
* SIL holds a valuable 29.88 per cent stake in Supreme Petro (SPL); a listed entity and a leader in polystyrene business in the Indian market with a market share of more than 50 per cent. With an installed capacity of 2,72,000 tonnes per annum, SPL is also the largest exporter of polystyrene from India, exporting to over 80 countries in the world
Growth drivers
Two of its new plants, meant for manufacturing composite cylinders and protective packaging products, are expected to be operational by September 2012. In addition, capacity augmentation has been undertaken at existing plants. The total capital outlay for FY12 has been Rs 250 crore and the management has planned an expenditure of Rs 200 crore for each year until FY15.
* SIL is credited with pioneering various products in the industry which include Cross-Laminated Films, HMHD Films, Multilayer Films, SWR Piping Systems, PP Mats and many more
* The management intends to focus on value-added products (VAP) and high margin products rather than chasing volumes. This is reflected in share of VAP to total revenues which rose from 22.9 per cent in FY09 to 31 per cent in 9MFY12. This is expected to go up further
Concerns
Two major risk factors are volatility in raw material price and intensifying competition in the plastic products industry. Supreme's key raw materials such as PVC resin, polypropylene and polyethylene are primarily linked to crude oil, exposing the company to volatility in crude prices. Further, intense competition in the industry, especially from the unorganised sector which accounts for nearly 70 per cent of the market, will necessitate timely diversification into newer product categories to maintain margins as well as market position.
Financials
Though SIL has an asset-heavy model, there has been no capital raising in the recent past. Instead, it bought back shares in FY09 totaling to 22,16,300 which is as much as 8.72 per cent of the current outstanding shares. The revenues during FY08-12 have grown at a CAGR of 20 per cent, however, the EPS has clocked a CAGR of 37.50 per cent on back of increasing focus on VAPs and hence, the improving margins. The debt on the books as on June 30 stands at Rs 254 crore which translates into a comfortable debt to equity ratio of 0.36. This is in sharp contrast with last year's debt which stood at Rs 505 crore; which showcases business's ability as well as management's intention to keep debt at low levels. RoE has averaged at 33 per cent in the FY08-12 period. FCCBs totaling to $28 million (Rs 154 crore) are maturing in mid-2013 and 2014.
Valuations
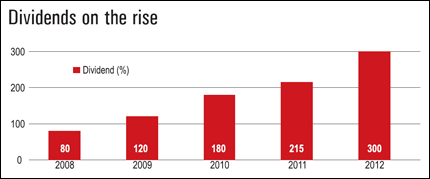
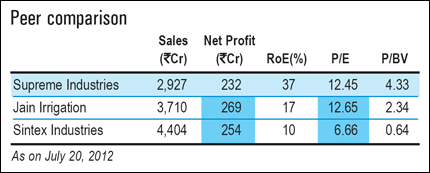
At Rs 237 a piece, SIL's stock trades at a P/E of 12.4. This is 10 per cent higher than its median P/E of 11.3. The price to book value is at 4.3 compared to 2.1 of peers like Jain Irrigation. The five year earnings growth of 37.5 per cent translates into a PEG of 0.33. Dividend yield is 2.53 per cent. If one were to consider only P/E and P/BV, the counter looks slightly expensive, however, a peg of 0.33 makes this counter very attractive. Indian plastic industry is still under-penetrated and is largely dominated by unorganised sector. Amidst this, an established brand, poised to benefit from changing dynamics of the industry, run by an experienced management, is bound to trade at rich valuation compared to peers. The stock looks attractive from 3-5 years perspective. BUY.
This article was originally published on September 19, 2012.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


