


There is a big sense of optimism around earnings expectations for the June quarter. Crisil Ltd, for example, says that revenue growth will hit a two-year high and operating profit growth will hit 13.5%. A good part of this jump comes simply because of a low base of the previous year.
If anything, earnings expectations have been considerably toned down. Consider the chart alongside. Bloomberg's consensus estimate for weighted average earnings of Nifty stocks for the next 12 months was ₹502.30 at the end of June. A year ago, the forward 12-month earnings estimate was ₹530 for the same set of stocks. Indeed, the forward 12-month earnings estimate was ₹498.68 two years ago and it's only marginally up since then.
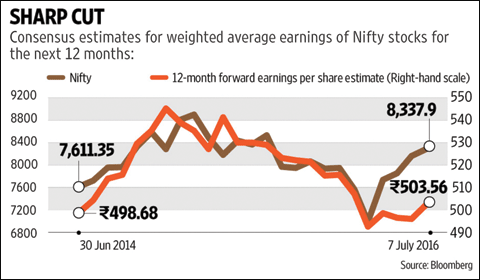
This not only reflects diminished expectations but also the disappointments of the last couple of years when actual performance lagged estimates. To take just one example, at the start of fiscal year 2016, analysts had an earnings estimate of ₹527 for Nifty stocks for that year. The actual earnings per share for FY16 was ₹368.
Now, theory says that the markets are shaped by future earnings expectations. Indeed, the chart alongside shows precisely that, with the Nifty closely tracking 12-month forward earnings expectations most of the time. Note though the sharp deviation between the two series since March this year, with the market running well ahead of earnings expectations. In other words, market valuations have expanded considerably. For the rise in the markets to sustain, earnings must catch up. The good news is that for the first time since early 2015, earnings estimates are no longer being revised down and indeed have shown a modest increase.
On the other hand, if even these toned-down earnings expectations are dashed, there is a big scope for disappointment despite the promise of continued liquidity after Brexit. To take just one reason, there is a big likelihood of margin compression in many industries as commodity prices have started inching upwards.
Some sectors such as realty and metals seem to be setting themselves up for such disappointments. Over the last six months, 12-month forward earnings estimates for the S&P BSE Realty index have risen by 19% compared with a flat line for the benchmark Sensex. For the S&P BSE Metal index, this increase was close to 14%. The stocks have also risen considerably; thus, if these earnings forecast are missed, expect a sharp fall.
In arrangement with HT Syndication | MINT
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


