


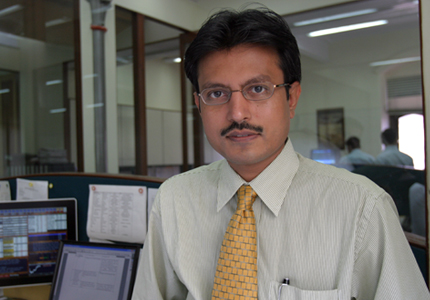
Nilesh Shah in an interview with Larissa Fernand, discusses the problems facing India, catalogues the solutions, lists his sectoral preferences and places the onus of getting the country on the high growth path on the government.
What hindrances do you see to the Indian economy’s growth?
In a very simple sense, I see execution as the problem. Or rather, the lack of it. Everyone knows what the problems are. Everyone knows we have infrastructure bottlenecks. And, more importantly, everyone knows what the solution is. We just need good execution. From being argumentative, we need to become executioners. Roads are not built by talking. Mumbai cannot become Shanghai by dreaming. It will require real actions on the ground. The kind of movement which we did to gain Independence or for achieving the Green Revolution, that same kind of dedication is required for execution.
How big a problem is our fiscal deficit?
Our fiscal deficit is funded out of domestic debt, not international debt. So the government always has the option of improving the tax efficiency by collecting more taxes from individuals. Then the deficit will resolve itself. Our tax-to-GDP ratio is one of the lowest in the peer group, which means Indians as a community are not paying appropriate taxes. If we can improve this ratio, the deficit will drop to that extent. We also have a reasonable size parallel economy which, if integrated into the main economy, can help contain the deficit.
The other way to tackle the deficit is by reducing expenditure. The issue is, can the government utilise its spending properly. There is leakage in the system and money is not being spent appropriately. If we can improve the utilisation process and plug leakages, the deficit will come down.
So by increasing income and effectively managing expenditure, we will be in a much better fiscal situation. It cannot happen overnight, but if it happens over the next 5 to 10 years, then our deficit problem disappears.
The latest GDP figures were encouraging. How dependent are we on the global economy?
I think over the past decade we have demonstrated to the world that our growth is far more internally dependent and domestically impacted, rather than by global factors.
During the Asian crisis of 1997, many countries in our peer group suffered. We still posted a healthy growth of 6 per cent. In the 2008 credit crisis, again when some of our peers suffered heavily, we still posted a 6 per cent growth. So during both periods, when the global economy was in reverse gear, we have shown that we are driving in third or fourth gear, if not in the fifth gear.
Economically, to a large extent, we are independent from global turmoil. I am not saying we are immune; we will get impacted but not as severely as other countries.
The economic impact is far more muted than the market impact of a global crisis. Historically we have seen how the market impact is far more significant. In 2007, when liquidity was sloshing around in our system, we jumped up along with global indices. In 2008, when liquidity fled, our market crashed more than other emerging markets. In 2009, when the bounce-back occurred, we were again higher.
So the economy is less dependent on the global factors but markets are more interlinked with the same.
How do you see the market panning out this year?
In 2007, no one could have predicted the market rising so high. In 2008 no one could have predicted such a sharp correction. The bounce back in 2009 too caught everyone unaware.
That proves that we have a hat-trick of failure in market predictions. So 2010 will be no different, considering everyone’s inability to predict the direction of the market.
Do you see 2010 difficult from an investing perspective?
Yes, at 17,500 levels the broad market is trading at the higher end of its fair value, or may be at fair value plus level.
We are not in a situation like February 2009 where you could move lock, stock and barrel into equity. And that too with a shorter term view. So when the market itself has become fair value plus, most of the sectors are also at that level. So one has to work really hard to find companies which are still at reasonable valuations and where the downside is protected.
Will you bet heavily on mid caps this year?
Our focus on 2010 is more stock specific calls, rather than sector calls. Last year was like a rising tide when everything moved up. Though one does attempt a balance between sectors and stocks, last year was far more driven by sector calls.
The Telecom tariff war resulted in a sector call since it impacted every player in the sector. The call on the Technology side was driven by global growth revival and currency movements. Here too every single player in the sector was impacted. So while bottom-up was not missing, 2009 was more about top-down calls.
This year, top-down will have limited impact and bottom-up stock picking will have a greater role to play.Now there is no tide to push up every boat. Each one will have to steer themselves in the direction they want to. The market will not reward across the board, one will have to put in an effort to generate returns.
That is your view on sector calls. What about market cap?
The difference between large and mid cap valuations is reasonable, as of today. It’s neither very cheap nor expensive. On an average, mid caps have traded at a discount of 10-40 per cent to large caps. Today they are trading at a 25-28 per cent discount.
So we will focus on quality mid caps where we see opportunity and growth and valuations are reasonable. We will continue to look at mid caps but will not be overweight on mid caps across our portfolios. We will have a reasonable allocation to mid caps.
Which is a sector which you are willing to stick your neck out for?
We believe in Telecom, looking at its underperformance and future potential. This sector has underperformed the market for more than a year. It is probably the only sector where stocks are still available at prices lower than what they were at the start of 2009.
The cut throat competition between telecom players has resulted in huge amount of losses for the players. This will not go on forever. They will not work as charitable trusts. They will soon begin to focus on profitability. Today’s price has factored in an extreme pessimism that the tariff war will last forever. Like the detergent price war ended, the telecom tariff war will also end. And that is the time the stocks will benefit from earnings growth as well as re-rating. There is short-term pain because telecom tariffs wars are not going to end tomorrow. But there is longer-term gain.
As Sir John Templeton said, when everyone is selling, it’s time to buy and when everyone else is buying, it’s time to sell.
Any other sector?
Though it has recovered in early January, there is some value left in mid cap cement stocks. Secondary market deals of promoter stakes could happen at a much higher price that what is being quoted in the market. There is talk in some investment banking circles about acquisition interests which are at a much higher valuation than what is being quoted in the market. So when that kind of acquisition takes place, these stocks could get re-rated. Please also remember that cement volumes are growing but because capacities have come up they are putting pressure on prices. The market is discounting that these low prices are going to prevail forever. Eventually demand will pick up, supply will adjust and the price rise cycle will begin. The cycle could be 12 months away or 18 months away. If infrastructure execution picks up it could be just six months away. The market will discount it accordingly. If the cycle is six months away, the market will discount it today. If it is 18 months away, it may discount it after 12 months. But certainly there is downside protection on value left in this sector, specially amongst mid cap stocks.
Where will you be doing your bottom-up stock picking from?
There are host of companies which we will focus on in Technology, Banking, Auto, Energy and Pharmaceutical sectors.
Banking seems to be fairly popular amongst fund managers now.
Banking is fairly valued. Most of the public sector and private sector banks are trading near their all-time high valuation in terms of Price-to- Book (PB). Going forward, banks will deliver returns which are related to growth in their PB value and growth in their earnings. It’s unlikely that a re-rating of any particular bank can occur.
Banks are not like pharma companies which can produce a molecule or come up with a new discovery that result in huge profits. It’s more of a steady-Eddie business. So the returns in banking will come more from earnings generated and how they accrue to Book Value (BV). So return expectations will have to be moderated. One will have to pick up banks which are relatively cheaper vis-à-vis their peers.
What was the reason for bank credit growth falling? Do you see it picking up?
Banks have sanctioned lot of money. There are no disbursements as the actual execution on the ground is not happening. Other than mortgage and auto loans and agriculture, there is no other sector demanding additional credit. Infrastructure companies have not been taking disbursements because projects are not getting executed quickly enough. The manufacturing industry had benefitted from the drop in commodity prices. They have tightened their belts well so that their working capital requirement is reduced. All this has resulted in a slowdown in bank credit growth. If the execution improves, credit will pick up.
Is it that banks have now become enthusiastic lenders to mid cap firms?
Banks have always been lending to mid cap firms and Small and Medium Enterprises (SMEs). Venture capital provides equity, not debt. Debt for SMEs comes from the banking system.
Eventually most banks get their bread and butter from lending to SMEs because of pricing power. So they create a blend of safety and return by balancing a lending portfolio to big and smaller firms.
You also mentioned Auto. Don’t you see auto sales being hit once the stimulus gets rolled back?
Clearly auto sales have been supported by the excise cuts which were given by the government in February 2008. Then there was the Sixth Pay Commission hike which took place between 2008 and 2009. So demand was supported by a reduction in excise duty and the pay hikes.
Going forward, the excise duty cuts can be reversed. Today a car is considered a luxury item so there is a strong case for reversal of excise duty cuts. The pay commission benefits will ward off. So auto companies will face some impact on their growth numbers.
What is the cause of commodity prices rallying? Is it that monetary flows are causing an asset price build up?
The demand-supply mismatch and dollar depreciation coming into play resulted in Metals moving up significantly. Commodities worldwide are quoted in dollar terms, so with the dollar depreciating, prices have appreciated. Secondly, a lot of the capacity had to shut down due to un-remunerative prices. So supply was withdrawn in steel, aluminium and oil, though demand started rising as the global economy revived.
Is it that India is just a price taker where commodity prices are concerned?
In oil, yes, we are price takers because we don’t produce sufficient amounts for domestic consumption. In most of the Metals we are reasonably self sufficient. Take the case of steel; our imports are more for specialised steel. But India can produce enough steel for domestic requirements.
In zinc and aluminium too we are reasonably self sufficient. Obviously India will have to create capacities and secure raw materials like China has done to ensure that in the future too we retain similar independence. The kind of time which we take to set up a steel plant for POSCO or Arcleor Mittal does not bode well for the future.
Going ahead, do you think the better part of the commodities rally has been spent?
If I have to take a medium term call, I think that the better part of the rally has neared its end. Economies have recovered globally, but not well enough to sustain higher metal prices for long.
The dollar has depreciated and will eventually depreciate but there is a possibility of a technical rally. The consensus is on dollar depreciation. Normally, when the market is so consensual there is the possibility of a technical rebound.
So weaker growth and appreciating dollar movements could probably bring down commodity prices.
What is the reason for current food inflation?
Food inflation to some extent has been induced by Minimum Support Price (MSP) increases given by the government. To add to it was the bad monsoon in 2009. It could also be the result of a mismatch in demand and supply of certain products as income level has increased but supply is lacking.
So the inflation is purely due to supply side issues rather than demand?
While the factors I mentioned are the prime causes, we must remember that we are faced with excess liquidity in the banking system. In September-October 2008, the liquidity crisis hit the Indian economy. Suppliers’ credit was withdrawn because of the global credit crisis. That funding had to be arranged from domestic resources. Which is why the Reserve Bank of India (RBI) released up to Rs 4,50,000 crore into the Indian banking system by a series of actions. It was the most unprecedented action by the RBI to provide liquidity in the banking system so that the economy does not get starved out of liquidity. It was like a massive blood infusion.
Over a period of time, the economy absorbed some liquidity. Then some liquidity returned as the overseas credit flows began to ease and the credit crisis began to ebb across the globe. The RBI has still not withdrawn the entire liquidity.
So the result was a situation of excess liquidity in the system coupled with high inflation.
But in such a situation, which is predominantly supply provoked, would the implementation of monetary policies help tackle inflation?
Milton Friedman said that all inflation is ultimately a monetary phenomena. So somewhere there is a conventional economic sense which says that eventually all inflation is a function of excess liquidity in the system.
Though the RBI knows that food inflation is not caused by monetary supply alone, it also has to ensure that future inflationary expectations don’t jump up because of excess liquidity in the banking system.
So the rise in interest rates will not be to control food inflation but to take out liquidity and control inflationary expectations which could get build up due to excess liquidity.
In India we have normally followed the path of controlling liquidity, raising rates and curbing demand to control inflation. We have not experimented with the Chinese style of inflation management of giving credit, rapid execution, low interest rates, high liquidity and excess supply to meet demand to control inflation. The RBI can provide high liquidity and low rates but the government will have to provide rapid execution so that we can tackle inflation on the supply side.
What is your take-away from the RBI’s monetary policy announcement and the CRR hike?
From the bond market point of view, the Cash Reserve Ratio (CRR) hike is just a little more than expected. The market had already factored in a 50bps hike in the CRR, which was over shot by another 25bps. However, there is sufficient liquidity in the system which, including the government surplus, will be over Rs 1,00,000 crore to Rs 1,20,000 crore, that will help absorb the impact of the hike. The way forward will be driven by the government’s borrowing programme to be announced in the upcoming Budget. It will be the fiscal consolidation roadmap that will be crucial in influencing interest rates more than the monetary policy.
On the equity market side, the market was expecting a control on inflationary expectations which the RBI has addressed effectively with the current liquidity tightening. The market stabilizing after the initial drop post announcement is endorsement of this view. This apart, the RBI has clearly indicated its focus on maintaining a balance between inflation and growth. It has also provided an optimistic assessment on growth at 7.5 per cent for FY 2011, which provides comfort to local and global investors.
This interview appeared in the February 15-March 14, 2010 issue of Mutual Fund Insight
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


