


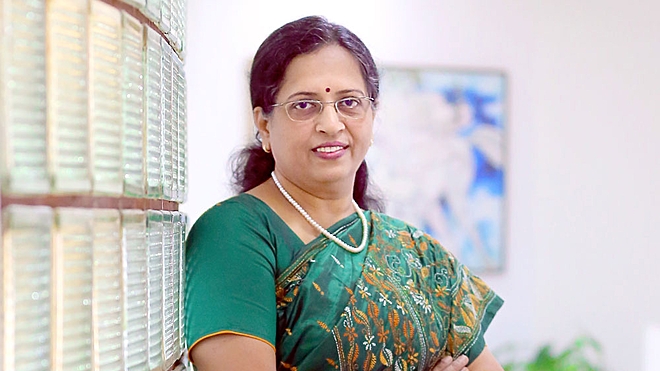
As private-sector mutual funds celebrate their 25th birthday in India, we decided to catch up with a fund house that has been a rock-steady performer for over 50 years - UTI Mutual Fund. Swati Kulkarni, Executive Vice President and Fund Manager - Equity, at the fund, exemplifies its non-sensational approach to wealth creation.
Having joined the research team at UTI in the frothy markets of 1992, Swati has been a fund manager since 2004, displaying a rare stability and loyalty in an industry where fund managers like to shuffle jobs every three or four years. From my many interactions with Swati over the years, I know that she hates talking about herself. So, I kick off our chat with more generic questions.
No cash calls
Most fund managers who currently manage mutual fund assets have seen one or, at best, two market cycles, but Swati has lived through four entire market cycles. What are the lessons from past cycles that she applies even today?
"I think my biggest learning is that timing the market is a myth and cash calls are not very helpful in generating alpha. Let us say you take a cash call ahead of time and it has a negative attribution on your performance. Typically, this negative impact on performance is far more than the alpha that you can hope to generate through the timing of such calls. In overheated markets, I have found that it is far better to own defensive stocks or value stocks with limited downside. Once you are confident of your holdings, stay patient through periods of underperformance and that eventually pays off."
She adds, "Markets create excesses and you should not get carried away by either excessive pessimism or optimism. What is in fashion typically gets overvalued and what is in distress gets undervalued over time, creating alpha-generation opportunities. You need a good investment process to identify such mispricing and also a cool head to hold onto these through the cycles."
So how do you manage to capture the upside and be defensive too? "That is why I think you need a diversity of strategies and styles within every AMC. You cannot have all schemes following growth or value styles; you need to have a mix of both."
Info overload
How has equity research in India changed in the last three decades? Has stock selection got easier with the easy access to information?
Swati says that she finds the information overload more challenging than the earlier lack of information. This has made it very important to filter out the noise while evaluating any stock. But more importantly, "Earlier, if you were right in sector selection, you could generate alpha, but today it is far more stock-specific. In every sector today, the divergence in returns between the best and worst stocks is extremely high. Take automobiles or banks and you have seen that divergence playing out. Therefore, getting your sector calls right is no longer enough, getting your stock selection right is the key."
When it comes to retail reach, UTI Mutual Fund is still the kingpin of Indian mutual funds. So how has investor behaviour changed over the years? Swati says that retail investors have always been more patient than HNIs and tend to stay invested for long periods. Of late, they are increasingly taking the SIP and STP routes to investing.
"But the other recent trend we have been observing is that investors are increasingly opting out of dividend options in equity funds and preferring the growth option. Before the tax changes in the budget, we noticed a shift from the dividend payout to reinvestment plans. Now the shift is in favour of growth plans. This indicates that investors are increasingly seeking wealth creation rather than regular income from equities. I have personally observed both trends in UTI Mastershare." Mastershare, the oldest equity scheme in operation, is known for its 31-year dividend track record.
Financial history helps
UTI Mutual Fund's approach to stock selection is quite textbook-ish, focusing on earnings growth, ROE, ROC, etc. But does too much focus on past metrics lead to missing out on turnaround opportunities?
Swati urges me to check out UTI's rebooted investment process. "After Vetri (Subramaniam) joining us (as Head of Equities), it is quite well-articulated on our website."
"We do use financial history to assess businesses. It has its uses. One, we use it to judge the inherent profitability and characteristics of a business. Two, it helps us judge the relative superiority of a business compared to peers in a sector. Three, it helps us assess if the implied growth assumed in the stock valuation is realistic and achievable. If a company's past growth rates and its maximum growth rates are nowhere near what the current valuation implies, then you need to be cautious."
"History can also help you identify turnaround possibilities where a company is going through a temporary bad patch. If a business has had a certain level of profitability in the past, which is depressed right now, it could indicate its potential."
So what's the forward-looking aspect? Basically, UTI classifies all the stocks in its universe into three tiers based on their operating cash flow and ROCE for the last five years. Stocks averaging an 18 per cent plus ROCE are classed as R1 stocks, those averaging 10-18 per cent are classified as R2 and those with lower ROCEs are bracketed into R3. Based on these buckets, Swati says, "We make an independent assessment of where a company's financial metrics are likely to be in future. What we have observed is that companies with consistent cash flows and high ROCE in the past have a high probability of continuing to throw up cash and sustaining high ROCE in future. Also, companies that migrate from R3 to R2 or R1 tend to generate big stock price returns. But one needs to spread the bets on these as the probability of such migration is low. So, while you build financial models to assess the wealth creation potential, it is essential to look in the rear-view mirror to judge the ability of companies to fulfil your expectations."
Swati says that UTI schemes are now clearly positioned along these lines. For instance, UTI Equity Fund invests mainly in R1 companies. UTI Mastershare invests mainly in R1, with some exposure to R2 companies. UTI Midcap Fund and UTI Core Equity Fund look mainly to capture the companies moving to higher ROCE band from R2 or R3. This ensures a good diversity of styles between growth, growth at a reasonable price and value.
Secret sauce
MNC funds are the rare category of thematic funds in India that have consistently beaten other diversified categories. UTI MNC Fund sports an impressive 10-year CAGR of 20 per cent and the Nifty MNC Index, with 18 per cent, is much ahead of the Nifty 50 or even the Nifty Midcap 100 index. So what's the secret sauce to MNC investing?
Swati thinks management meetings are overrated. "MNC funds bring a very differentiated portfolio to a space where most other equity schemes feature common names. We find that the MNC space features quite a few wide-moat companies with strong entry barriers. The companies typically have leading positions in their sectors. The parents also provide export opportunities and are able to invest in brands and distribution. They also feature very strong balance sheets."
There are tailwinds for MNCs, too. "Over the medium term, the shift from unorganised to organised sector in many sectors will benefit MNCs. Earlier, when the cyclical recovery in the economy was not evident, we had more consumer MNCs in the portfolio. In the last three years, we have added consumer-discretionary names and cyclical-recovery plays. In industrial MNCs, there is a strong focus on profitability rather than winning market share. We have preferred to stay with such names rather than those that have been aggressive in chasing large order books."
The other specialty fund that Swati manages is UTI Dividend Yield Fund. But dividend-yield strategies in India are a very different animal from those like Dogs of the Dow used in the western world. So, does UTI shoot for the highest dividend-yield names in the market?
"We divide our stocks into three buckets. First, there are companies with fair dividend yield and good growth prospects. Two, we look at companies with dividend yield that is twice the Nifty's dividend yield. Three, we buy companies with a possible increase in earnings in future that could improve dividend yield. I would say two-thirds of the portfolio is focused on growth at a reasonable price and yield. Only about 10-12 per cent of the portfolio would be in the conventional very-high-dividend-yield stocks."
Swati offers a good argument for why one cannot apply the developed-market approach to dividend-yield investing in India. "Here, relying only on dividend yield for returns does not make sense because fixed-income securities already yield 7-8 per cent. In the developed markets, even a 2-3 per cent dividend yield is a good return for stock investors because returns on fixed income were close to zero until recently. In India, we need a mix of dividends and capital appreciation from such stocks to deliver a decent return."
Personal lessons
I get to my pet subject. Multi-baggers such as Asian Paints, Eicher Motors or P&G show us that the most difficult part of equity investing is not buying or selling but holding on when stock prices go nowhere. So how has Swati dealt with this challenge?
"I think this is a function of how well you have thought through your investment rationale. The more you do, the more conviction you have to hold on. For instance, in the names you mention, if you identified clear drivers for growth, like low penetration levels, you would have had the conviction to hold through a bad patch. If you see clear entry barriers in terms of unique offerings, technology or brand, you get the conviction to hold on, too. We have seen with many of our mid-cap IT holdings that they did not perform initially. But the huge cash per share was a plus and we held on and that paid off," she says.
Swati is a keen volleyball player right from her school days. What are the lessons from sports one can apply to fund management?
Her answer is: "Not many people appreciate that fund management is a team effort. If you are a team player, that helps deliver consistent results, rather than when you take all decisions yourself. We have seen in our industry that there is no fund or manager consistently at the top. Everyone has an equal opportunity to win."
Ask Value Research 
 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


