




The last one year has been phenomenal for the industry and for our fund house, with the assets growing by almost a third, over 50 per cent growth in SIP folios and over 100 per cent growth in the SIP book.
Managing return expectations
During the course of our roadshows with large groups of IFAs and through our media interactions, we have been emphasising that while equities will still be able to give inflation-beating and bank FD rates-beating returns, investors shouldn't expect the high returns of the past three years to sustain and should get comfortable with low double digit returns from equities over the medium term.
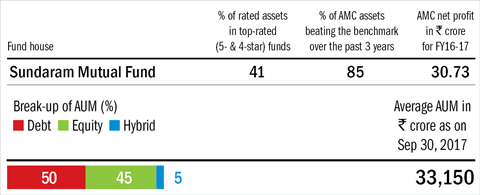
As has been our past track record, we have been launching a series of four to five-year closed-end funds, which enables us to expose investors to undervalued or reasonably valued sectors. Also, in our diversified funds, we ensure that there is reasonable representation to sectors in the economy with varying valuations. Further, the underlying theme of our investment process continues to remain GARP (growth at reasonable price). In many of our mid and small-cap funds, we adopt a bottom-up stock-picking approach, with a four to five-year outlook on the underlying company, which ensures that the resultant sector allocation in our funds is well anchored around company growth prospects.
Rising industry assets
The challenges created by rising assets are to maintain an appropriate balance between medium-term, high-valuation sectors and longer-term, reasonably valued sectors in order to ensure outperformance relative to the benchmark while catering to long-term wealth-creation needs.
Growing clout of domestic funds vis-a-vis FIIs
As one has observed, when FIIs sold off Indian equities during events such as US elections, demonetisation, UP elections, Indian budget, etc., the mainline indices have seen much narrower falls compared to earlier years. This demonstrates that domestic funds, which have a much longer time frame closer-to-the-ground view, have stepped in to buy their preferred stocks and sectors at such times.
Outlook for equity and debt
We believe that large-cap earnings should bounce back after a four-year hiatus and small and mid-cap companies should continue their growth trend. Amongst sectors, we are overweight on consumption, financial services and infrastructure with a longer-term view. We remain underweight on IT, pharmaceuticals and telecom.
We expect Indian domestic yields to remain range bound. We recommend that with volatility being the cornerstone in the coming year, and looking at the risk-reward payoff, the fixed-income investor is better off in short- to medium-term funds with an accrual focus.
This article was originally published on January 03, 2018.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


