
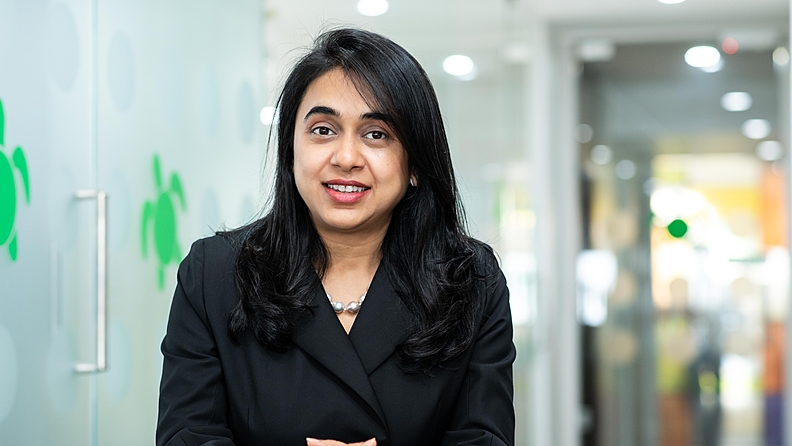
05-Nov-2026 | Ruchira Sharma

PPFAS Wealth takes its simple way to wealthy families
The fee is set in rupees on day one and does not rise when the portfolio does
PPFAS Wealth offers rich families the same advice PPFAS Mutual Fund gives everyone: keep your money simple. What a family pays for is someone who keeps it simple as life changes, for a fee that does not grow with the portfolio.
In 2013, as PPFAS launched its mutual fund, it stopped taking new portfolio management clients. Its founder, Parag Parikh, said the firm creates rich investors and does not chase them. In 2024, the group relaunched PPFAS Wealth to advise wealthy families. I asked Khushboo Neil Parikh, its President, what changed.
The plan never changed, she said. The pause was forced. Soon after PPFAS got its mutual fund licence, the minimum net worth for a fund house went up from Rs 10 crore to Rs 50 crore. Then the firm lost Parag Parikh. It put everything into the fund. Old clients kept asking when the advice would return.
One fund is not a family plan
A salaried man with one equity fund, a debt or hybrid fund and a liquid fund for emergencies is well set. Add a wife and two children and the questions multiply. A move to a bigger flat raises monthly spending. A child picks a university abroad over one in India. A business family spread across three generations needs something harder: one family charter that everyone accepts. PPFAS Wealth handles planning, insurance, estate and succession under one roof.
The fee does not follow the market
Most clients use its non-discretionary PMS, where the firm carries out each transaction the client approves. The fee is a fixed rupee amount, set at the start from the portfolio’s size and the work involved. If a Rs 50 crore portfolio becomes Rs 60 crore, the fee stays the same, and there is no profit share. Clients see three years of fees in advance. No regulator asks for this. The firm chose it.
Some clients hold only PPFAS schemes. Others hold none. If a family’s portfolio already looks like a PPFAS scheme, she said, she will not add one.
Too many funds, too much faith in debt
Two mistakes keep turning up. Families add equity fund after equity fund and call it diversification. Five equity funds from five fund houses spread the risk of any one fund house, and nothing more. The second is the belief that anything labelled debt is safe, whatever its structure.
Talk about the will while you can
Indian families avoid the question of kisko kitna jayega, or who gets how much, while the elders are alive. “When they are not there, it is all havoc and it’s full Sholay,” she said.
Parag Parikh did the opposite. He discussed his will with his sons, explained his choices, took their views and updated it often. The family thought the talks pointless. After his sudden death, those talks held the firm together. “Everyone had clarity,” she said. “Each member knew their role.”
Her lesson for a Rs 10,000 SIP investor is the one PPFAS repeats everywhere. Complicated products look sophisticated, so people assume they earn more. Often they do not. Set an allocation that fits your needs, review it and stay with it. “Investment should be boring,” she said. “If it gets exciting, that means you’re gambling.”
Other Videos

When the buyer is also the seller
· 8,858 Views
'This decade may belong to mid-tier private banks'
· 3,153 Views
'The market is clearly far more attractive today'
· 1,663 Views
'Investing is a marathon, not a sprint'
· 4,257 Views
'Correction could be more prolonged in mid and small caps'
· 10,121 Views
'Large and mid caps look better placed than small caps'
· 9,524 Views
'Even after the correction, mid and small caps aren't cheap'
· 11,136 Views
'Small-cap index gave 20%+ returns over last 3 and 5 years'
· 16,853 Views
Why did Mirae's small-cap fund outperform in a tough 2025?
· 34,598 Views
'We don't see a major market downturn right now'
· 14,196 Views
'Half the battle is won if the buying price is right'
· 19,446 Views
'Margin of safety looks better on the large-cap side'
· 21,125 Views
'Growth is stronger, earnings are catching up'
· 37,512 Views
'More value has emerged in large caps this past year'
· 42,576 Views
 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


