


GAIL (India) Ltd's share price has gone up 7.3% in the last two trading days.
On Wednesday, the Petroleum and Natural Gas Regulatory Board (PNGRB)'s tariff order increased the company's KG basin pipeline tariff to Rs.45.3 per million British thermal units (mBtu) from a provisional tariff of Rs.5.6 per mBtu. That led to the spike.
As Nomura Financial Advisory and Securities (India) Pvt. Ltd pointed out in a note to clients that even though the KG network is one of GAIL's smaller networks and accounts for less than 5% volume, this large hike can raise GAIL's FY17 earnings by more than 3%.
"Importantly, investor confidence would increase, that forthcoming tariff orders will also lead to tariff hikes (though not such steep ones)," adds the Nomura report. Considering that the pipeline network's useful life (25 years) is ending on 11 February 2017, earlier period adjustments would be taken into account, leading to a sharp tariff hike for the KG network.
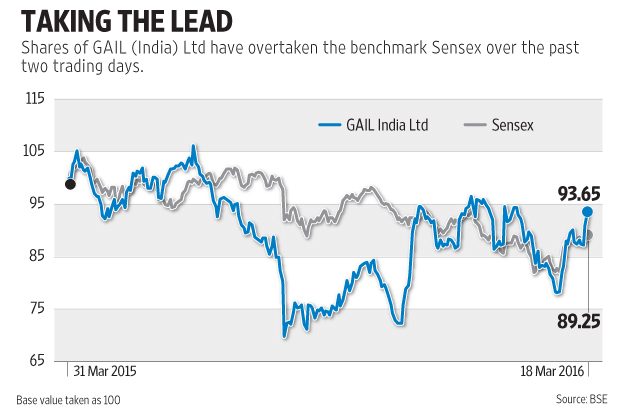
Despite the recent increase, the GAIL stock is still 6.4% lower so far this fiscal. However, from its yearly low in August, the share price has appreciated by one-third. The renegotiation of Qatar's RasGas LNG contract is a key reason for the optimism. Input costs of GAIL's petrochemicals business are expected to reduce as LNG prices have been renegotiated at a lower price.
As Antique Stock Broking Ltd pointed out, the stabilization of the expanded petrochemicals capacity in the first half of 2016 would lead to higher utilization, which would ensure lower fixed unit operating cost and a higher revenue over FY17-18 for the business. Nevertheless, the sharp decline in petrochemical prices and slow pace of production ramp-up are metrics investors should watch out for. For the nine months to December, the petrochemicals business has posted earnings before tax and interest loss of about Rs.700 crore. Weak realizations and higher input costs are some factors to blame.
"We have marginally revised up our Ebitda estimates in FY16/FY17 by ~5% building in a) better petrochemicals Ebitda on account of volume ramp-up/ cheaper spot prices b) a pick-up in gas trading segment due to increase in spot volume," said Ambit Capital Pvt. Ltd in its last quarter results review. Ebitda is earnings before interest, taxes, depreciation and amortization.
Currently, the GAIL stock trades at about 13 times estimated earnings for fiscal 2017, not cheap for a utility company of this size. Lower than expected transmission volumes, or tariff hikes, are key risks.
In arrangement with HT Syndication | MINT
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


