




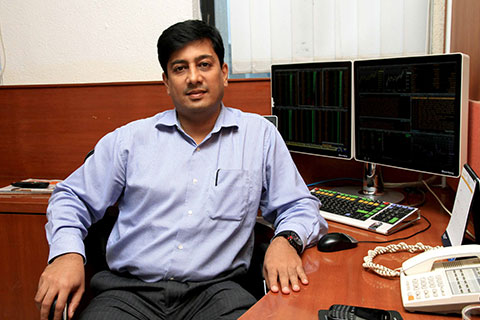
As one of India's storied equity fund managers, Harsha Upadhyaya, CIO (Equity) at Kotak Mahindra AMC, is always immersed in finding out the micro impact from macro developments.
Kumar Shankar Roy caught up with him in an interview just days after Finance Minister Arun Jaitley unveiled the all-important budget.
Occuring in the backdrop of demonetisation, the annual financial exercise carried high hopes. Upadhyaya feels the budget was focused on reviving sectors that saw collateral damage due to the government's bold initiative to cleanse the economy. He has positioned his portfolios towards domestic themes, and expects state elections, GST implementation, and US Fed actions to guide markets in the near term.
Has the budget done enough to reduce the impact of demonetisation? The expectations of a windfall for the RBI were absent in the budget.
This budget has focused on reviving those sectors of the economy which were adversely impacted due to demonetisation. The lower end of consumption demand should look up going forward as tax payers at the lowest slab will pay less tax and will have higher disposable income. The focus on infrastructure creation and affordable housing should drive demand for cement, home-building materials and allied sectors while creating more jobs in the economy. The aggregate outlay for agriculture-related segments is at over Rs 1,87,000 crore, which will significantly benefit the rural economy.
Banks, autos and real estate have reacted positively to the budget. How sustainable are these gains?
The budget has focused on long-term improvements in the economy. Its plans seem very credible. If the plans are implemented effectively, then the gains will be sustainable. Immediate reaction to the budget or any event is generally driven by sentiments and liquidity and hence one should not read too much into it.
Are you excited about the government's plan to list IRCTC, IRFC and IRCON?
Government's intention of listing various public-sector enterprises is a welcome move. However, our investment interest in any new listing will be driven purely by company's growth prospects and its valuations.
From the point of view of a mutual fund investor, what are the positive takeaways from the Union Budget?
Clearly, this budget will try to revive the domestic economy post the demonetisation drive, which should support earnings recovery in FY18. Non-introduction of long-term capital-gains tax on equities or a change in the holding period, as feared by a section of the stock market, has also not materialised. No news is good news in this regard.
Are there any mild or major negatives in the budget that can hurt the stock market?
Ideally, a larger allocation (than Rs 10,000 crore outlined in the budget) towards recapitalisation of public-sector banks would have been good for the sector. There were some expectations of a cut in corporate tax starting next year, which have not been fulfilled. If at all we were to pick negatives, these would be the ones in our opinion.
Given the demonetisation impact, what is your view of the corporate earnings right now?
January-March 2017 quarter earnings could once again be mixed just like the previous quarter due to the temporary impact of demonetisation. We expect overall corporate earnings to normalise post March 2017 quarter. We expect earnings growth of around 14-15 per cent during FY18.
In terms of stock-market valuations, are we comfortably placed in the backdrop of economic-growth challenges?
With the recent rally in Indian equities, the market is slightly above fair valuations as compared to its historical-valuation range. This marginal premium is justifiable, given expectations of earnings recovery in FY18 and beyond, in our opinion.
As a portfolio manager, are you unnerved by the protectionist moves coming out of US? Info-tech and pharma sectors have been in the spotlight.
We had expected some of these developments post US election results. We have been carrying underweight position in both IT and pharma for more than two years now in our portfolios. We were cautious on these sectors due to their weakening fundamentals and regulatory issues. The recent protectionist moves from the US are added negatives.
How have you positioned your portfolios?
Our portfolios are tilted towards domestic businesses, which have high operating leverage and are seeing signs of a demand recovery. Most of our overweight exposures are in cement, auto, oil and gas, and private-sector financials.
What are the next big triggers for equity markets that fund investors should watch out for?
On a fundamental basis, market will be driven by earnings expectations and valuations over the medium to long term. However, events such as state elections, GST implementation, US Fed actions, etc., could present volatility in the short term.
After the post-budget rally, what, in your view, is the approach that fund investors should adopt, going forward?
We continue to advise investors to utilise SIP route for equity investments. Disciplined and regular investments are always helpful to beat short-term volatility and create long-term wealth.
Consumption has been big theme for quite some time. How are you approaching the sector and stocks, given the valuation concerns?
While we are positive on consumption-demand growth in the country, we are selective in this segment, given valuation richness. This is one of the segments where the earnings growth is expected to be higher than the average market earnings growth. If we can buy or add stocks at reasonable valuations in this segment, we can expect to outperform the market in general.
Ask Value Research 

 New episodes every Friday


 New Process Alert
 Seems like you've uploaded a wrong QR code. Please upload the QR code downloaded from MF Central platform.


